
Webull (BULL) Could Be 55% Undervalued On China Ties Selloff
Webull (BULL) is back in focus after its shares dropped sharply following a bipartisan House Select Committee on China report that raised national security concerns around the broker’s structural ties to Chinese entities.
The congressional report hit a stock that was already under pressure, with Webull’s share price down 39.5% over the past month and 28.1% year to date, and the 1‑year total shareholder return declining 53.5%. This signals that momentum has been fading despite recent product launches and partnerships on AI tools and social-market data.
Scan how other brokers and fintechs are reacting to similar regulatory and sentiment pressure by reviewing our hand picked 31 resilient stocks with low risk scores together with Webull today.
The sharp reset in Webull’s share price now sits against a business that still reports revenue of $672.3m and net income of $42.6m. Are investors repricing fundamentals, or mainly reacting to regulatory and sentiment shock as they weigh valuation next?
Most Popular Narrative: 55% Undervalued
The most followed narrative on Webull puts fair value at $13 per share, compared to the recent $5.89 close. This frames the current selloff against a far higher long term earnings and cash flow story.
Ongoing expansion into new international markets, including recent launches in Canada, Latin America, and Europe, is rapidly diversifying Webull's customer base and driving robust growth in assets under management (AUM). This supports future revenue and top-line growth. The successful launch and acceleration of subscription-based offerings such as Webull Premium and paid analytics products are already exceeding targets. These offerings combine higher daily trading activity and increased average revenue per user (ARPU) to boost net margins and recurring revenue stability.
See why 40 investors see Webull as 55% undervalued.
Result: Fair Value of $13 (UNDERVALUED)
Still, if retail trading activity cools or regulators constrain Webull’s international and crypto push, that upbeat $13 fair value narrative could quickly lose traction.
Find out about the key risks to this Webull narrative.
Another View: Webull Looks Expensive On Earnings
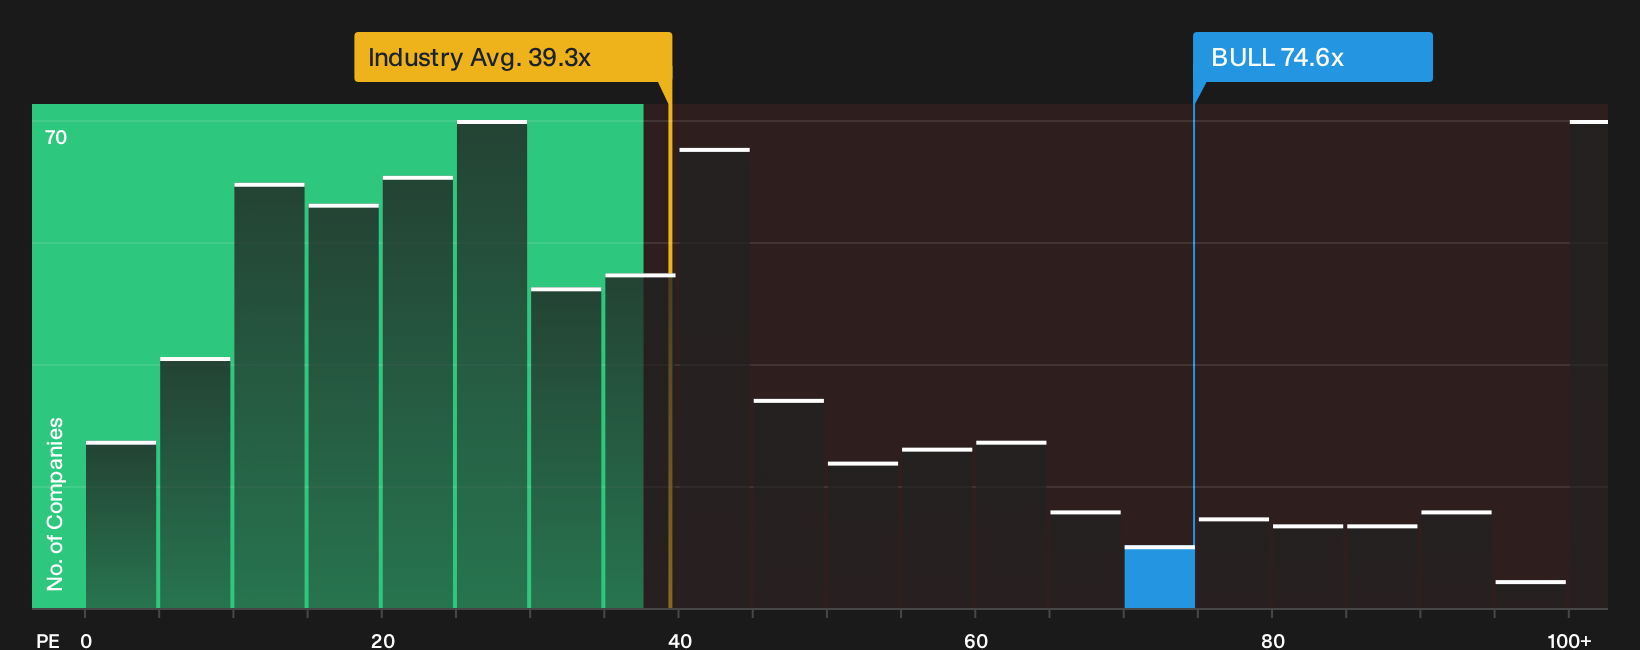
There is a very different picture when you step away from narratives and look at Webull through its current P/E. The stock trades on 74.6x earnings, compared with 39.3x for the wider US Capital Markets group and 15.5x for its peer set.
The fair ratio for Webull is estimated at 28.5x. That is far below where the shares trade today and suggests valuation risk if sentiment cools or growth expectations are revised. Which version of Webull do you put more weight on: the growth story or the current multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Webull can be confusing, so move quickly, look through the full data set, and weigh both the perceived upside and the caution flags yourself. To see those signals side by side, review the 1 key reward and 3 important warning signs.
Looking for more Webull-sized opportunities?
If Webull has sharpened your focus on risk and reward, do not stop here. Use curated screeners to spot other ideas before the crowd catches up.
- Target resilient companies by reviewing the list of solid balance sheet and fundamentals (25 results), which combines healthier finances with more durable business models.
- Hunt for mispriced opportunities using the 20 high quality undiscovered gems, which highlights strong fundamentals the market may be overlooking.
- Build a steadier income stream by scanning the 8 dividend fortresses, which focuses on higher yielding payouts with an eye on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com