
The Call Designer Brands Bulls Got Right
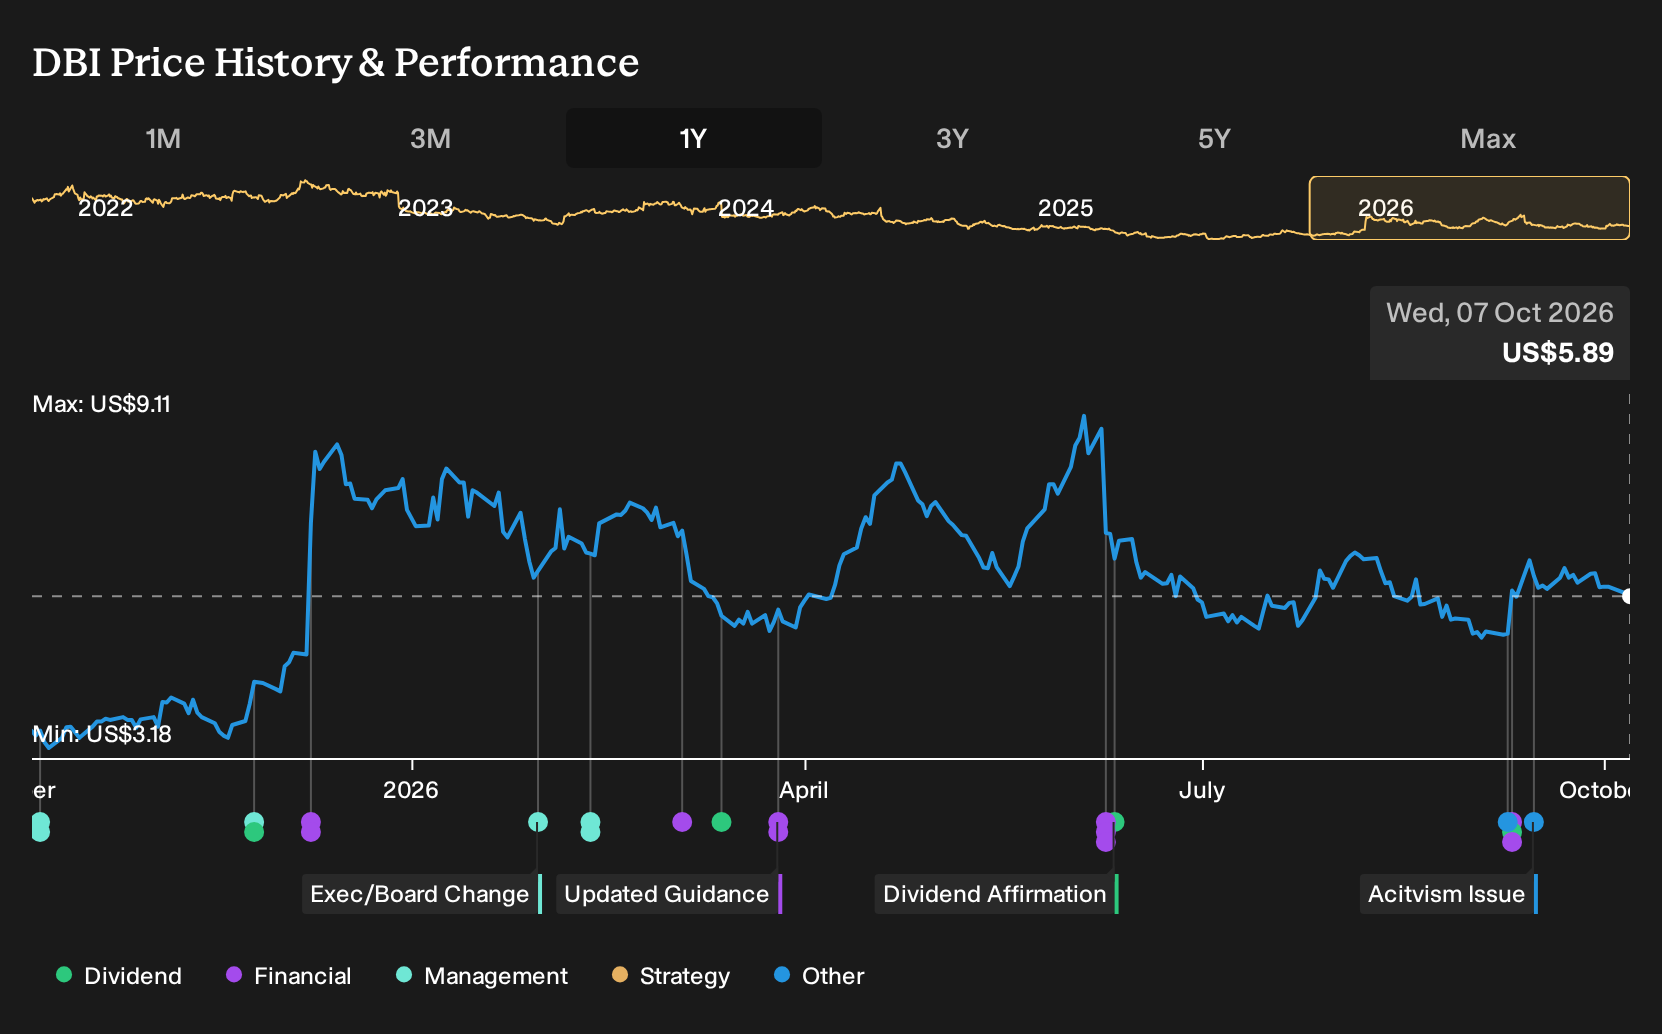
Designer Brands just posted a year where revenue slipped but net income and margins improved, an outcome that hardly screams effortless success. For Designer Brands shareholders, the return over the past year was 75.0%, including dividends. If you had bought on 7 October 2025, you faced falling comparable sales, pressure on gross margin, and no near term path to profitability on analyst forecasts. So what exactly in the early evidence made that risk look worth taking?
Designer Brands has already moved. See which of 29 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Weigh On Designer Brands
The shares cost US$3.4 at the start of the period, and anyone looking at Designer Brands then was choosing between two very different stories about where the footwear retailer might head next.
The bullish narrative pointed to a Fair Value of US$5, a rough guide to what believers thought the stock could be worth if things played out their way. It was built on assumptions like revenue growth of 1.1% a year and profit margin rising toward 4.4% as omnichannel investments and owned brands scaled.
The bearish view centred on a Fair Value of US$3 and leaned on concerns such as ongoing sales declines and an 8% drop in comparable sales. Those trends left heavy physical stores, promotions and sourcing exposure looking like persistent margin risks.
What The Results Changed For Designer Brands
The most concrete development was the Q2 2027 print, where Designer Brands reported total revenue of US$730.631m and net income of US$17.557m, with net margin at 2.4%. That margin level, up from 1.4% on revenue of US$739.762m a year earlier, lent some support to the optimistic focus on cost control while still echoing the cautious concern about pressure on the top line.
The lesson here is simple. When a thesis leans heavily on margin improvement, track both net income and the percentage margin together, even if revenue softens, to see whether efficiency gains are actually coming through.
What Designer Brands' Run Leaves Open Today
Designer Brands now trades at US$5.89, and the story has shifted from survival questions to whether that price better reflects sentiment or business progress. The clearest hard evidence is that net income in Q2 2027 was US$17.557m on revenue of US$730.631m, with net margin at 2.4% compared with 1.4% a year earlier.
Shareholders saw a strong one year gain while the retailer delivered higher profitability on a smaller top line. The key assumption to test is how much further margin improvement the current valuation quietly bakes in.
The return is settled. The valuation question is not. Pinpoint what our model says Designer Brands is worth.
Looking Beyond Designer Brands
Designer Brands lives in a world where retail efficiency really matters. That pressure shows up in constant debates about stores, inventory and fulfilment.
Behind the scenes, another giant is attacking a similar problem from a different angle. It spends heavily to automate logistics and sharpen demand forecasting.
The effort is not only about cheaper delivery. It also focuses on helping shoppers quickly locate what they want and finish a purchase.
If that model keeps reshaping expectations around speed and convenience, what happens to retailers following older playbooks?
That argument has a Narrative and a number behind it. → See the company one Narrative values 73% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com