
Packaging Corporation Of America (PKG) Files Dam Analysis As Undervalued View Holds
Packaging Corporation of America (PKG) recently filed a dam failure analysis for its Grandmother Falls Hydroelectric Project, recommending a shift in hazard classification, a technical move that could reshape how investors think about related operational risks.
For investors watching Packaging Corporation of America’s share price, the recent dam failure analysis arrives after a modest pullback. The stock is down 4.21% over the past 30 days but still shows a 7.64% year to date share price return and a 91.86% total shareholder return over five years. This suggests that the market has been reassessing risk rather than abandoning the longer term story.
Scan 31 resilient stocks with low risk scores to find other businesses, alongside Packaging Corporation of America, where operational risk controls and balance sheet strength are front and center.
After a 4.21% pullback and with Packaging Corporation of America trading below both analyst targets and intrinsic value estimates, is the recent wobble simply noise, or does it indicate a genuine gap between market price and fair worth?
Most Popular Narrative: 12% Undervalued
Packaging Corporation of America last closed at $227.25, while the most followed narrative points to a fair value of $259.30. This suggests investors are weighing short term operational headlines against a richer long term earnings story built into that model.
The company is committing US$840 million to US$870 million of capital expenditure in 2026 and has invested roughly US$6.5 billion in mills and box plants since 2017. This positions its upgraded network to drive efficiency and potentially support net margins as these assets are further utilized.
See why 9 investors see Packaging Corporation of America as 12% undervalued.
Result: Fair Value of $259.30 (UNDERVALUED)
Still, the Packaging Corporation of America story can change quickly if corrugated demand softens or if higher recycled fiber and freight costs remain elevated.
Find out about the key risks to this Packaging Corporation of America narrative.
Another View: Packaging Corporation of America Through Earnings Multiples
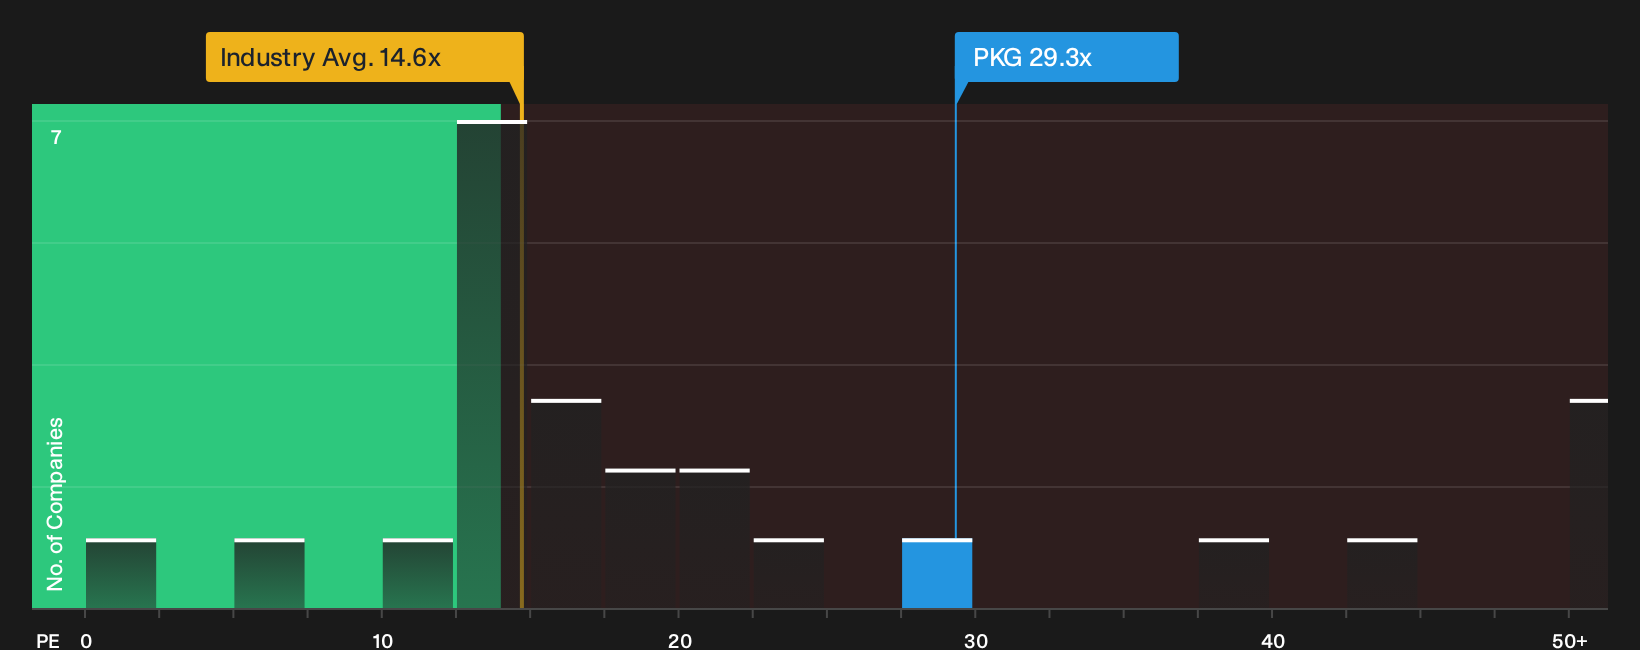
Packaging Corporation of America screens as undervalued on cash flow, yet its current P/E of 29.3x tells a different story. That valuation sits well above the global packaging group at 14.5x and above its own fair ratio of 26.3x, which points to less margin for error if sentiment cools.
For investors weighing these competing signals, the key question is whether the quality of earnings and future growth can justify paying more than both peers and the fair ratio, or if patience is safer while expectations reset. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals rarely stay mixed for long, so use this window to check the numbers yourself and pressure test both sides of the Packaging Corporation of America thesis. A helpful starting point is to weigh the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Packaging Corporation of America?
If Packaging Corporation of America has sharpened your thinking, do not stop there. Use this momentum to widen your watchlist with focused, high quality stock ideas.
- Target potential mispricings by scanning companies that look attractively priced on fundamentals through the 29 high quality undervalued stocks.
- Lock in income-focused opportunities by reviewing dependable payers highlighted in the 8 dividend fortresses.
- Prioritise resilience by filtering for financially robust businesses using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com