
Fastenal (FAST) Stock Looks Fully Valued Given Its Earnings Premium
Fastenal has turned a long holding period into a meaningful ride for shareholders, and the stock now trades near US$49.83 after a strong multi year stretch. With that kind of run on the chart, the live question is whether the current share price is still grounded in the company’s earnings power.
- Over the past 5 years, Fastenal has delivered a total return of 109.5%, which puts real pressure on the idea that its earnings can fully explain today’s valuation.
- The business leans on recurring demand from customers and a model that can support consistent profitability, which may support investor expectations for future earnings and cash generation.
- The analysts covering Fastenal have run their own numbers. See what analysts think Fastenal's shares could be worth.
The issue now is whether Fastenal’s current share price is justified by the earnings that investors are effectively paying for today.
If you are weighing Fastenal at US$49.83 and want a reference point for other quality focused ideas, it can help to compare it with 29 high quality undervalued stocks.
Is Fastenal Getting Expensive on Earnings?
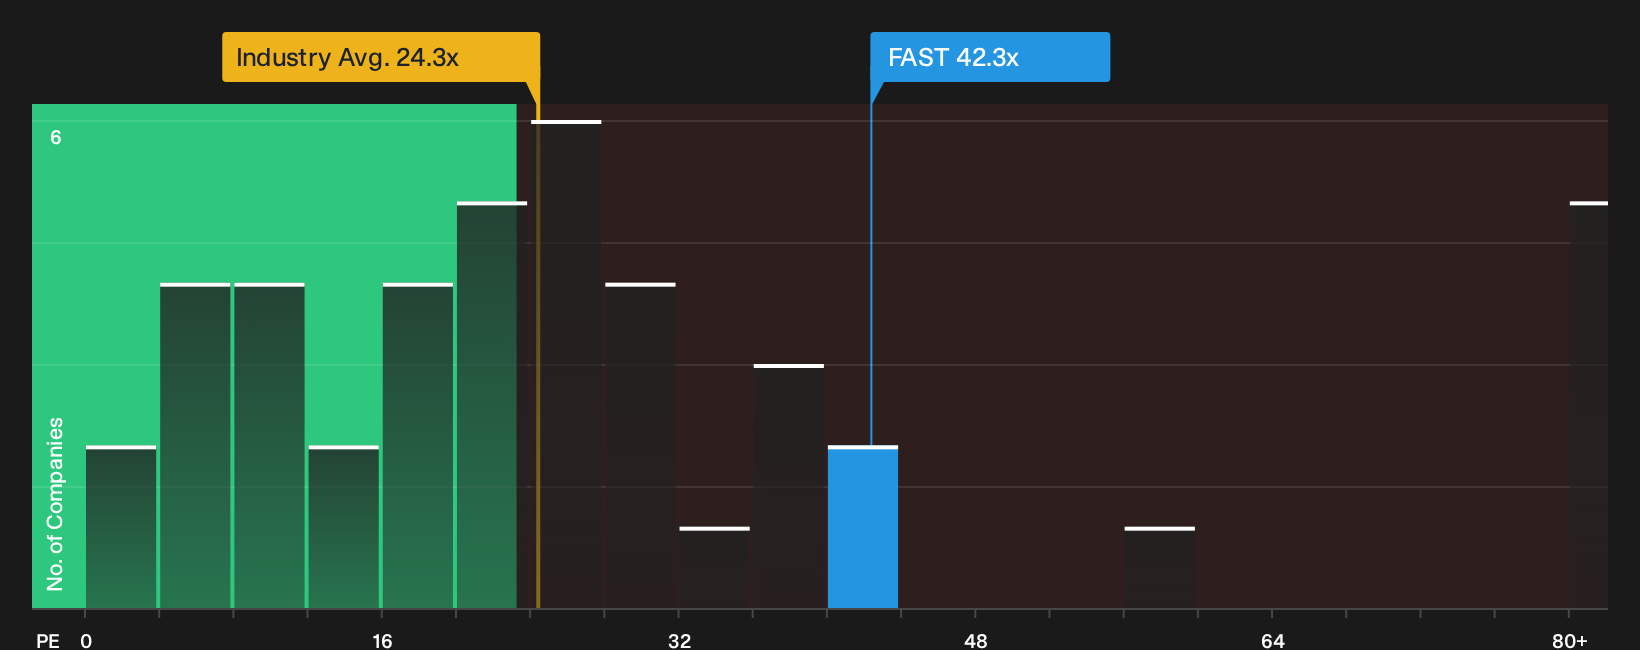
The P/E ratio fits Fastenal well because earnings remain a key lens for a mature, cash generative distributor. At roughly 42.3x earnings, the stock trades at a clear premium to the Trade Distributors industry average of about 24.3x and a peer group closer to 24.8x. That is a sizeable mark up for each dollar of profit you are buying into Fastenal compared with typical sector alternatives.
The fair value model, which blends the company’s growth assumptions, margins, size and risk profile into a tailored P/E yardstick, points to a lower multiple than the one the market is paying today. Fastenal therefore screens as overvalued on this earnings metric, with investors currently placing a richer price tag on the shares than the model suggests is warranted. The key question for you is whether the quality of the business and its cash generation justify paying so far above more conventional earnings benchmarks. Explore the numbers behind Fastenal's P/E valuation.
The Fastenal Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Fastenal pick up where the P/E debate leaves off by spelling out which future paths for growth, margins and earnings would make today’s valuation look rich or restrained. Instead of a single output from a model, Narratives lay out the underlying story that number relies on so you can see the world that has to unfold for Fastenal’s current price to make sense, and then watch over time whether that story is holding together.
Community views on Fastenal are split between those who see more upside left in the model and those who think most of the story is already in the quote.
Bull case: 16% undervalued
"Fastenal is using its shift toward large onsite and high spend customer sites, which now account for just over half of sales and grew revenue more than 26% year over year..."
Discover why this Narrative puts Fastenal at 16% undervalued.
Bear case: roughly fairly valued
"The current valuation, together with this narrative’s view that Fastenal is fairly valued and bullish, implies that the share price already reflects meaningful confidence in its high ROIC, elevated CapEx plans and expansion of digital and on site service revenue..."
Explore why this Narrative puts Fastenal at roughly fairly valued.
Fastenal’s valuation still leaves one crucial piece of the puzzle open
Price tells you what the market thinks of Fastenal, but the real steering wheel sits with the people in charge and how their incentives are wired to long term outcomes. See who runs Fastenal and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com