
How Recommerce Report Will Impact eBay (EBAY) Investors
- eBay released its 2026 Recommerce Report, showing secondhand shopping as a regular habit for many buyers, with 47% purchasing monthly and 89% planning to maintain or increase secondhand spending.
- The report highlights that 70% of global consumers view resale shopping as important for household budgets, which underscores how eBay’s recommerce focus connects value seeking buyers with small business sellers.
- The discussion then considers how eBay’s push into recommerce, highlighted by rising secondhand shopping frequency, could influence how some investors view the company.
eBay Investment Narrative Recap
To own eBay, you need to believe the marketplace can keep growing recommerce, keep enthusiast buyers engaged, and layer on higher margin services like advertising and payments without letting trust programs and shipping protections erode profitability. The latest recommerce data supports the demand side of that story. It signals that value driven secondhand buying is not a niche use case.
Near term, the key swing factor is whether focus categories and first party ads can offset the drag from higher transaction losses, Depop dilution, and any legal or compliance costs tied to past conduct. The recommerce report itself does not materially change those near term catalysts or the primary risk around protection economics and debt.
The most relevant update around this recommerce push is eBay’s work on AI powered search and discovery. Better search can help buyers actually find the secondhand items they want, which matters if recommerce habits keep deepening. More relevant results can also support higher ad effectiveness, since promoted listings live inside the same experience.
There is tension, though. Power users already flag that personalization and ads sometimes make precision searching harder. That is an operational execution risk. If enthusiast buyers or sellers feel search is less reliable, engagement and listing growth could slow, which would feed directly into GMV, ad revenue, and the core recommerce thesis investors are weighing today.
eBay's current analyst narrative points to revenues of US$14.8b and earnings of US$2.7b by 2029. That profile sits on top of assumed yearly top line growth of 7.1% and an earnings increase of about US$0.5b from US$2.2b today.
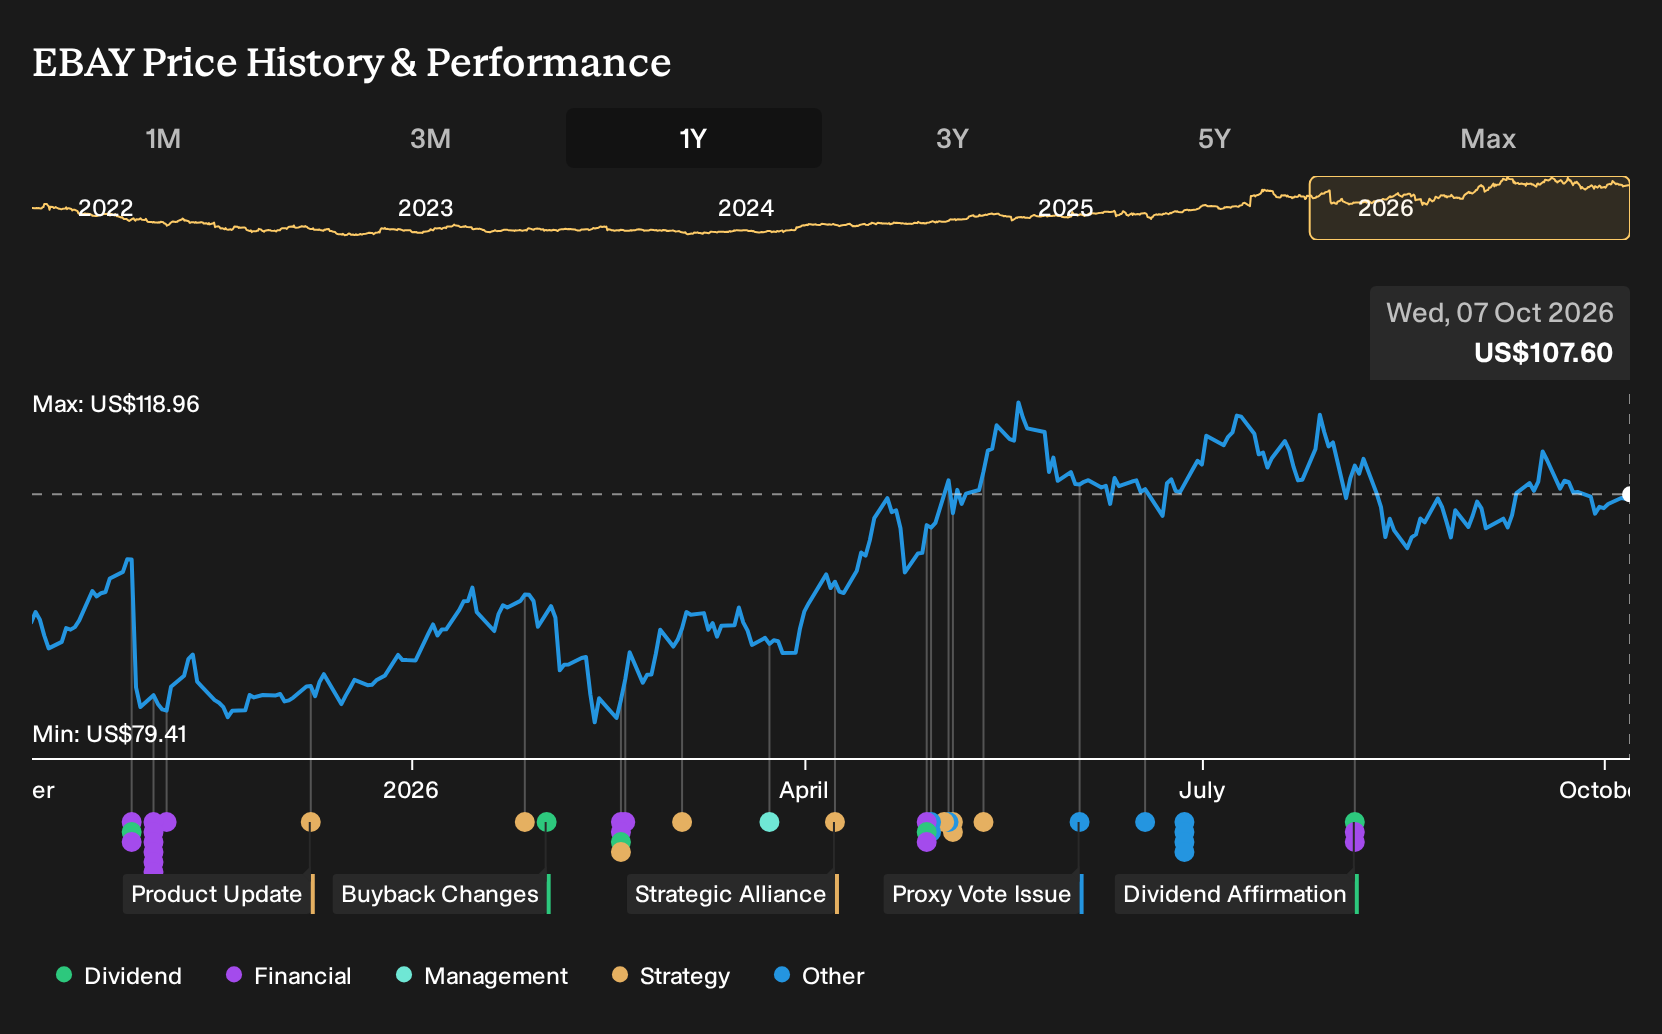
Discover how eBay's fair value indicates an 8% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view puts eBay’s margin pressure front and center. Those more cautious analysts were pencilling in revenue of about US$14.0b and earnings of roughly US$2.3b by 2029, with margins easing to 16.5%. This can be read as a much tougher story, where today’s recommerce momentum might eventually need a reset. This latest report could nudge those expectations in either direction, so it helps to compare both the upbeat and the more restrained forecasts before you decide how convincing each one feels.
Explore 4 other eBay fair value estimates, including one that suggests it could be worth just $104.94.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your eBay research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for eBay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate eBay's overall financial health at a glance.
Looking For More Ideas Beyond eBay?
Once you have a view on eBay, it can help to line it up against other opportunities that match your style. The Simply Wall St Screener lets you filter the market by balance sheet strength, income focus, or potential mispricing, so you can compare eBay with peers that fit your own risk and return preferences.
- For investors who care most about resilient finances and staying power, start with this list of solid balance sheet and fundamentals (25 results) to see which businesses keep their foundations tight.
- If income is your priority and you want cash coming back to you regularly, take a look at companies in the 8 dividend fortresses that focus on higher yields.
- For those hunting for opportunities that the market may not be fully focused on yet, scan the 20 high quality undiscovered gems and see which quieter stories you want to research next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com