
Will $2b Axiom Investment Change Flex (FLEX) Stock Narrative
- Flex entered into a new undrawn US$3.3b 364 day term loan facility that is tied to its credit ratings, with covenants on leverage, interest coverage and other balance sheet actions.
- Axiom, the data center spin off, secured a US$2b preferred equity investment at a US$37.5b valuation, which highlights investor focus on Flex’s Cloud and Power Infrastructure economics.
- We will look at how Flex’s investment narrative around AI infrastructure shifts as outside investors price Axiom near the parent’s value.
Scan beyond Flex and compare this AI infrastructure story with 92 AI infrastructure stocks that are also drawing capital into power hungry data center build outs.
Flex Investment Narrative Recap
To own Flex, you need to believe its heavy tilt toward AI infrastructure, power systems and higher value manufacturing will keep translating into stronger earnings and better use of capital. The undrawn US$3.3b term loan sits in the background as optional firepower, rather than a change to day to day operations right now.
The near term swing factor is whether Cloud and Power Infrastructure and EPC Power can keep feeding demand for AI data center and grid projects while spin off work does not dilute margins or distract execution. The biggest risk is stacking more leverage and capital commitments onto a business already flagged as having a high debt load.
The new 364 day facility links directly into the EPC Power acquisition, which sits at the center of Flex’s power and data center pitch. Having a committed, ratings linked loan gives management a defined funding path for that US$4.4b deal and helps replace a portion of the existing US$4.4b bridge commitments.
For you as a shareholder, that matters because EPC Power is tied to NVIDIA’s DSX architecture and is expected to add roughly US$800m of revenue in 2026, with management commentary pointing to material growth in 2027. The loan increases financial flexibility around this build out, while also tightening leverage and interest coverage covenants that could become a constraint if AI infrastructure demand or EPC execution disappoint.
Flex's narrative projects US$56.5b revenue and US$4.2b earnings by 2029. This rests on analysts modeling 24.5% yearly revenue growth and an earnings increase of about US$3.2b from US$973.0m today.
Uncover how Flex's fair value indicates a 34% potential upside to its current price that could narrow quickly if Flex continues executing on its AI build out.
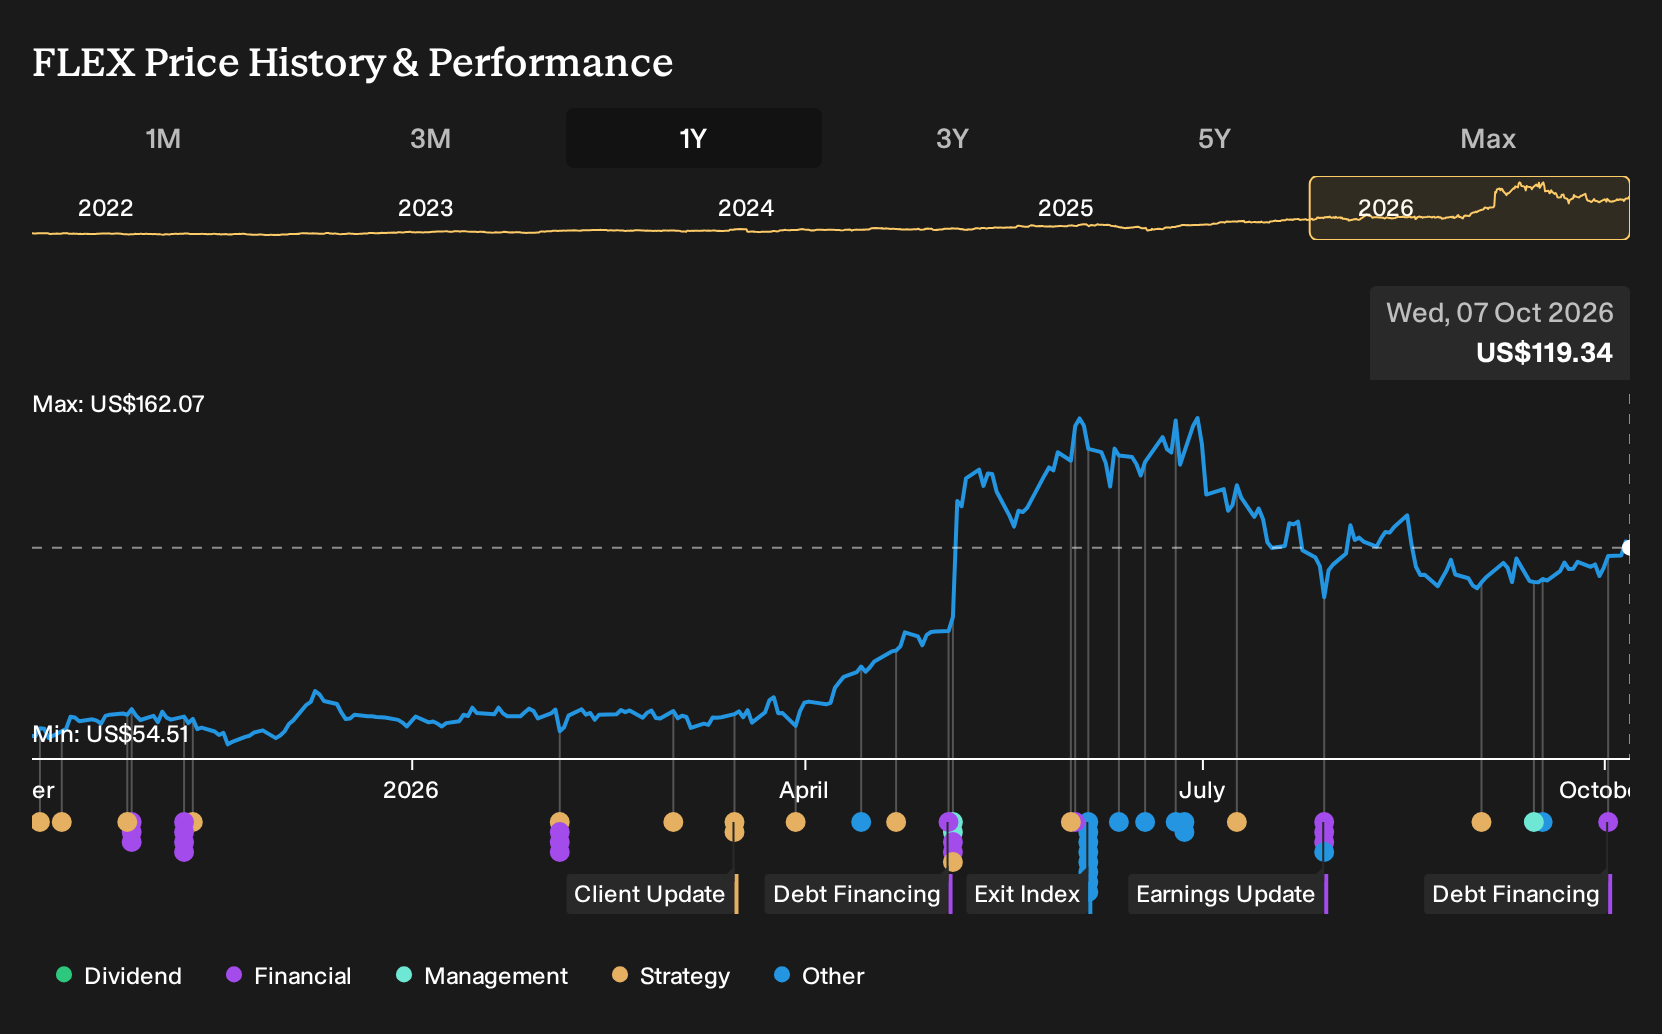
Exploring Other Perspectives
The lowest analysts focus on Flex’s free cash flow risk rather than AI upside. They went into this news assuming revenue would reach about US$53.8b and earnings about US$3.6b by 2029, which is meaningfully below consensus. That more cautious story could shift, so consider both possibilities before you form your own view.
Explore 5 other Flex fair value estimates, including one that suggests it could be worth just $130.26.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Flex research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Flex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flex's overall financial health at a glance.
Looking For More Investment Ideas Beyond Flex?
If the Flex story has sharpened your interest in AI infrastructure and cash flow quality, it can help to widen the lens and compare it with other companies that fit different risk and return profiles. The Simply Wall St Screener offers several targeted ways to do that, so you can line up Flex alongside peers that match your own goals.
- For investors hunting for stability with meaningful income, consider companies in our list of resilient payers by checking out 8 dividend fortresses.
- If capital preservation sits higher on your priority list than aggressive upside, review businesses filtered for financial resilience and lower risk through 31 resilient stocks with low risk scores.
- Readers who want to focus on quality first can scan for financially sound operators with strong fundamentals using the broader list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com