
Borregaard (OB:BRG) Refinanced Its Debt, But Is The Stock Still Undervalued?
Borregaard (OB:BRG) just replaced its existing revolving credit lines with NOK 1,500 million in new multicurrency facilities that are tied directly to specific sustainability metrics, including emissions, workplace safety, and river pollution.
Recent trading tells a different story to the refinancing headlines. At a NOK150.6 share price, Borregaard’s stock has fallen 23.4% on a year to date share price basis, while the 1 year total shareholder return is down 18.69%. This suggests recent momentum has been weak despite roughly flat performance over three years.
Scan 182 high quality undervalued stocks, where, like Borregaard, the market reaction appears out of sync with balance sheet strength, earnings trends, or recent funding moves tied to sustainability goals.
Borregaard has fresh sustainability linked credit and a weak share chart. Does that mix still offer a skew that favours new buyers, or has the risk side of the equation started to dominate the valuation story?
Most Popular Narrative: 13% Undervalued
Borregaard’s most followed narrative points to a fair value of NOK174 per share, compared with the latest NOK150.6 close. This sets up a valuation gap anchored in specific growth and margin expectations rather than vague optimism.
The analysts have a consensus price target of NOK174.0 for Borregaard based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be NOK8.7 billion, earnings will come to NOK1.4 billion, and it would be trading on a PE ratio of 15.7x, assuming you use a discount rate of 7.0%.
See why 16 investors see Borregaard as 13% undervalued.
Result: Fair Value of NOK174 (UNDERVALUED)
Still, two pressure points could easily upset that 13% undervalued story for Borregaard: higher wood and logistics costs, or weaker demand from agriculture-linked customers.
Find out about the key risks to this Borregaard narrative.
Another View: Borregaard Through The P/E Lens
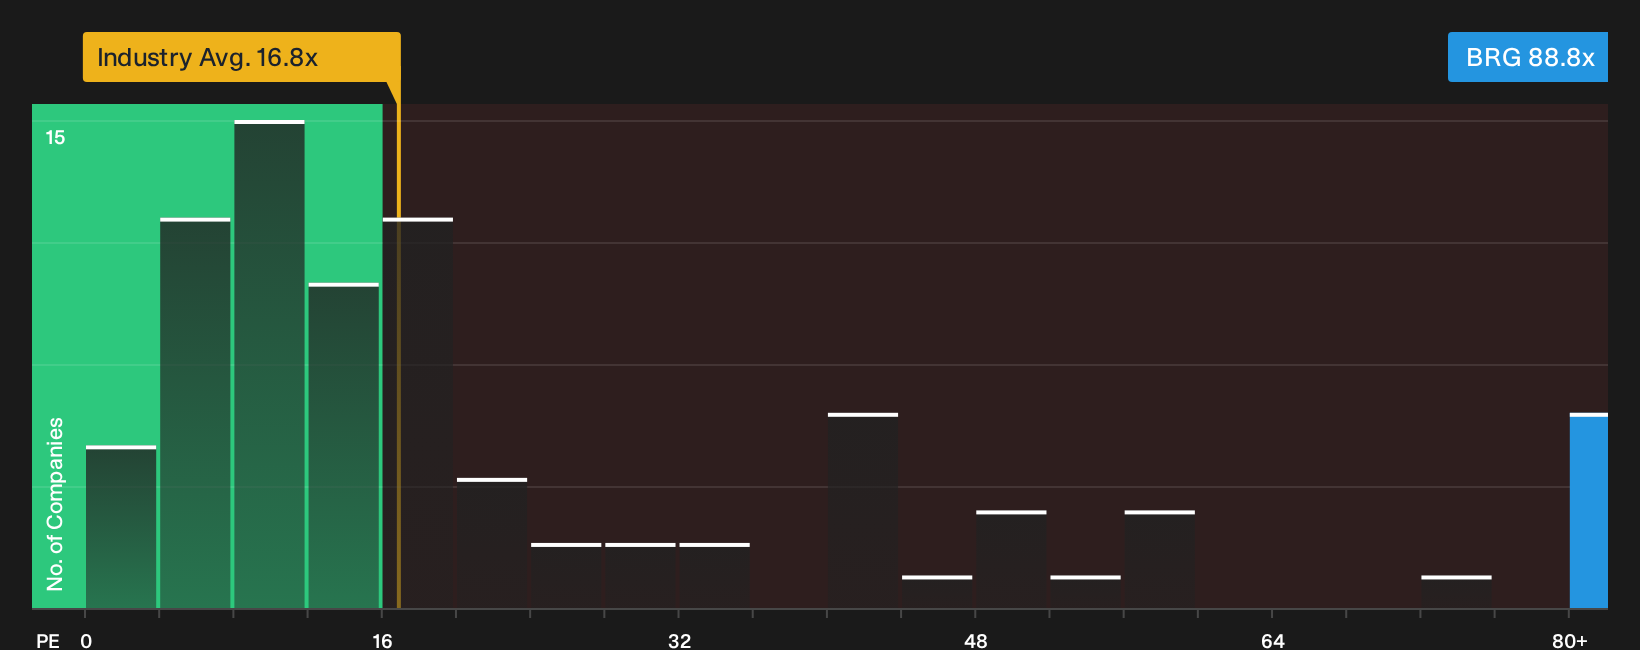
Look at Borregaard through simple earnings multiples and the picture changes. The stock trades on a P/E of 88.8x, which is far higher than both the peer average of 23.4x and the European Chemicals sector on 16.8x. It also sits above a fair ratio of 45x, so investors are currently paying a rich price for each krone of earnings. This raises the question of how much short term disappointment the share price can absorb before that gap closes.
To see how this earnings based view fits with the rest of the valuation work on Borregaard, including how the numbers line up against quality and growth, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Borregaard so far. If that leaves you on the fence, move quickly from headlines to hard numbers and weigh both sides of the story with the 2 key rewards and 1 important warning sign.
Looking for more Borregaard sized investment ideas?
Do not stop with Borregaard. Use the Simply Wall Street Screener to quickly surface fresh ideas that match your risk appetite, income needs, and time horizon.
- Target resilient cash generators by scanning the list of solid balance sheet and fundamentals (206 results) that combines financial strength with consistent fundamentals.
- Hunt for mispriced opportunities through the 619 high quality undiscovered gems where strong underlying metrics have yet to attract wider attention.
- Build a smoother ride across market cycles by checking the 225 resilient stocks with low risk scores that filters for companies with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com