
Wolfspeed (WOLF) Stock Could Be Fully Priced After $1.5B Loan Commitment
Wolfspeed has rallied hard in 2026, and with the stock closing at US$31.37, the key issue for investors is whether that share price still lines up with the revenue the business is generating. With expectations riding on its silicon carbide technology, the open question is how much sales the current valuation is really asking you to underwrite.
- The stock is up 65.7% year to date, which puts more pressure on the price to be supported by the company’s sales base rather than just momentum in the chart.
- A conditional US$1.5b loan commitment from the U.S. Department of War can support Wolfspeed’s push into larger scale silicon carbide and gallium nitride manufacturing, which may reshape how you think about future revenue capacity and the investment needed to get there.
- Your read on Wolfspeed is one view; the desks covering it have another. See what analysts think Wolfspeed's shares could be worth.
The issue now is whether Wolfspeed’s current market value is justified by its sales when you set it against the Fair Ratio benchmark.
If you want to test the same sales based valuation question across a wider group of chipmakers, scan through 92 AI infrastructure stocks.
Has Wolfspeed Run Too Far on Sales?
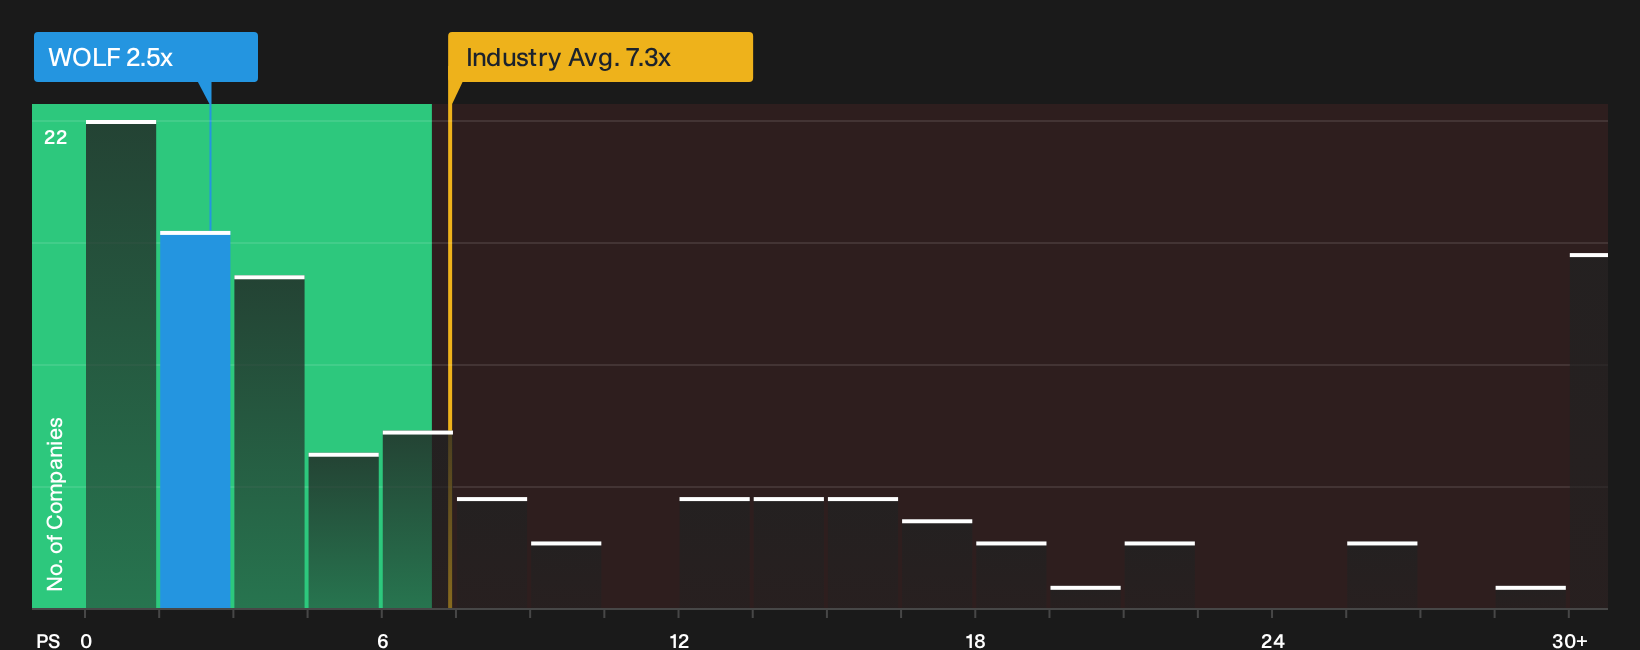
P/S is the cleaner yardstick for Wolfspeed because earnings and free cash flow are deeply negative, so revenue is the only stable anchor for the valuation right now. On that lens, the stock trades on a P/S of 2.5x, which is far below the semiconductor industry average of 7.3x and also under the peer group at 8.3x. Despite the recent US$1.5b loan commitment from the Department of War lifting expectations around capacity and product breadth, the share price still reflects a much lower sales multiple than many chipmakers with similar end markets.
The Fair Ratio framework, which tries to adjust the P/S for Wolfspeed’s growth profile, margins, size and risk, points to a much lower multiple than where the stock currently changes hands. Because the gap is very wide, the model is effectively flagging that the market is putting a rich price on each dollar of current revenue relative to what those fundamentals might justify. That tension between a discounted headline P/S versus the Fair Ratio signal is what you need to weigh. Explore the numbers behind Wolfspeed's P/S valuation.
The Wolfspeed Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take Wolfspeed's valuation puzzle and turn it into a set of clear future paths that link today's share price to specific outcomes for growth, profitability and earnings. Each narrative sits on the Community page and shows which combination of future sales, margins and cash generation would need to play out for the stock to justify a meaningfully higher or lower level than now. Where a single ratio or pricing model gives you one number, the narratives unpack the future that number relies on so you can watch how reality lines up with it over time.
One of the top community narratives on Wolfspeed: 14% overvalued
"Operational focus on producing the same revenue with less capacity consumed and on improving factory utilization, combined with a refreshed leadership team…"
Discover why this Narrative puts Wolfspeed at 14% overvalued.
For Wolfspeed, price is only one question you need to answer
Valuation tells you what the market is paying today, but Wolfspeed also has specific business risks and pressure points that our checks have picked up and that deserve your attention. Take a closer look at 5 warning signs (4 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com