
Learn Why The Bull Case For IMAX (IMAX) Could Change Following Revenue Growth
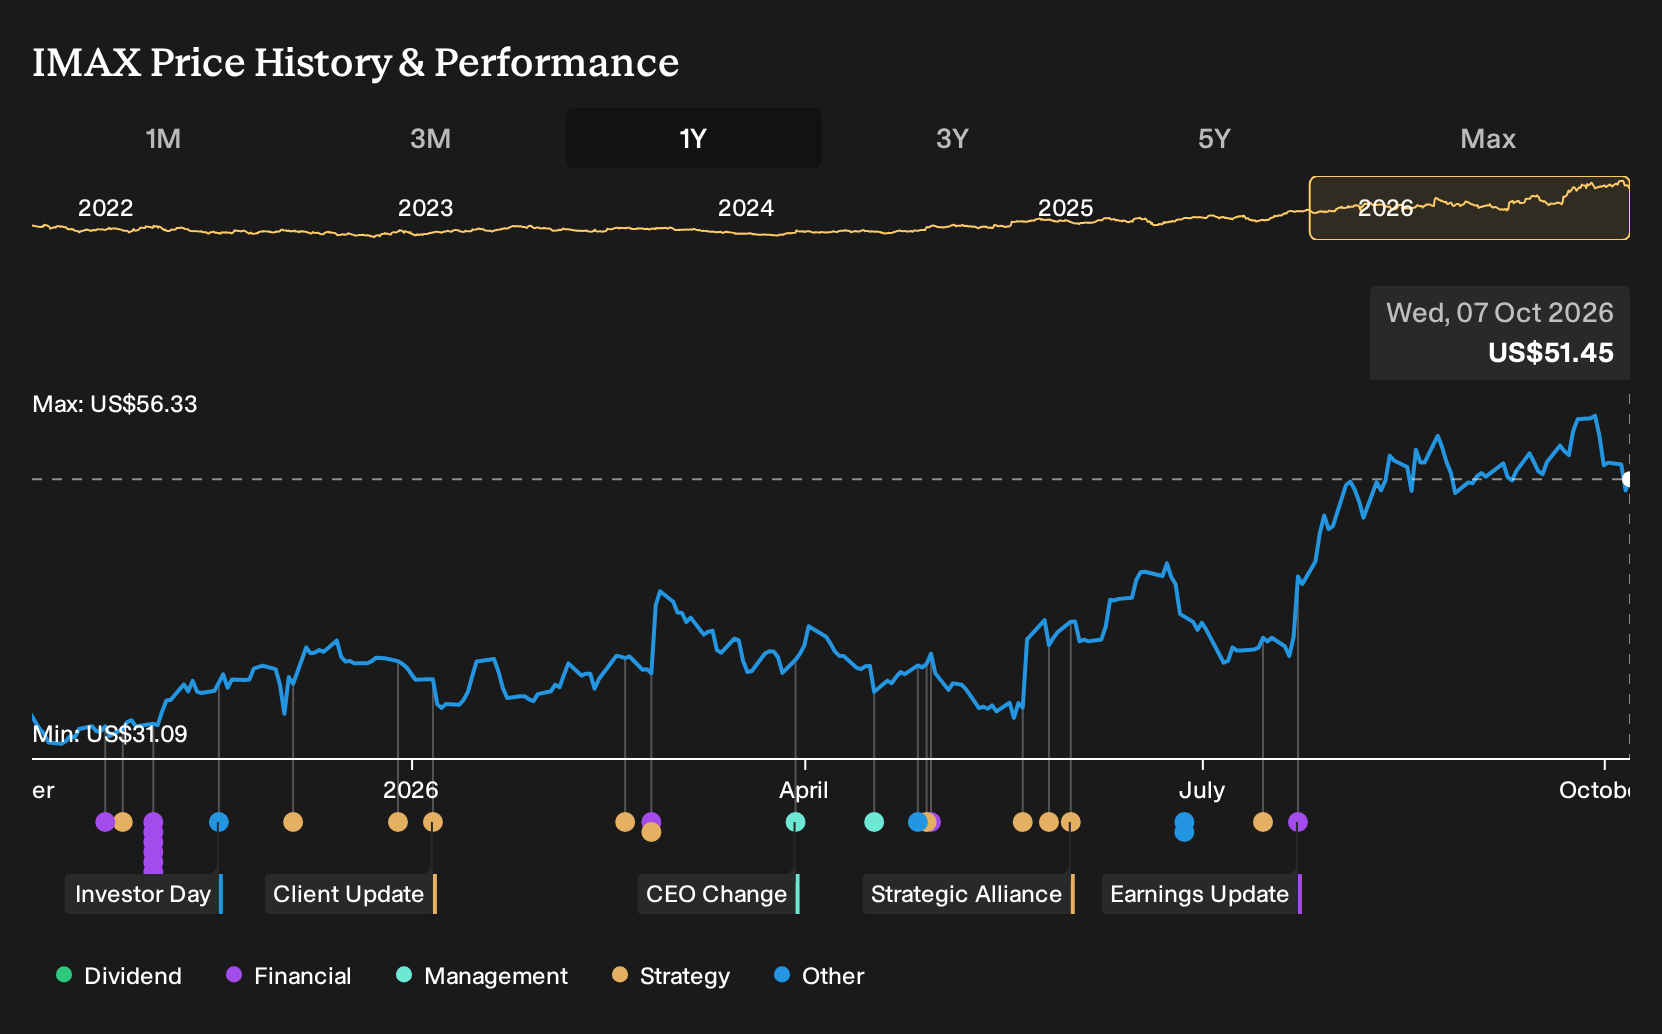
- IMAX reported a 12% year over year revenue gain in its latest quarter, supported by strong IMAX box office for The Odyssey and continued interest from large institutional investors.
- The combination of higher revenue tied to a premium release like The Odyssey and visible institutional support highlights how IMAX's format can translate hit films into stronger perceived business momentum.
- We will now explore how IMAX's positive revenue surprise from The Odyssey could influence the existing investment narrative around margin potential.
Scan for other cinema and premium-format stocks showing similar box office and institutional momentum by zeroing in on our hand picked 20 high quality undiscovered gems that echo the IMAX story.
IMAX Investment Narrative Recap
For you to stay interested in IMAX, you need to believe premium large format is a habit, not a fad. The recent 12% year over year revenue gain tied to The Odyssey supports the idea that blockbuster content can still pull people off the couch and into high value auditoriums, which feeds both system sales and recurring service income.
The key near term swing factor remains how well IMAX converts that momentum into more system installs and a healthier backlog while the Skydance led studio reshuffle plays out. The biggest risk is simple. If tentpole volume or cinema attendance softens, box office driven fees and the installation pipeline could both feel pressure.
The Skydance merger that combines Paramount and Warner Bros Discovery matters directly to this story. A larger studio entity with a bias toward global theatrical releases gives IMAX clearer visibility on a flow of large format friendly titles like The Odyssey, which is what supported the latest revenue surprise.
That same consolidation cuts both ways for you as an investor. Reliance on a smaller group of major content partners increases concentration risk if release schedules change or a year has fewer true event films. Execution for IMAX now hinges on using this window of strong box office and institutional support to deepen partnerships, expand its screen base and keep content diversification, from local language films to live events, moving forward.
IMAX's narrative projects revenues of US$509.0 million and earnings of US$95.8 million by 2029. This is based on an assumption that revenue increases by 6.9% per year and earnings increase by about US$54.9 million from US$40.9 million today.
Discover how IMAX's fair value indicates a 10% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
Some of the lowest IMAX analysts focus less on box office upside and more on the risk that at home formats steadily chip away at premium theatrical demand. Before this news, they were working off roughly US$513.0 million of 2029 revenue and US$105.0 million of earnings, so you may see those views shift as fresh data lands.
Explore 2 other IMAX fair value estimates, including one that suggests it could be worth just $56.68.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your IMAX research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for IMAX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IMAX's overall financial health at a glance.
Looking For More Ideas Beyond IMAX?
If the IMAX story has sharpened how you think about box office driven businesses, it can help to set it alongside other opportunities that score well on quality, value, or resilience using the Simply Wall St Screener.
- For investors hunting for mispriced opportunities with solid fundamentals, start with a focused group of 29 high quality undervalued stocks that may offer a better balance of quality and price.
- If capital protection sits higher on your priority list than shooting for maximum upside, filter for 31 resilient stocks with low risk scores that show steadier profiles across debt, earnings and volatility.
- When you care most about strength in the balance sheet and core metrics, target our list of solid balance sheet and fundamentals (25 results) to see which businesses pair financial resilience with cleaner fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com