
Why WEBTOON Entertainment Bears Were Right Before The Drop
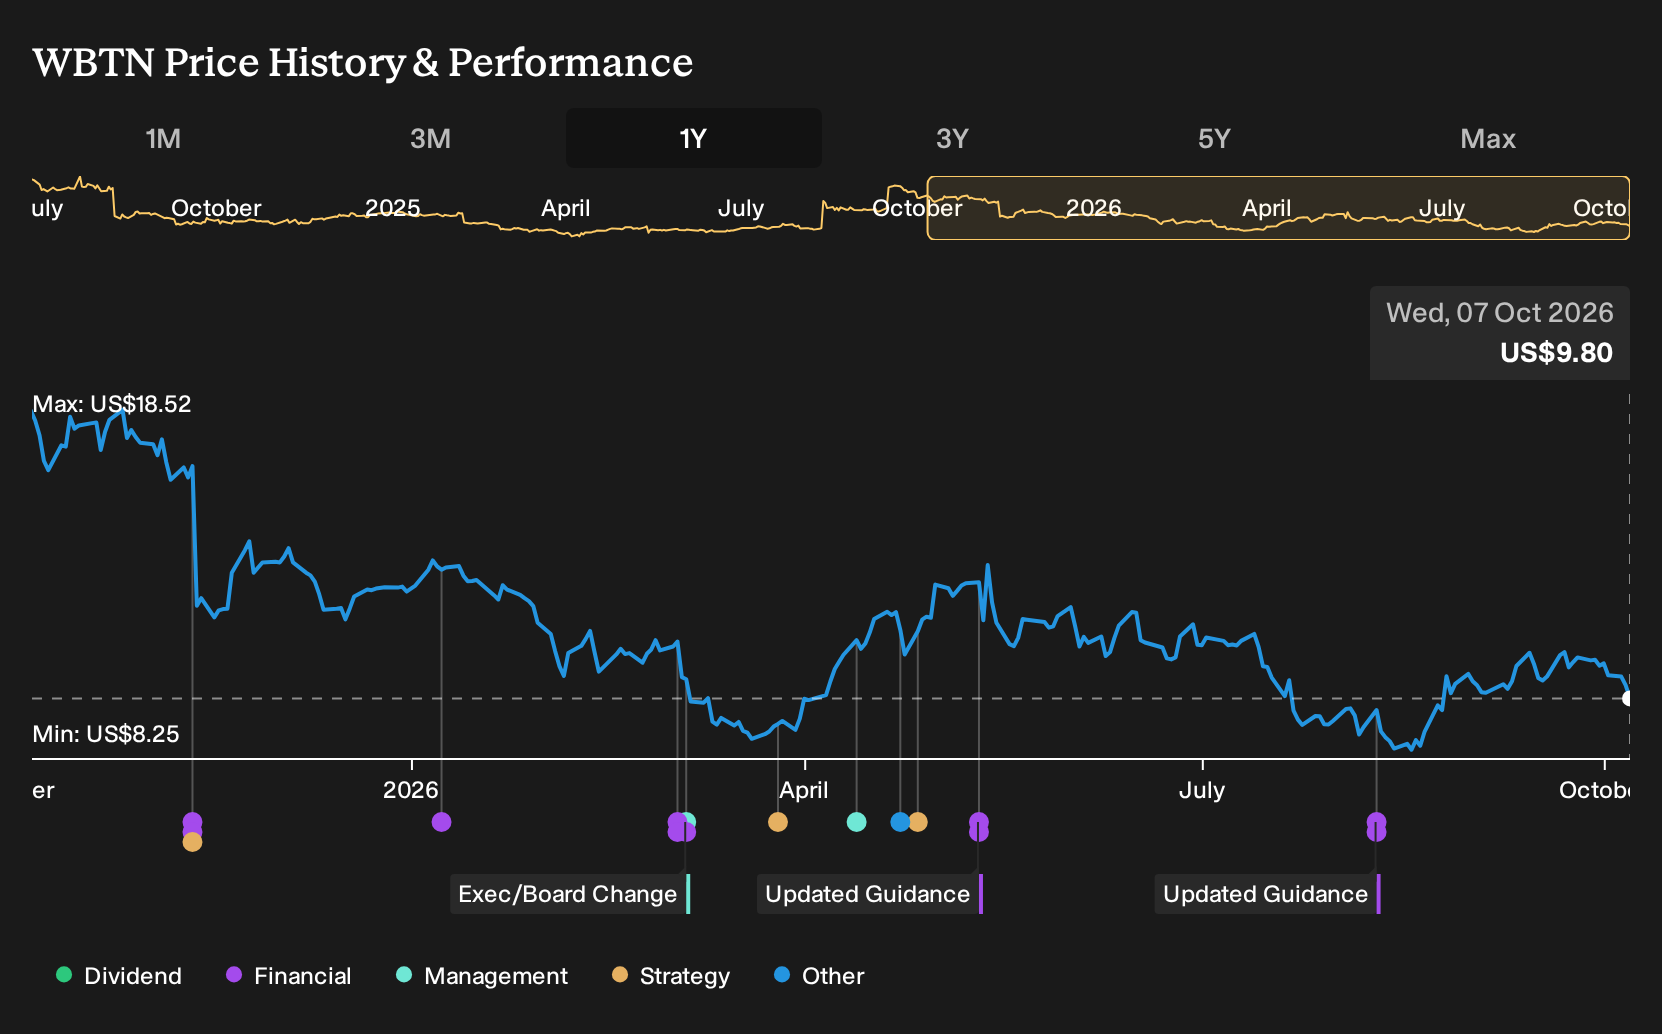
WEBTOON Entertainment’s latest quarterly report combined a revenue dip with an earnings beat and a softer outlook for the months ahead, which helped focus attention on what owning the stock has actually delivered. For WEBTOON Entertainment shareholders, the loss over the past year was 44.8%, including dividends. If you had chosen to buy on 7 October 2025, how should that setback now reshape expectations for its Disney tie up and broader transmedia push?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind WEBTOON Entertainment. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On WEBTOON Entertainment
The shares cost US$18.2 at the start of the period, and anyone looking at WEBTOON Entertainment then had to choose between two very different Narratives that both sounded reasonable.
The bullish view put Fair Value at US$22.25. That story leaned on annual revenue growth of 17.3% and an improvement in profit margins to 5.4%, supported by confidence in the Disney partnership and transmedia push.
The cautious Narrative set Fair Value at US$17. It still assumed 14.0% yearly revenue growth but focused on risks such as regulatory bans and the need for a future P/E of 86.0x to justify the expectations.
What The Evidence Around WEBTOON Entertainment Actually Showed
WEBTOON Entertainment’s Q2 2026 numbers challenged the bullish profitability story. Revenue slipped from US$348.3m to US$338.5m and the business still reported a loss. Net margin moved further into the red, from a loss of 1.3% to a loss of 4.5%, so the earlier expectation of near term margin lift stayed unproven. Overall, the evidence leaned toward the cautious case.
The key assumption here was that earnings quality would improve more quickly than headline sales. For another stock built on a similar premise, it may be useful to watch whether losses narrow and net margin moves toward the level reflected in any optimistic P/E multiple.
What You Would Be Paying For In WEBTOON Entertainment Today
WEBTOON Entertainment now trades at US$9.8, with this selected Narrative arguing that Fair Value sits above that level based on longer term earnings potential rather than recent share price moves.
The bullish case leans on Disney-backed transmedia reach and a mobile-first creator platform. For the fall to look like an opportunity rather than a warning, a buyer would need confidence that these factors genuinely support sustained margin expansion and user monetization.
"Unique mobile-first, creator-driven ecosystem and cross-media IP adaptation provide structural advantages for monetization and long-term margin expansion over traditional publishers. Heightened competition, rising costs, and regulatory pressures threaten WEBTOON Entertainment's global expansion, user engagement, and margin growth amid digital fatigue and content saturation."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Which Company Could Surprise You Next?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 33% below our estimate - targets a large resource base to extend the life of mining projects.
- Company 2 - 35% below our estimate - leverages major project backlog linked to data-led and industrial construction needs.
- Company 3 - 24% below our estimate - sells advanced AI-focused chips and tools into data-intensive computing environments.
That is three of the list. See the full list of 25 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com