
Fabrinet (FN) Rallies As Capacity Expansion Narrative Puts Valuation Back In Focus
Fabrinet (FN) has drawn fresh attention after recent share price moves, with the stock closing at $497.99. Investors are weighing that level against the company’s reported revenue of $4.64b and net income of $473.03m.
Recent trading has been strong, with Fabrinet’s 1-month share price return of 22.24% and 7-day gain of 17.38% pointing to building momentum. At the same time, a 1-year total shareholder return of 29.88% and 5-year total shareholder return of 396.70% show a longer track record of value creation being priced into the current move.
Scan other high-momentum optical and AI infrastructure manufacturers by sorting through the hand-picked 91 AI infrastructure stocks alongside Fabrinet’s recent surge.
Fabrinet now trades almost US$240 below the average analyst target and roughly 23% above an implied intrinsic estimate. The gap is clear. Which reference point anchors fair value for you?
Most Popular Narrative: 32% Undervalued
Fabrinet’s most followed narrative points to a fair value of $734.11 against the latest close at $497.99, so the current market price is being weighed against higher implied earnings power and capacity plans.
Planned capacity expansion from roughly 5.8b of existing capacity to about 9.8b by early calendar Q1 2027 and ultimately to 12.5b to 14b, supported by Building 10 and additional Thai and US sites, gives Fabrinet room to take on new programs and potentially scale revenue and operating income without a proportionate rise in fixed costs.
See why 48 investors see Fabrinet as 32% undervalued.
Result: Fair Value of $734.11 (UNDERVALUED)
Still, Fabrinet’s tight reliance on a handful of hyperscale customers and ongoing component supply constraints could quickly weaken the bullish fair value story.
Find out about the key risks to this Fabrinet narrative.
Another View: Fabrinet Through A Cash Flow Lens
The earlier narrative leans heavily on earnings power and analyst targets to argue Fabrinet looks undervalued. A different tool, the SWS DCF model, paints a cooler picture. On that framework, FN at $497.99 sits above an estimated future cash flow value of $406.24, which frames the stock as overvalued on cash generation. Which signal do you trust more when cash and earnings tell different stories?
For readers who want to see how that cash focused estimate was built and stress test the inputs themselves, the full SWS DCF model run on Fabrinet is a useful cross check for the headline multiples and analyst targets, starting with Look into how the SWS DCF model arrives at its fair value..
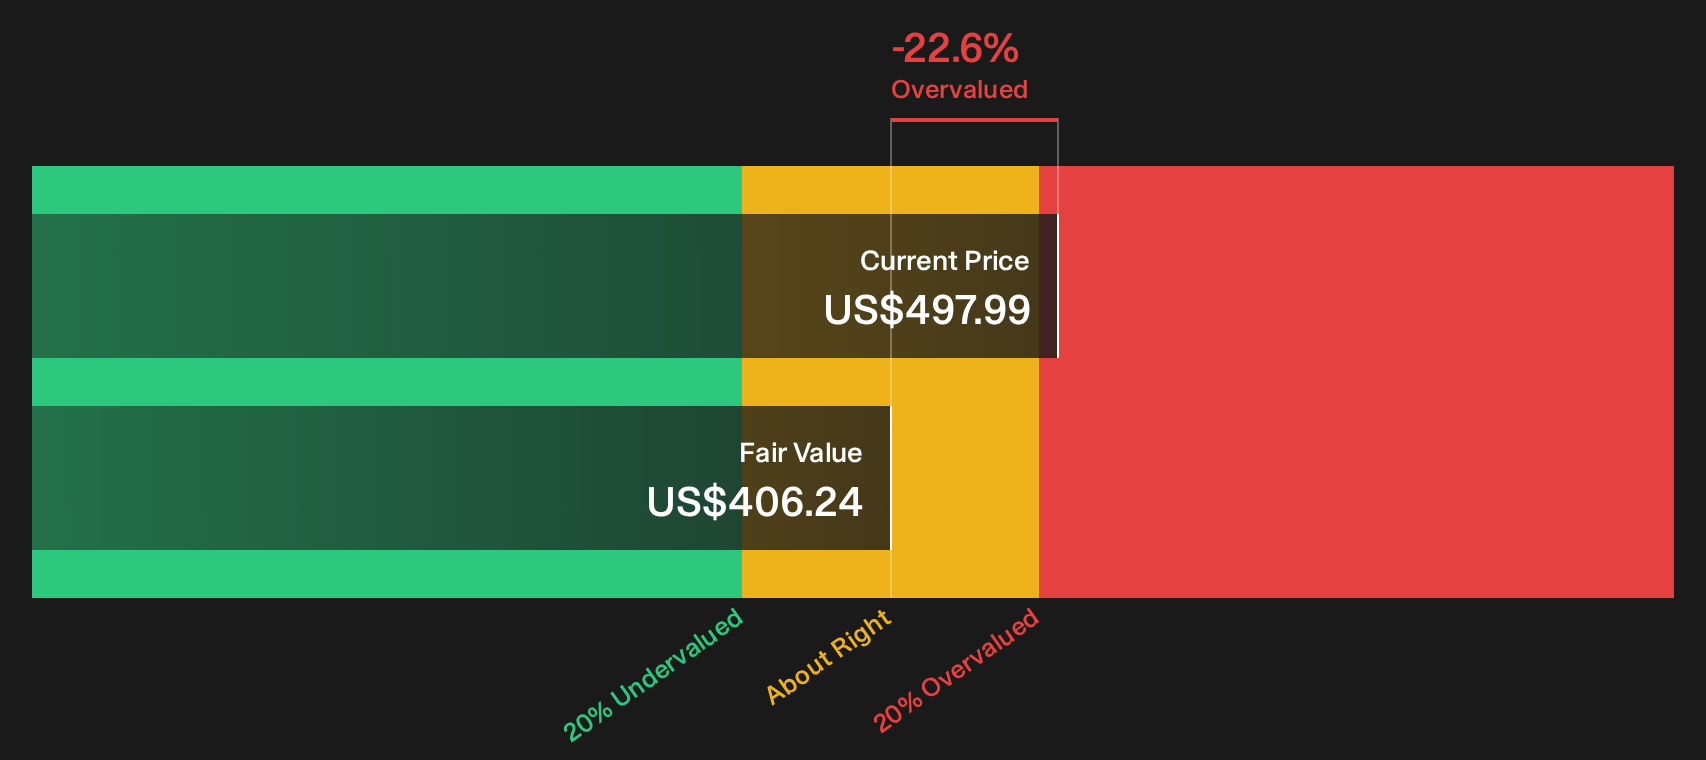
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fabrinet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Fabrinet so far, or a clear setup taking shape in your mind already? Act while the data is fresh, weigh both the concerns and the upside, then pressure test your view against the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Fabrinet?
Do not stop your research at Fabrinet alone. Let the same disciplined approach guide you toward other stocks that fit clear, focused criteria.
- Hunt for potential mispricing by scanning the 29 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
- Strengthen the income side of your portfolio by reviewing the 8 dividend fortresses that target higher yields with supporting financials.
- Prioritise resilience by filtering through the 31 resilient stocks with low risk scores that emphasise durable balance sheets and steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com