
Tryg (CPSE:TRYG) Could Be 13% Undervalued On Profitability Plans
Pre-close analyst calls on Tryg (CPSE:TRYG) are drawing attention to the insurer ahead of the market close, giving investors a fresh look at recent share performance and business fundamentals.
Recent trading tells a mixed story for Tryg. The DKK143.7 share price comes after a 7 day share price return of 1.77%. However, the 30 day share price return is down 6.51% and the year to date share price return has declined 12.96%, while the 3 year total shareholder return of 28.37% points to stronger longer term compounding.
Scan how Tryg stacks up against other insurers by running through our hand picked 226 resilient stocks with low risk scores that focuses on resilient balance sheets and steadier return profiles.
Tryg now trades at a double discount, both to analyst targets and to one estimate of fair value, after a weak year to date share price. Is that caution deserved once you line it up against the fundamentals?
Most Popular Narrative: 13% Undervalued
On the latest numbers, the most followed narrative puts Tryg's fair value at DKK166.04 against a last close of DKK143.70. This frames a valuation gap that rests heavily on execution in earnings and margin plans.
Tryg is implementing profitability initiatives, particularly in their Private and Motor segments, which are expected to improve their underlying claims ratio over time. This can enhance earnings and profitability.
See why 23 investors see Tryg as 13% undervalued.
Result: Fair Value of DKK166.04 (UNDERVALUED)
Still, the narrative around Tryg can change quickly if inflation keeps pressure on claims costs, or if tougher regulation crimps pricing power and earnings quality.
Find out about the key risks to this Tryg narrative.
Another View on Tryg’s Valuation
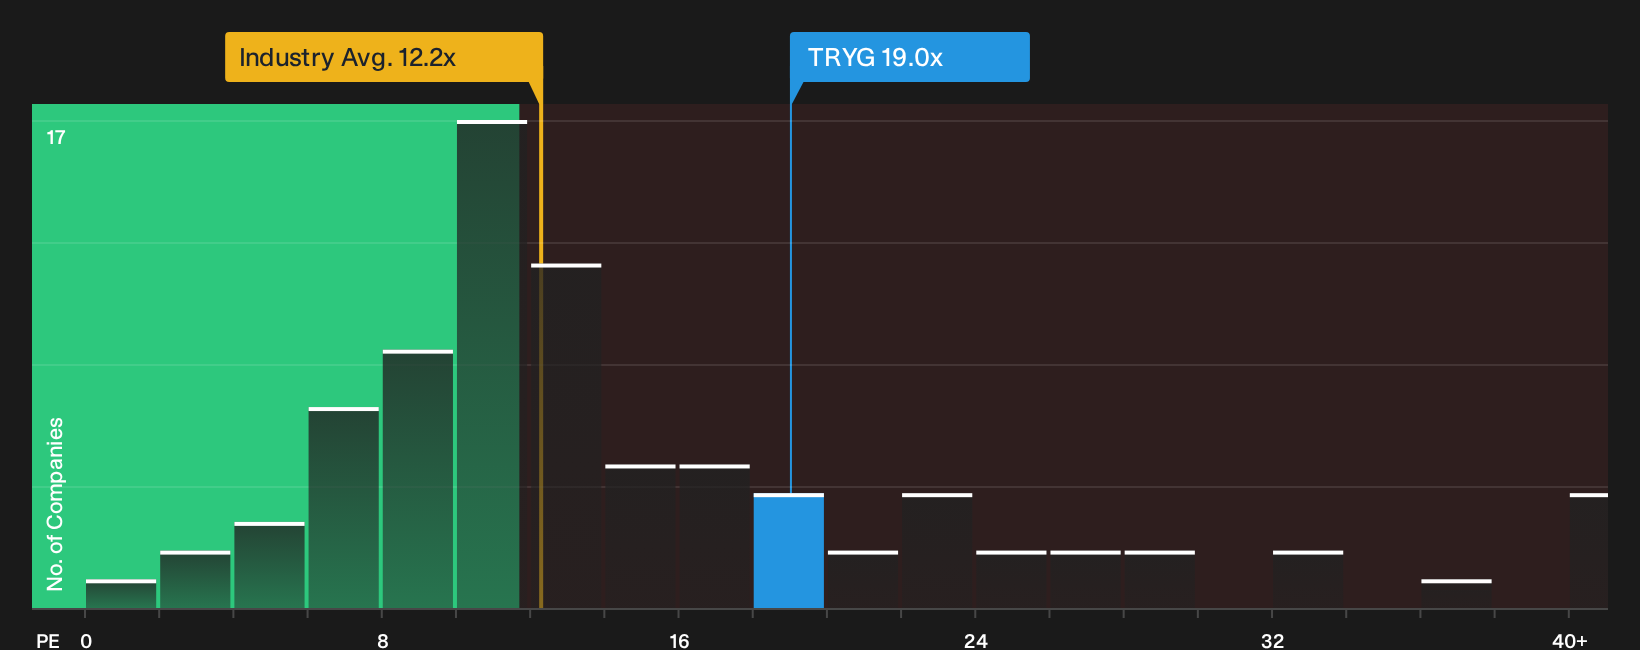
The story looks different once you shift from fair value estimates to plain P/E math. Tryg trades on roughly 19x earnings, which is higher than the European insurance sector at 12.3x and above peer averages around 14.8x. Yet the fair ratio sits at 22.6x, implying the current multiple is below where the market could migrate over time. Is that a safety cushion or a sign investors are already paying up for quality?
For a closer look at how this P/E gap might affect potential upside or downside, especially if sentiment toward insurers changes again, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Views on Tryg are clearly split, so take a moment to review the numbers yourself, weigh the trade off between potential upside and downside, and then check the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tryg?
If you only focus on Tryg, you could miss other opportunities that fit your goals, so put a few minutes into comparing ideas across the wider market.
- Target potential mispricing by scanning companies that screen as attractively valued using the 186 high quality undervalued stocks.
- Build a steadier income stream by reviewing dividend payers that clear our quality checks through the 225 dividend fortresses.
- Strengthen your watchlist with businesses that pair robust finances with cleaner balance sheets using the list of solid balance sheet and fundamentals (207 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com