
How Investors May Respond To Church & Dwight Stock Slow Sales Growth
- Church & Dwight is contending with slow organic sales and modest earnings per share growth, which points to softer demand for its core products and a relatively rich forward P/E multiple that already reflects much of the good news.
- The contrast between pressured fundamentals in the core portfolio and headline friendly STEM outreach and AI driven logistics awards highlights how investors appear more focused on the durability of Church & Dwight's underlying demand than on brand marketing or operational accolades.
- We will now explore how Church & Dwight's investment narrative shifts when slower organic demand growth becomes harder to ignore in forecasts.
Church & Dwight Investment Narrative Recap
To own Church & Dwight here, you need to believe its big brands and e commerce reach can offset sluggish organic demand and modest earnings per share momentum. The immediate swing factor is whether core categories regain volume without heavy discounting. Recent news on slower organic growth makes that harder to argue as a near term tailwind.
The biggest operational risk remains soft consumption in underperforming segments and the drag from higher SG&A, including stranded costs from exited lower margin businesses. If sales stay muted while expenses remain elevated, earnings leverage could stall. The recent headlines do not materially change that equation; they simply keep the pressure on execution.
The Golden Kite Award for Strategic Intelligence around the FourKites partnership is the most relevant recent update for near term catalysts. Church & Dwight is using AI automation in logistics to improve on time pickups and deliveries while handling high communication volumes. That speaks directly to cost discipline and supply chain reliability as demand cools.
For you as an investor, this award matters only if those logistics gains translate into sustained service levels and controlled freight and warehousing spend. Better transportation visibility could help protect margins if revenue growth remains modest. The key watchpoint is whether these operational wins offset rising SG&A and the risk from weaker categories like vitamins and multivitamins.
What The Current Forecasts Assume For Church & Dwight
Church & Dwight's narrative projects revenues of US$6.9b and earnings of US$997.4m by 2029. This rests on analysts penciling in 3.4% yearly revenue growth and an earnings increase of about US$252.6m from US$744.8m today.
Those headline figures bundle several moving parts that matter for you. Forecasts build in higher profit margins, with analysts expecting an uptick from 12.0% earnings today to 14.5% in three years. That margin lift does a lot of the heavy lifting for the earnings number, since top line growth assumptions sit in the low single digits.
Earnings expectations also assume a modest share count reduction. Consensus has Church & Dwight buying back enough stock to reduce shares outstanding by roughly 1.22% each year over the next three years. That can support earnings per share even if the underlying profit pool grows at a slower pace than the headline earnings figure suggests.
Valuation work in the consensus set pins these 2029 projections to a P/E of 29.7x. That compares with about 30.2x on earnings today and sits above the current 22.6x P/E for the broader US household products group. The gap implies you would be paying a premium for the stock based on the forecasts, not a discount to the sector.
Price targets knit all of this together into a single reference point for the share price. The current analyst average target is US$105.11, with the most optimistic at US$115.00 and the lowest at US$78.00. Against a recent price of US$94.95, the midpoint implies potential upside of 9.7%, although the spread between bullish and bearish views shows that conviction on these forecasts is far from uniform.
Uncover why Church & Dwight's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
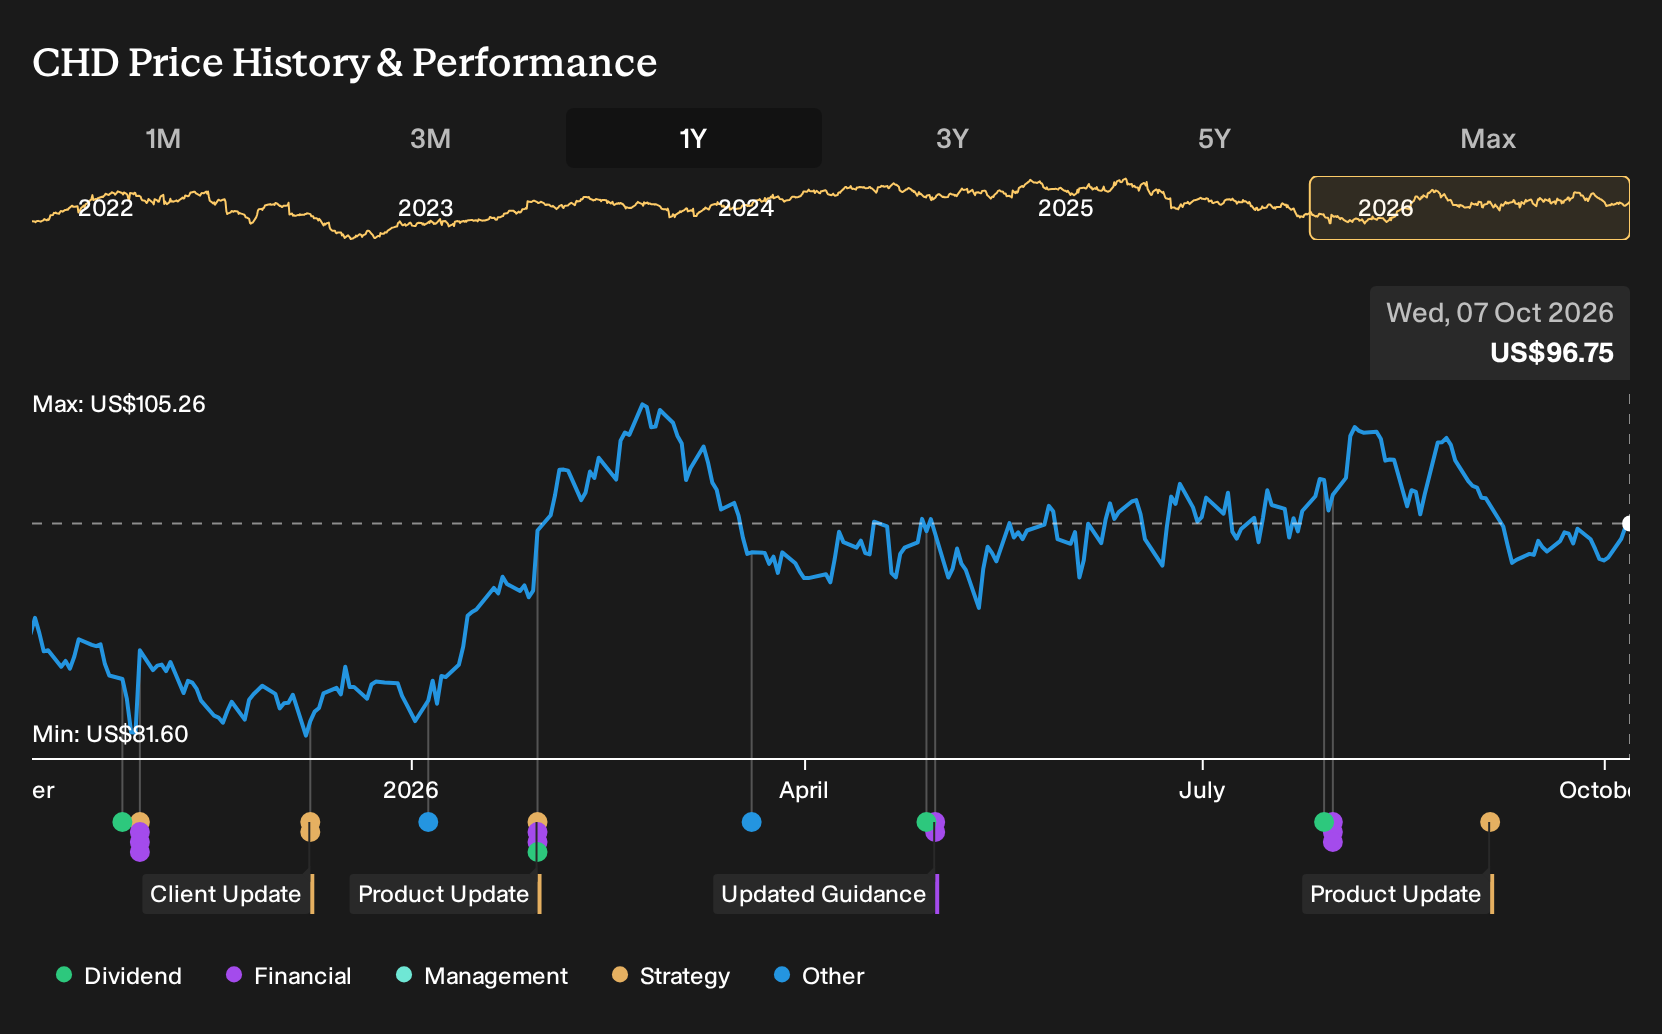
Exploring Other Perspectives
You might see the Golden Kite award as a clear catalyst for Church & Dwight, because it highlights AI driven logistics that could help protect profitability. The lowest analysts tell a cooler story. They were already assuming only 3.3% annual revenue growth and earnings of about US$1.0b by 2029. Their more cautious view could shift again once this news filters into models.
Explore 3 other Church & Dwight fair value estimates, including one that suggests as much as 13% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Church & Dwight research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Church & Dwight. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Church & Dwight's overall financial health at a glance.
Looking for more investment ideas beyond Church & Dwight?
If the Church & Dwight story leaves you wanting a broader watchlist, use this moment to widen your lens and scan for other businesses with profiles that better match your risk and return preferences.
- For readers who want quality at a reasonable entry point, start with companies that combine strong fundamentals with appealing pricing through our 29 high quality undervalued stocks.
- If resilience and financial strength sit at the top of your checklist, focus on businesses with robust balance sheets and consistent fundamentals by reviewing a list of solid balance sheet and fundamentals (25 results).
- Income focused investors can zero in on reliable cash return potential by screening for stocks in our 8 dividend fortresses that offer higher yield plus an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com