
SharkNinja (SN) Tests Valuation Following New Product Launches And A 2026 Outlook Lift
SharkNinja (SN) is back in focus after unveiling new Shark corded stick vacuums and the Ninja PREPi kitchen system, paired with an AI push that has management lifting its 2026 sales growth outlook.
That product drumbeat has been reflected in the tape, with SharkNinja’s share price returning 24.45% over 90 days and 62.66% year to date. The 1-year total shareholder return of 102.04% and 3-year total shareholder return of 330.30% point to strong, sustained momentum rather than a short-lived spike.
Capture SharkNinja’s momentum, then scan a curated set of 20 high quality undiscovered gems that may share similar product strength and execution.SharkNinja’s execution looks strong, and the share price has sprinted to reflect it. The next question is whether that momentum already fully captures what the business is worth today.
Most Popular Narrative: 67% Overvalued
Against SharkNinja’s last close of $185.19, the most followed narrative pegs fair value at $110.73, which implies the current share price sits well above that estimate based on the assumptions in that narrative.
SharkNinja makes products people genuinely seem to love. My brother-in-law hasn't stopped talking about his Ninja coffee machine. Every gym-goer seems to own a Ninja ice cream maker churning out protein ice cream. And don't get me started on how everyone now owns an air fryer. This is a brand that has quietly embedded itself into daily life and that kind of word-of-mouth loyalty is genuinely hard to manufacture.
See why 8 investors see SharkNinja as 67% overvalued.
According to AshleighG, the narrative assumes revenue growth gradually moderating from around 12% today toward 6% by 2030, with net margins edging toward 11% as direct to consumer sales scale and partly offset tariff pressure. On those inputs and a 9% discount rate, the implied fair value of $110.73 sits well below where SharkNinja trades today, suggesting the market is currently pricing in a richer outcome than that base case allows for.
Result: Fair Value of $110.73 (OVERVALUED)
Still, two pressure points could flip this SharkNinja story: weaker consumer spending on discretionary appliances and any renewed tariff hit to already watched margins.
Find out about the key risks to this SharkNinja narrative.
Another View: SWS DCF Sees SharkNinja As Undervalued
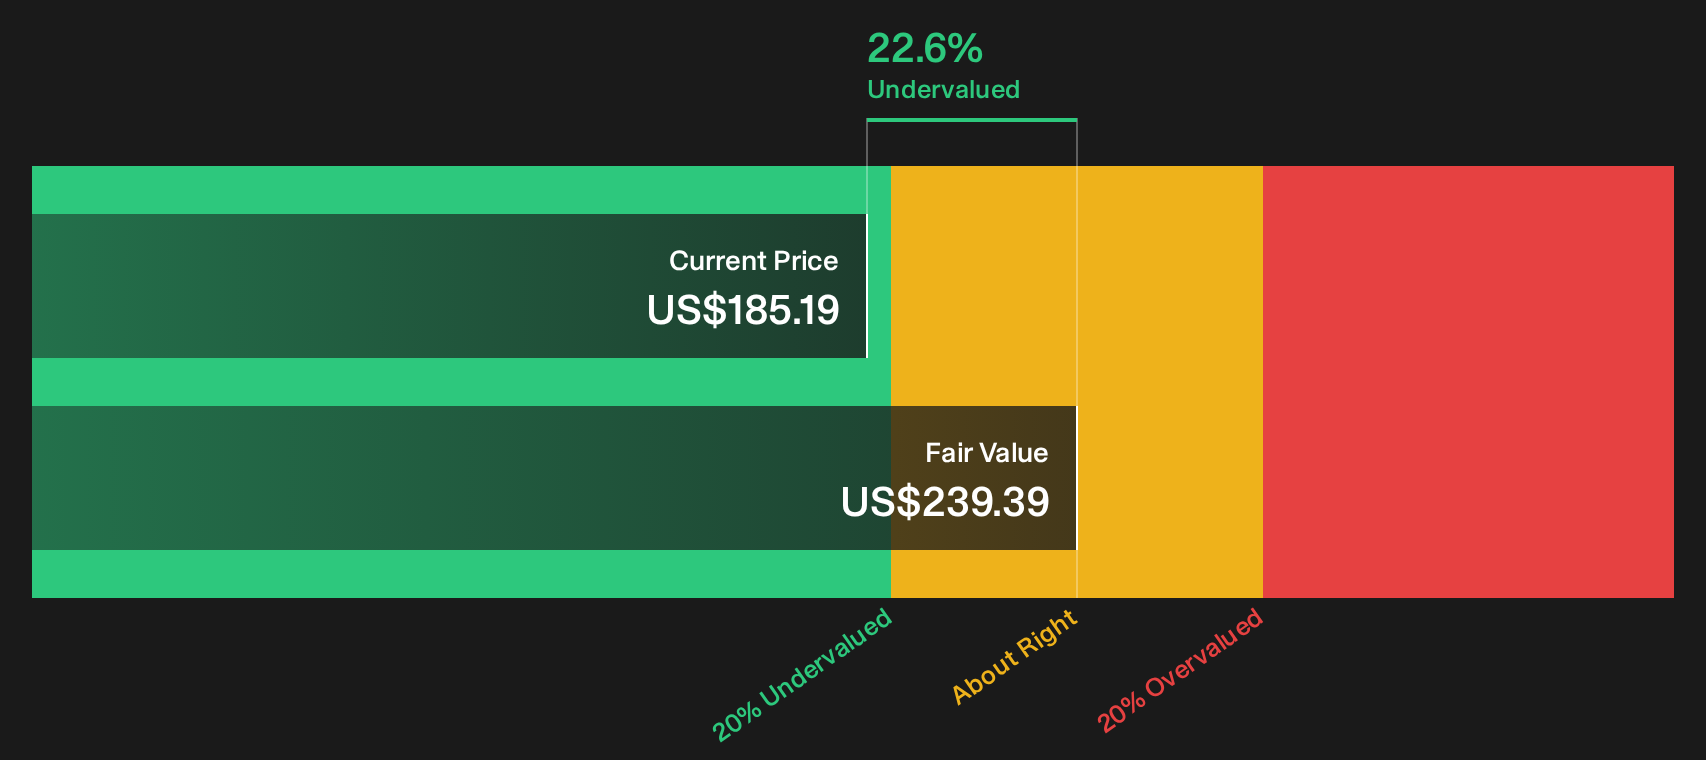
A second lens on SharkNinja flips the script. Our DCF model points to a fair value of $239.39 per share, which is above the current $185.19 price. On this framework, the stock trades at a 22.6% discount and screens as undervalued rather than stretched.
The gap between this SWS DCF model output and AshleighG's $110.73 narrative fair value comes down to inputs you cannot observe directly, such as long term growth, margins, and the return investors demand. That raises the key question for you as a shareholder: Which story about SharkNinja's future cash flows feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SharkNinja for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around SharkNinja’s valuation and outlook make this a moment to move quickly, review the data yourself, and stress test your own thesis using the 3 key rewards and 1 important warning sign.
Looking for more SharkNinja style ideas?
If SharkNinja has sharpened your focus on quality execution and clear stories, do not stop here. The screener can surface other compelling setups fast.
- Target resilient, cash generative businesses by running a filter on companies with strong fundamentals and balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Hunt for potentially mispriced opportunities by scanning the 29 high quality undervalued stocks that pair quality metrics with what could be attractive entry points.
- Prioritise stability and lower downside risk by reviewing a curated group of 31 resilient stocks with low risk scores that may better match a defensive playbook.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com