
CEO Change Could Be A Game Changer For Adeia (ADEA)
- Adeia announced that Dipti Vachani has been appointed CEO and board member, effective October 12, 2026, succeeding Paul E. Davis, and confirmed a multi year renewal of its intellectual property license agreement with Charter’s Spectrum brand covering pay TV, broadband and mobility services.
- The combination of a leadership change with deep semiconductor experience and a renewed IP deal with a major US operator highlights Adeia’s focus on recurring licensing revenue and cross sector monetization of its media portfolio.
- Investors can now evaluate how Adeia’s investment narrative could be influenced by Vachani’s appointment as CEO and her semiconductor licensing background.
Scan how Adeia’s licensing focus compares with other IP rich businesses by reviewing the hand picked 20 high quality undiscovered gems that could be pricing similar recurring revenue stories differently.
Adeia Investment Narrative Recap
Owning Adeia means believing it can continue converting its 14,250 patent portfolio into steady royalties across Pay TV, OTT, broadband and semiconductors, despite modest revenue forecasts and higher legal spending. The recent Charter renewal supports that core licensing thesis by keeping a major US customer on contract across multiple services.
In the near term, the key swing factor remains the timing and size of large media and chip licenses relative to rising litigation costs that could pressure margins. The Charter deal helps reduce renewal risk concentration but does not change the broader exposure to regulatory shifts around IP rights and Adeia’s debt load.
The most relevant announcement for that risk‑reward balance is the multi‑year renewal with Charter’s Spectrum brand. It gives Adeia clearer visibility on a portion of its US$470.87 million IP licensing revenue base across Pay TV, broadband and mobility, which can smooth revenue timing compared with a scenario where negotiations drift or end in litigation.
For catalysts, this agreement sits alongside earlier multiyear renewals such as Google and new e‑commerce licenses that support Adeia’s recurring model. Investors can weigh how stable contracts like Charter interact with slower forecast revenue growth, higher legal expense and an earnings outlook that consensus expects to decline about 0.9% annually over the next three years.
Adeia's analyst narrative projects US$465.5 million in revenue and US$106.8 million in earnings by 2029. This assumes revenue remains broadly flat over the next few years and implies an earnings decline of about US$15.9 million from current earnings of US$122.7 million.
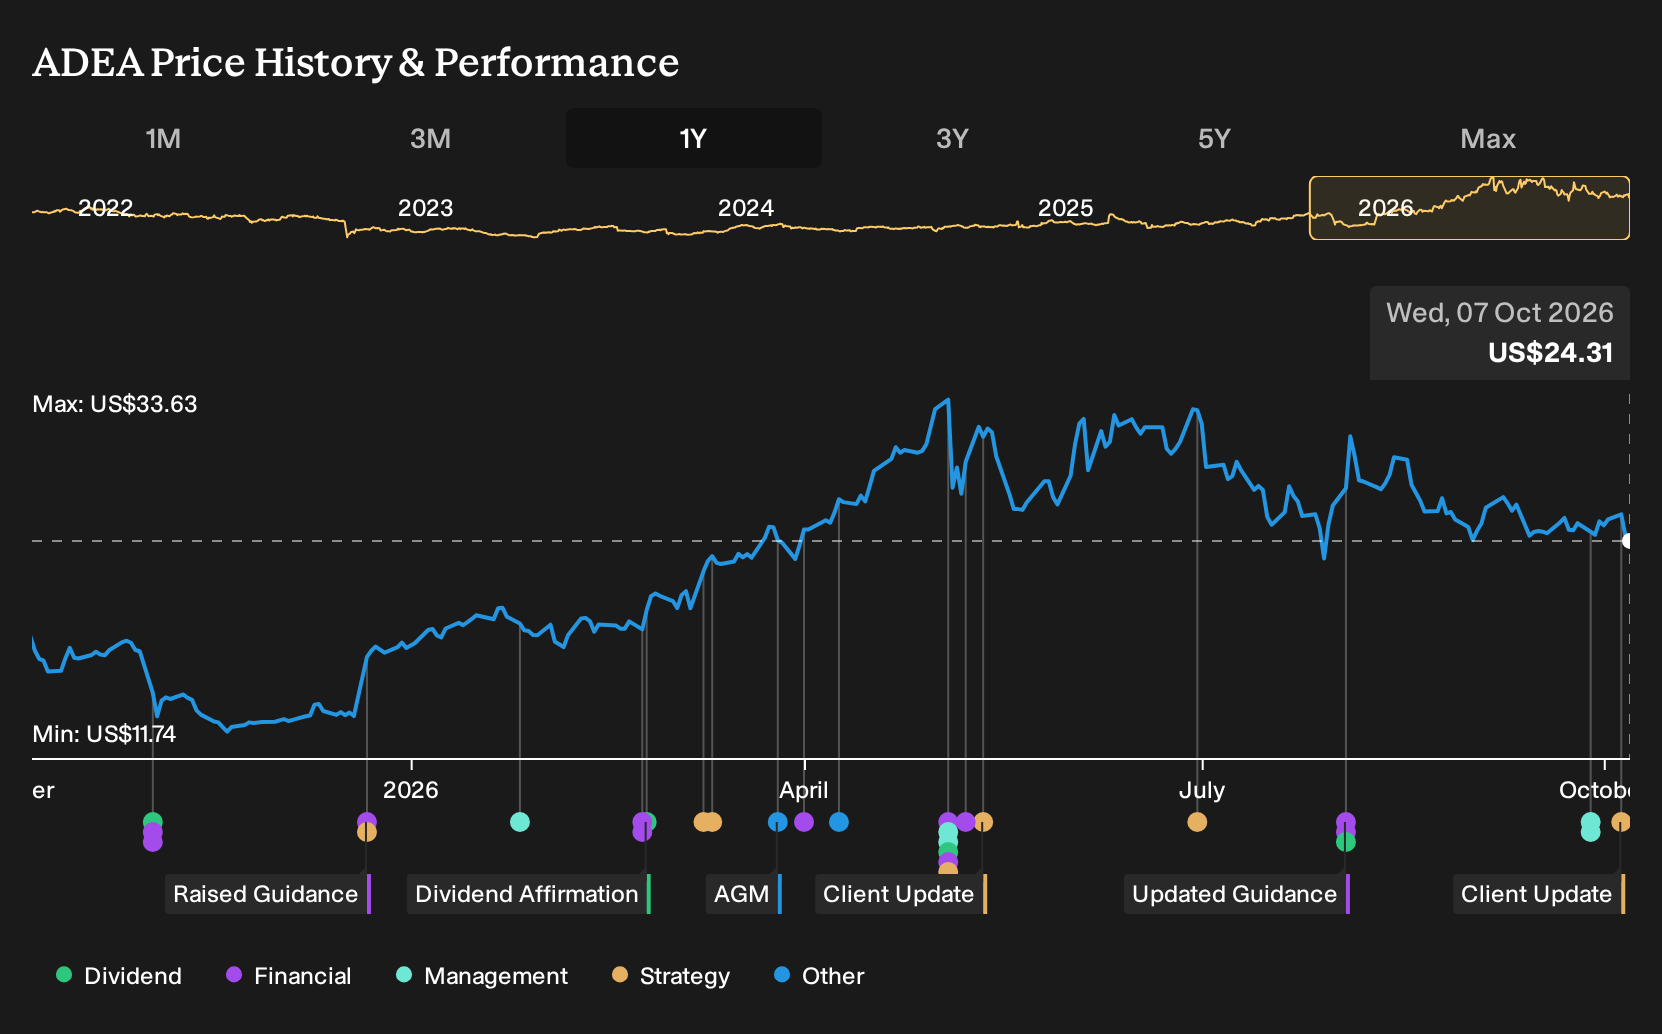
Uncover why Adeia's fair value indicates a 77% potential upside to its current price before the discount narrows.
Exploring Other Perspectives
You might see Adeia’s Charter renewal as a stabilizer, yet the most cautious analysts fixate on customer concentration risk. Before this news, they were working off 2029 estimates of about US$476.5 million in revenue and US$112.0 million in earnings. That is a tighter story, and it could shift once fresh viewpoints absorb these updates.
Explore 4 other Adeia fair value estimates, including one that suggests as much as 21% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Adeia research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Adeia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adeia's overall financial health at a glance.
Looking for more Adeia style investment ideas?
If Adeia's licensing story has your attention, it can help to compare it with other businesses that share traits like recurring income, solid balance sheets or lower risk profiles. The Simply Wall St Screener can surface those kinds of opportunities in a few clicks.
- For investors who want potential mispricings with stronger fundamentals, start with a curated set of 29 high quality undervalued stocks that might offer a different balance between quality and price.
- If capital preservation sits higher on your priority list, filter for companies in the 31 resilient stocks with low risk scores to see which businesses carry more resilient risk profiles.
- When balance sheet strength matters most, focus on the list of solid balance sheet and fundamentals (25 results) and look for businesses where financial footing supports long term compounding.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com