
Expedia Group (EXPE) Stock Could Still Be A Bargain On Earnings
Expedia Group has delivered a powerful 153.3% gain over the past three years, yet its share price has slipped in recent weeks, which naturally raises the question of whether the current US$258.86 level still lines up with the travel platform's earnings power. With new loyalty perks and travel benefits rolling out, the issue for you as an investor is how much of that story is already embedded in the valuation.
- The 153.3% return over three years puts pressure on the earnings case because more of the thesis now rests on what the business can sustainably earn rather than on a simple rebound story.
- Fresh Expedia One Key benefits such as lounge access during delays, discounted CLEAR+ membership and Price Drop Protection may support expectations for future demand and spending, which matters for how much investors are willing to pay for each dollar of profit.
- There is a second opinion on Expedia Group worth weighing. See what analysts think Expedia Group's shares could be worth.
The stock's next move may depend on whether Expedia Group's current price can be squared with what its earnings justify today.
To see how Expedia Group's loyalty push compares with other travel and leisure opportunities, evaluate it alongside companies in the 29 high quality undervalued stocks
Is Expedia Group Still Cheap on Earnings?
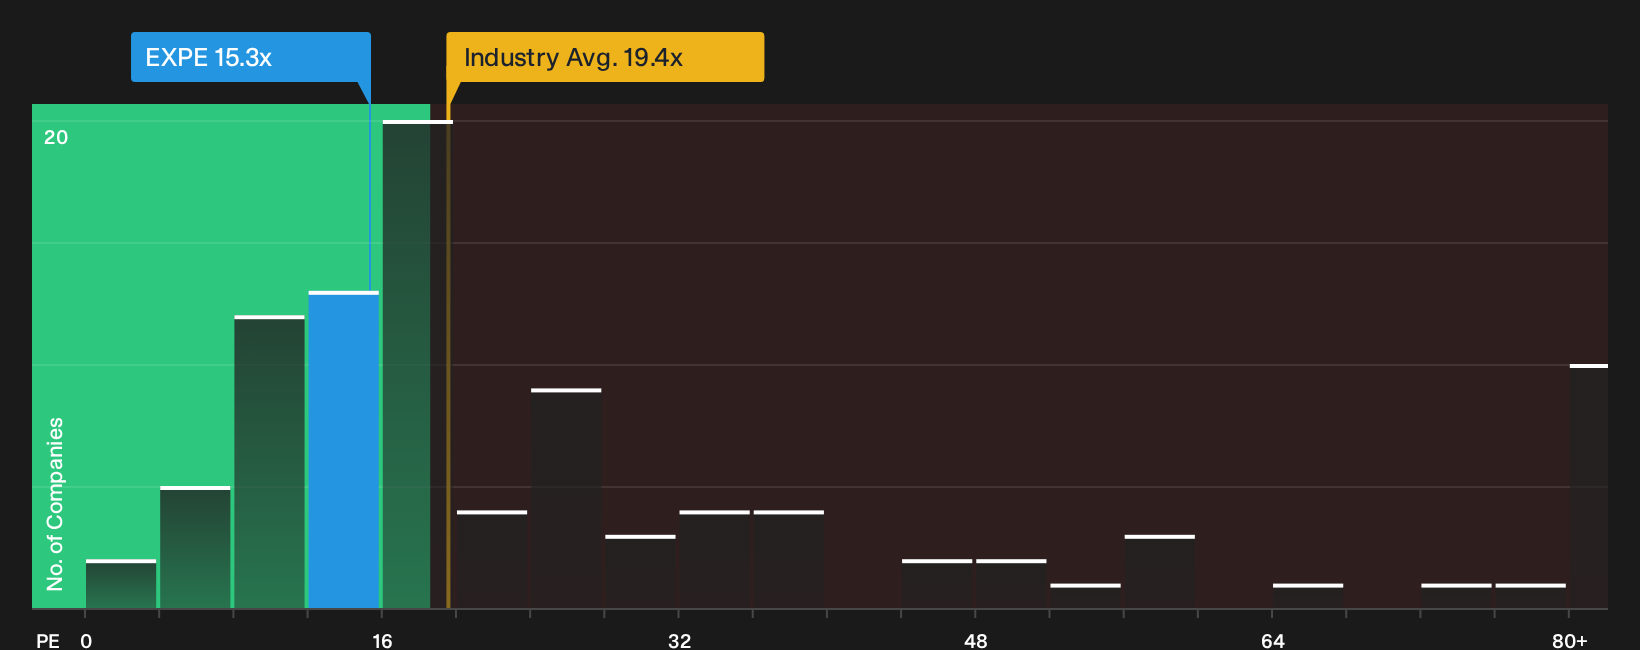
P/E tends to fit Expedia Group because earnings still drive the story more than assets or revenue scale. At about 15.3x earnings, the stock trades below the Hospitality sector average of roughly 19.4x and also under the peer group on about 22.6x. That signals the market is asking for a lower price for each dollar of Expedia Group profit than it does for many travel related businesses with similar economics.
The Fair Ratio, which reflects what investors might usually pay for Expedia Group given its sector, margins and risk profile, sits above the current P/E, so the shares screen as undervalued on this yardstick. Because the fresh One Key perks have sharpened the loyalty pitch without pushing the multiple toward peer levels yet, the valuation still prices in a discount to what comparable companies command on earnings. Explore the numbers behind Expedia Group's P/E valuation.
The Expedia Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Expedia Group leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today's price. Each scenario pins a fair value estimate to a clear story about Expedia Group's potential catalysts and risks, so you can track over time which version of events seems closest to what the business is actually delivering.
Expedia Group splits opinion, with some investors seeing meaningful upside in the execution story while others think most of the value is already recognised.
Bull case: 24% undervalued
"Expansion of Expedia Group’s unified technology platform and automation, including AI supported developer tools that are delivering roughly 40% faster tech and product cycle times..."
Discover why this Narrative puts Expedia Group at 24% undervalued.
Bear case: roughly fairly valued
"Although Expedia Group is leaning into AI driven personalization and faster product cycles, the rise of third party AI assistants that can steer users directly to suppliers risks muting the benefit of these tools..."
Explore why this Narrative puts Expedia Group at roughly fairly valued.
One more piece of the Expedia Group puzzle to check
Analyst projections for Expedia Group over the next few years offer a separate reference point to compare with today's earnings multiple and loyalty story, and the gap between those expectations and your own view can be crucial. Explore where analysts expect Expedia Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com