
Preformed Line Products (PLPC) Looks Fully Priced After Its 91% Run This Year
Preformed Line Products (PLPC) has drawn fresh attention after recent price moves, with the stock closing at $404.67. Investors are weighing that level against its value metrics, growth figures, and recent return profile.
Recent trading has cooled slightly, with the share price slipping 4.0% in the last session, yet Preformed Line Products still carries strong momentum after a 90.95% year to date share price return and a 1 year total shareholder return of 102.47%.
Scan beyond Preformed Line Products and review other grid and infrastructure plays by exploring our hand picked 43 power grid technology and infrastructure stocks that reflect a similar price and momentum story.
So is Preformed Line Products at $404.67 mostly reflecting a stronger underlying grid hardware business, or has enthusiasm simply run ahead of what the current fundamentals support?
Price-to-Earnings of 45.9x: Is it justified?
On a simple snapshot, Preformed Line Products trades on a P/E of 45.9x, which puts a rich tag on the recent $404.67 closing price when stacked against both peers and the broader Electrical group.
The P/E ratio compares what investors are willing to pay today for each dollar of current earnings. For a grid hardware and communications infrastructure supplier like Preformed Line Products, a higher P/E often signals that the market is baking in stronger profit growth, steadier earnings quality, or a business mix that investors see as relatively resilient.
Current data points in a different direction. PLPC is described as expensive versus the peer average P/E of 31.9x, and also expensive against the wider US Electrical industry average of 36.9x. The stock is also trading above an estimated fair P/E of 26.1x. This suggests the current earnings multiple is materially higher than a level the market could move toward if sentiment cools or expectations reset.
Explore the SWS fair ratio for Preformed Line Products.
Result: Price-to-Earnings of 45.9x (OVERVALUED)
Still, any setback in grid spending or a reset in expectations around Preformed Line Products earnings could quickly pressure that 45.9x P/E narrative.
Find out about the key risks to this Preformed Line Products narrative.
Another View on Preformed Line Products Using Cash Flows
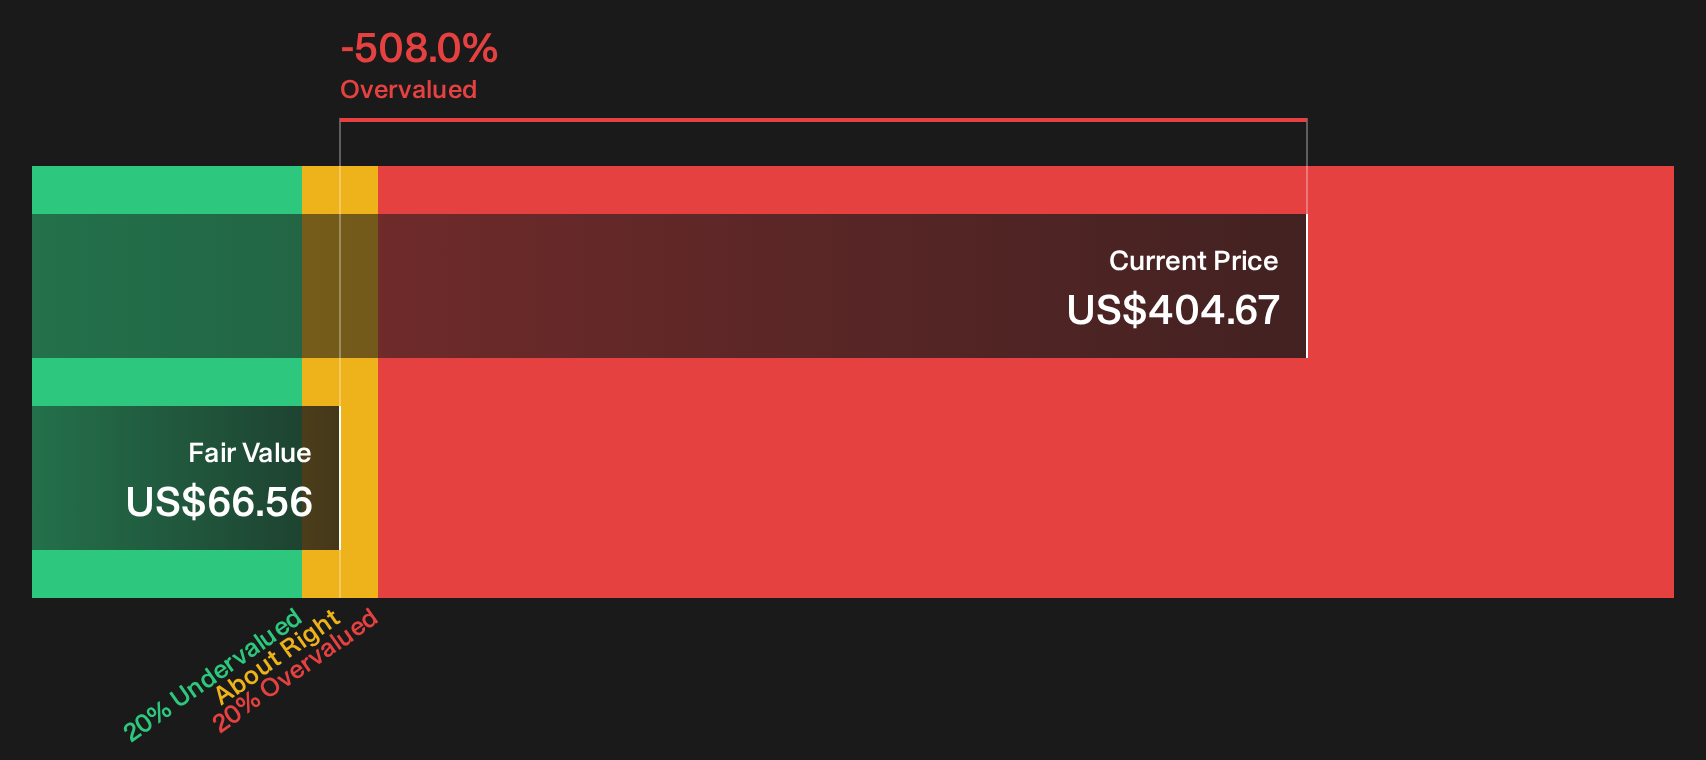
The P/E argument portrays Preformed Line Products as expensive, and the SWS DCF model amplifies that concern. On this framework, the current $404.67 share price sits well above an estimated future cash flow value of $66.56, which indicates a deeply overvalued profile on cash flow terms.
That kind of gap can matter for you as an investor, because if sentiment cools and pricing begins to track cash generation more closely, the adjustment could be sharp rather than gradual. The key question is whether you believe PLPC can grow into this valuation quickly enough to close that distance.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Preformed Line Products for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Preformed Line Products is clearly mixed, with a rich valuation on one side and flagged concerns and upside potential on the other. Act quickly, review the full risk and reward balance, and decide where you stand with the 1 key reward and 2 important warning signs
Looking for more Preformed Line Products investment ideas?
If Preformed Line Products at $404.67 feels fully priced, do not stall. Use the Simply Wall Street Screener to hunt for fresher, more compelling setups next.
- Target resilient balance sheets and fundamentals first, then filter further using the list of solid balance sheet and fundamentals (25 results) that keeps financial strength front and center in your process.
- Hunt for mispriced quality where expectations still look reasonable by working through the 29 high quality undervalued stocks that filters for both strength and potential upside.
- Stack your watchlist with potential sleepers by reviewing the 20 high quality undiscovered gems that surfaces quality businesses many investors have not seriously reviewed yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com