
Daisy Milano Extension Might Change The Case For Investing In Macmahon Holdings (ASX:MAH)
- Macmahon Holdings secured a two year extension in 2026 for underground mining services at Vault Minerals' Daisy Milano Gold Mine in Western Australia, a contract valued at about A$98 million and now running through to late October 2028.
- The Daisy Milano extension reinforces Macmahon Holdings' shift toward deeper underground work, which can support more recurring activity alongside civil infrastructure projects.
- We will look at how Macmahon Holdings' broader investment narrative is influenced by this A$98 million Daisy Milano contract extension.
Scan for more contract rich miners like Macmahon Holdings by jumping into the hand picked list of solid balance sheet and fundamentals (12 results) that could handle multi year underground commitments and civil work side by side.
Macmahon Holdings Investment Narrative Recap
To own Macmahon Holdings, you need to believe the contractor can keep converting its order pipeline into long term underground and civil work while holding margins steady. The Daisy Milano extension helps the near term story by adding more contracted visibility. It supports the current focus on underground mining, but does not radically change the overall business mix.
The key short term catalyst still sits in how effectively Macmahon Holdings replaces any completed large projects and prices new tenders in a competitive market. The biggest risk remains contract churn or clients shifting to owner operator models. That could leave gaps in utilisation if replacement work or civil projects do not line up cleanly.
With company announcements thin around this specific Daisy Milano news, the most relevant context is the broader diversification push already under way in Macmahon Holdings. The business now spans surface and underground mining, international work and civil infrastructure, including the Decmil acquisition. Daisy Milano fits into that pivot toward deeper underground capability rather than changing direction.
For you, the link to catalysts is straightforward. Contract renewals such as Daisy Milano matter most when viewed against risks mentioned earlier around pricing pressure and client concentration. Each renewal or extension that runs through to dates like late 2028 slightly improves revenue visibility, but execution quality, fleet investment and debt discipline still drive how much value the existing contract book ultimately delivers.
Macmahon Holdings' narrative projects A$3.5b revenue and A$174.3 million earnings by 2029. This is based on assumed 10.4% yearly revenue growth and an increase in earnings of about A$73.2 million from A$101.1 million today.
Discover why Macmahon Holdings' fair value appears to be generally consistent with its current price.
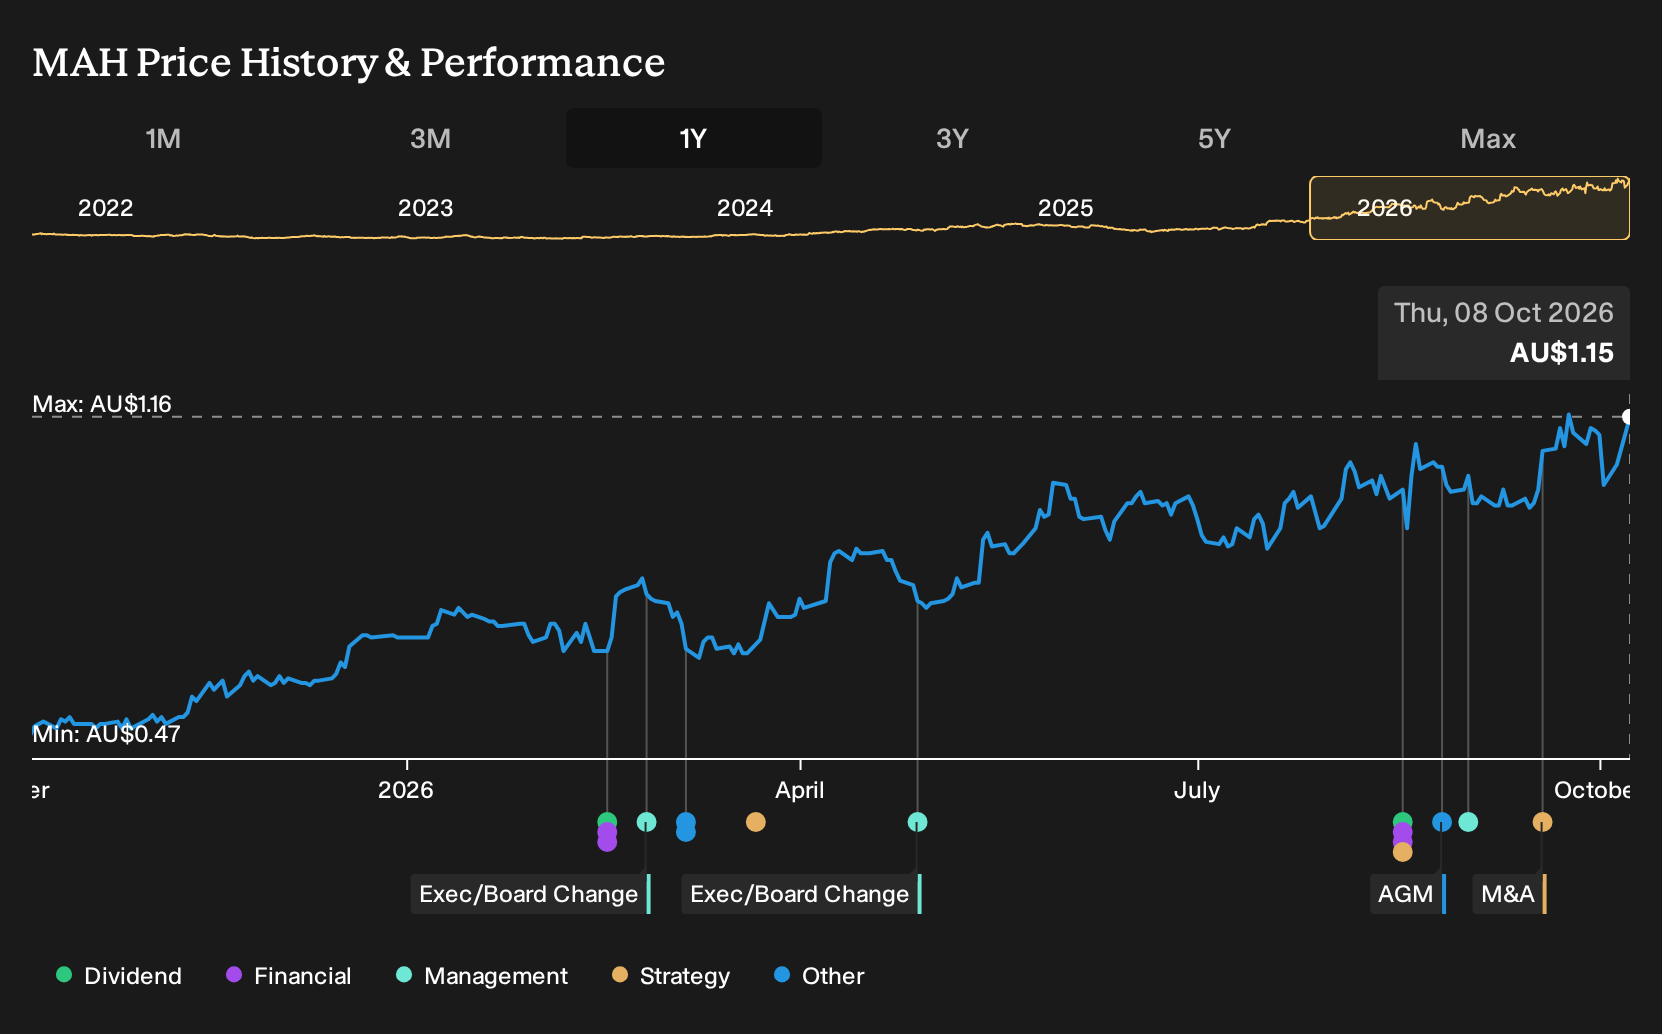
Exploring Other Perspectives
Pessimistic analysts focus on a different angle. They worry that Macmahon Holdings' heavy exposure to traditional gold and copper work could clash with longer term shifts in commodity demand. Before this Daisy Milano news, the most optimistic group already modelled A$3.6b revenue and A$189.6 million earnings by 2029. You can now ask whether underground contract extensions like this push those bullish expectations closer to the mainstream or force everyone to revisit their assumptions from both directions.
Explore 5 other Macmahon Holdings fair value estimates, including one that suggests up to 124430% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Macmahon Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Macmahon Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Macmahon Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Macmahon Holdings?
Once you have a handle on Macmahon Holdings, it can help to widen the lens and compare it with other companies that share similar financial strengths or risk profiles. The Simply Wall St Screener gives you a structured way to do that, so you are not just reacting to headlines but lining up a shortlist that actually fits your approach.
- If resilience and balance sheet strength matter most to you, start with a list of solid balance sheet and fundamentals (12 results) that can better weather funding cycles and contract timing.
- For investors who care most about valuation and fundamentals, scan through 5 high quality undervalued stocks that combine healthier cash flows with more disciplined financial profiles.
- If you prefer something a little more off the radar, review 15 high quality undiscovered gems that pair quieter market attention with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com