
South Africa Expansion Might Change The Case For Investing In Equinix Stock
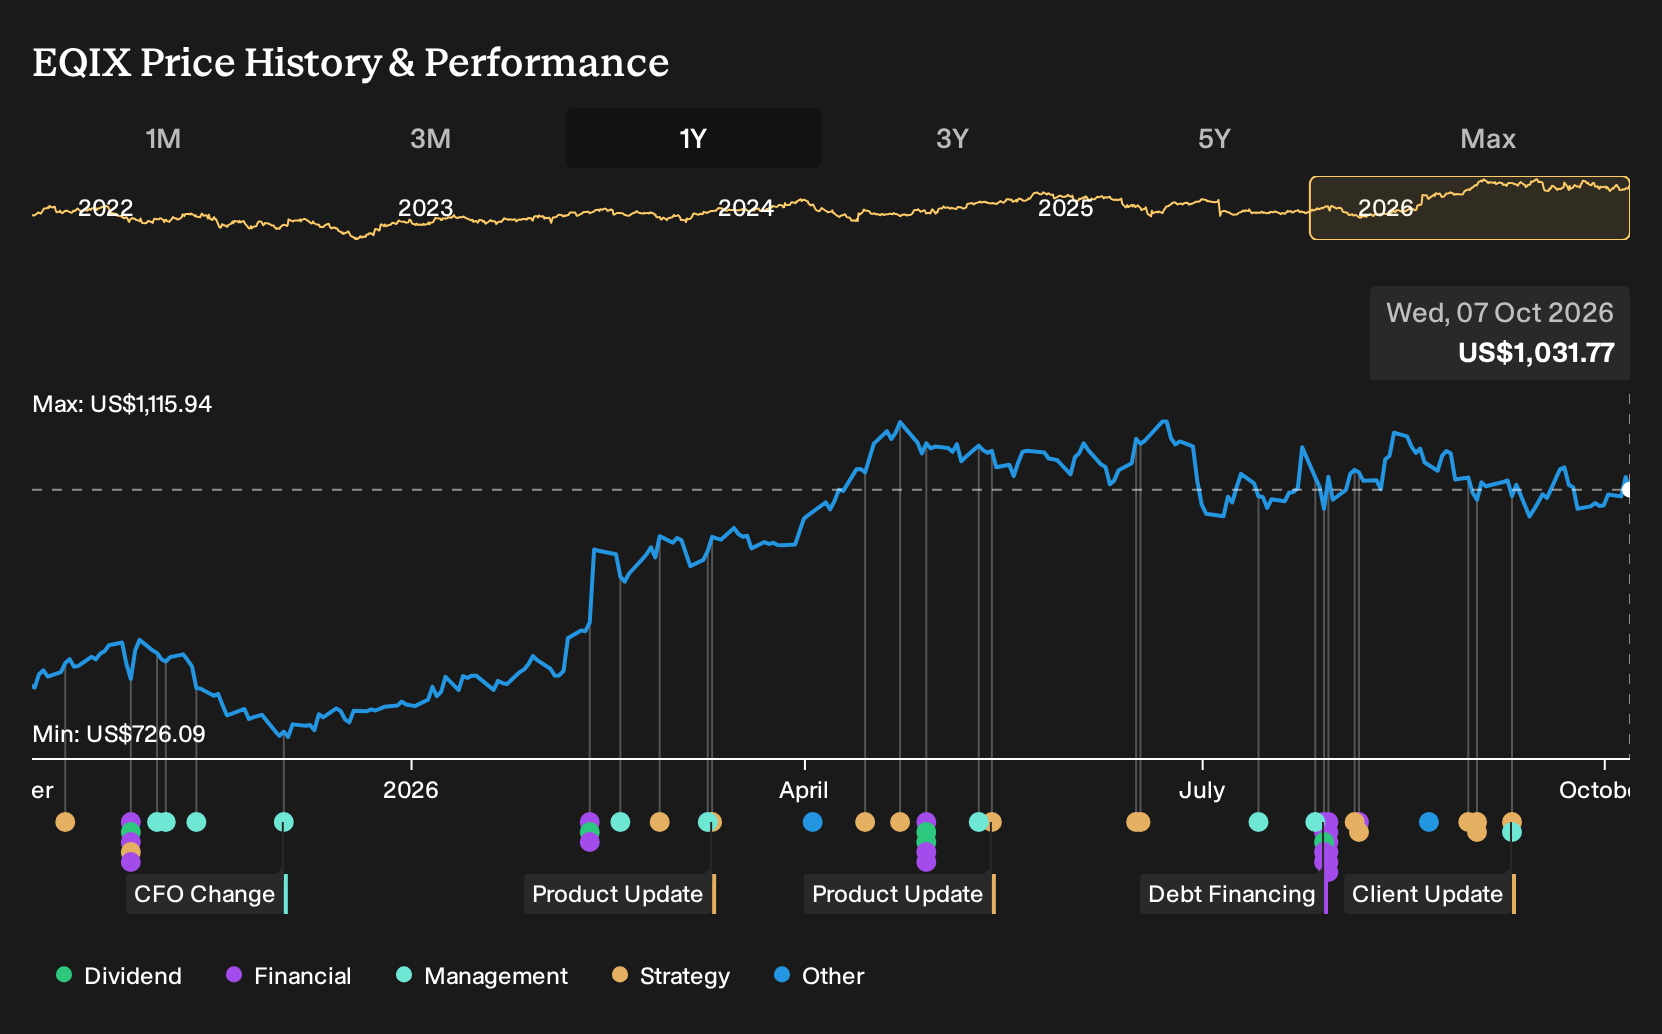
- Equinix recently presented at the Yotta 2026 conference in Las Vegas, where Senior Director of Global Design Greg Metcalf outlined the group’s approach to data center design and deployment.
- The company is also active in South Africa’s expanding colocation market, where rising cloud, AI and digitalization demand is drawing capital alongside government incentives.
- We will now examine how Equinix's investment narrative is shaped by its South African data center push and its focus on AI ready infrastructure.
Equinix Investment Narrative Recap
For you to own Equinix, you need to believe that its large build program can keep converting AI-heavy demand into long-term recurring cash flows without compressing returns. The Yotta 2026 presentation supports that view, since it underlines an ongoing design focus on dense, AI-ready sites in power-constrained markets. As a near-term catalyst, execution on that 600 MW development pipeline and progress toward 1 GW under production look more important than this single conference appearance.
The key risk remains on the supply side. Grid access, skilled construction labor and permitting all have the potential to slow builds or squeeze project economics. That matters for a business carrying meaningful debt and a rich 66.4x P/E multiple. If construction and financing costs increase more than expected, the spread between target returns in the low to mid-20% range and the cost of capital could narrow.
The Yotta 2026 session helps link Equinix’s broader development story with the push into South Africa’s colocation market. Management is talking publicly about AI-oriented design at the same time the region is drawing capital on the back of cloud demand, government support and enterprise digitalization. For investors, that ties directly to the plan to deploy US$5 billion to US$7 billion per year in new projects from 2027 to 2029.
That spending plan is a core catalyst because it is intended to turn Equinix’s roughly 3 GW of designed power into higher recurring revenue and funds from operations over time. The same build cycle carries clear execution risks. Power constraints, local opposition or higher build costs in markets such as South Africa could limit how much of those targeted low to mid-20% cash-on-cash returns ultimately appear in earnings and cash flow.
Equinix's current analyst story points to revenues of US$13.5b and earnings of US$2.3b by 2029, based on an assumed 10.8% yearly revenue growth rate and an increase in earnings of about US$0.8b from US$1.5b today.
Uncover why Equinix's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community span roughly US$1,233 to US$1,638 per share, so retail opinions on Equinix already stretch from cautious to optimistic. Before the Yotta 2026 update and South Africa build plans are even factored in, you are seeing how far views can diverge. Supply constraints, political friction and the sheer scale of that US$5b to US$7b annual development program could all shift how these private investors rethink revenue durability and cash generation. Use this spread as a prompt to test your own thesis and explore several alternative viewpoints before deciding where you sit in that range.
Explore 2 other Equinix fair value estimates, including one that suggests as much as 59% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Equinix research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Equinix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Equinix's overall financial health at a glance.
Looking For More Ideas Beyond Equinix?
Once you have a view on Equinix, it often helps to compare it with a few very different opportunities. That contrast can sharpen your thinking, highlight what risk level you are genuinely comfortable with, and keep you from anchoring on a single story stock.
The Simply Wall St Screener can surface a wide mix of companies that fit clear, fundamentals based criteria. A few starting points are below.
- If capital preservation sits high on your list, consider starting with a group of businesses that screen for financial resilience through a 31 resilient stocks with low risk scores.
- For readers hunting for quality on sale, you can focus on companies that combine strong fundamentals with appealing prices through a curated 29 high quality undervalued stocks.
- Those who care most about balance sheet strength can zero in on financially robust candidates by scanning a list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com