
Why Yakult HonshaLtd (TSE:2267) Is Getting Attention Today
Yakult Honsha Ltd (TSE:2267) has completed a share repurchase program that ran from July to September 2026, buying 3,863,600 shares, or 1.34% of its stock, for ¥10,999.8 million.
Yakult Honsha Ltd’s completed buyback lands at a time when momentum has cooled in the short term, with a 30 day share price return of 2.46% and a 90 day share price return of 2.87%. At the same time, the year to date share price return sits at 12.47% and the 1 year total shareholder return is 18.44%, against a weaker 3 year total shareholder return that declined 19.69% and a 5 year total shareholder return of 5.87%. Taken together, these figures suggest that recent sentiment has improved compared with a softer longer term experience.
Scan how Yakult HonshaLtd’s completed buyback compares with other companies returning cash to shareholders by reviewing the 32 dividend fortresses in the market right now.
Yakult Honsha Ltd has just finished a ¥10,999.8 million buyback, which can change how you think about value at today’s ¥2,759 share price. Is it worth entering now, or waiting for a cheaper shot later?
Most Popular Narrative: 16.9% Undervalued
Yakult Honsha Ltd’s most followed valuation narrative points to a fair value of ¥3,318.84 against a last close of ¥2,759. This frames the latest buyback inside a story of discounted pricing and debated earnings power.
While analysts broadly recognize operating margin improvement potential from international expansion, they may be underestimating Yakult's ability to capture margin uplift as ongoing cost management and manufacturing scale, combined with localization in low-cost emerging markets, could drive much stronger-than-expected margin expansion and earnings leverage.
See why 0 investors see Yakult HonshaLtd as 17% undervalued.
Result: Fair Value of ¥3,318.84 (UNDERVALUED)
Still, Yakult Honsha Ltd faces pressure from weaker dairy volumes in Japan and rising input costs. Any prolonged squeeze on margins could quickly challenge this upbeat valuation story.
Find out about the key risks to this Yakult HonshaLtd narrative.
Another View On Yakult Honsha Ltd’s Valuation
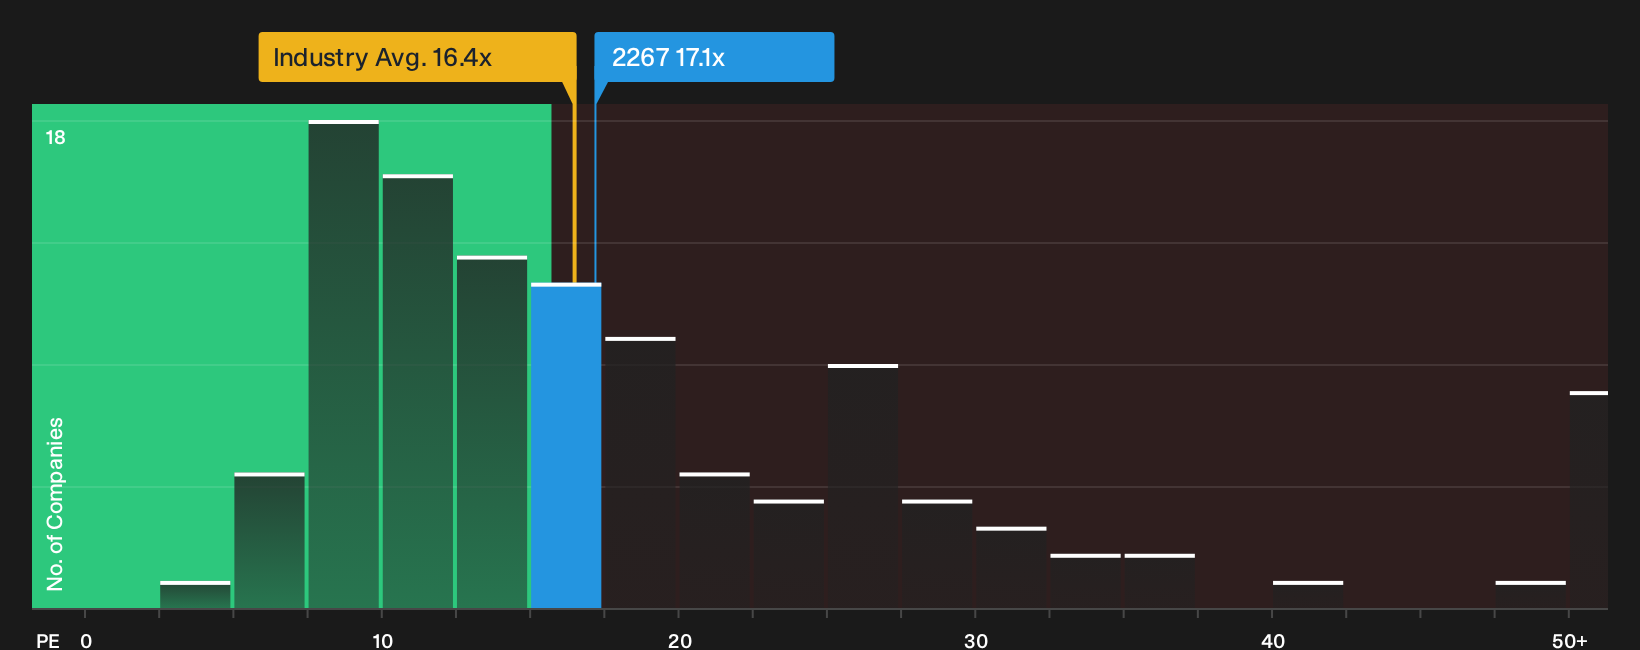
The most followed fair value for Yakult Honsha Ltd sits at ¥3,318.84 and frames the stock as 16.9% undervalued. Yet on plain P/E math, the picture is less generous. The shares trade on 17.1x earnings, compared with 16.4x for the JP Food industry and 16.1x for the fair ratio our model suggests the market could move toward. That premium may be small, but it raises a simple question: Is Yakult Honsha Ltd priced for more earnings strength than analysts currently forecast.
For a closer look at how this earnings multiple stacks up and what it might mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about Yakult Honsha Ltd after this buyback and valuation debate. Act quickly, stress test the numbers yourself, then weigh the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Yakult Honsha Ltd?
If this Yakult Honsha Ltd story leaves you wanting a wider playbook, use the Simply Wall Street Screener to line up your next move before the crowd does.
- Target dependable income streams by reviewing the 32 dividend fortresses that combine higher yields with resilient fundamentals.
- Hunt for potential mispriced opportunities by scanning the 14 high quality undervalued stocks that match quality metrics with discounted valuations.
- Prioritise capital preservation first by focusing on the 22 resilient stocks with low risk scores that score well on balance sheet strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com