
Caught Out By Melrose Industries' Fall? What The Bears Saw
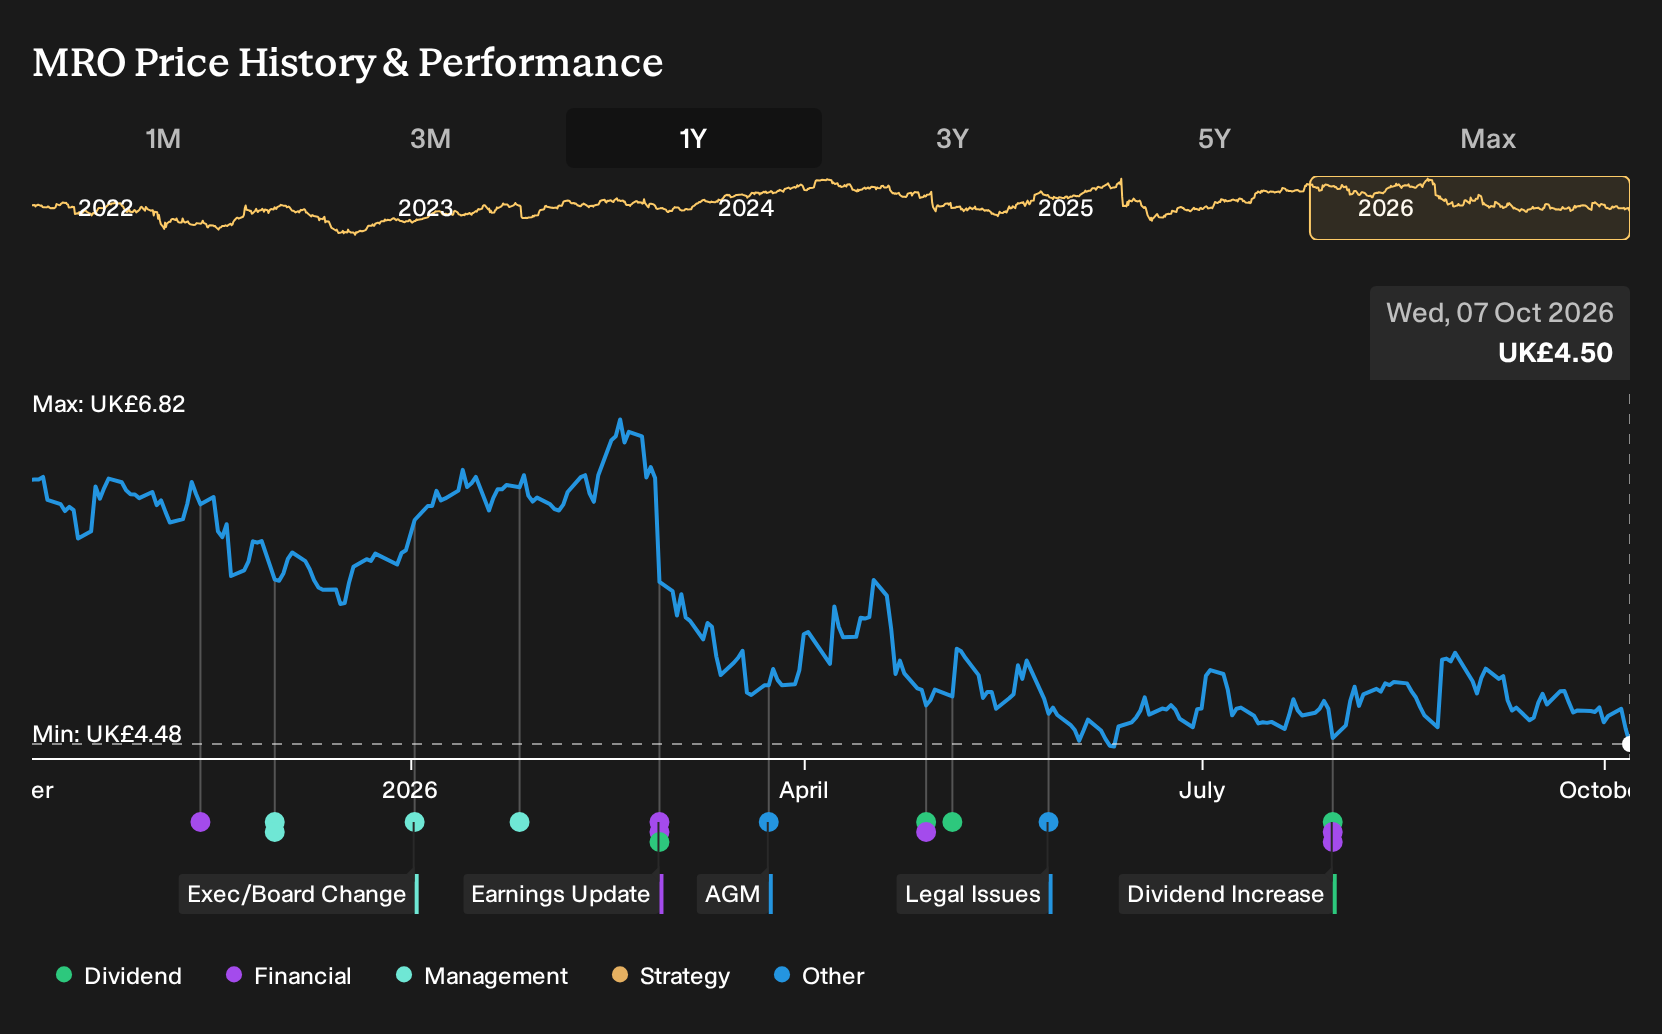
If you had hesitated on Melrose Industries in October 2025, the missed opportunity might look very different now. For Melrose Industries shareholders, the loss over the past year was 28.5%, including dividends. The latest interim report added a fresh jolt, with higher revenue but a much slimmer net margin as profit dropped sharply. The harder question is what assumption about future earnings resilience or margin predictability could have signalled that risk before any of this was visible.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Melrose Industries harder to judge, start where the gap is still open and scan 8 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Melrose Industries
The shares cost £6.39 at the start of the period, and investors in Melrose Industries were pulled between two very different stories that both relied on decarbonization and aircraft replacement staying powerful themes.
The bullish narrative set Fair Value at £8.25 and relied on the idea that margin expansion and free cash flow growth could run ahead of consensus as volumes picked up and restructuring benefits came through earlier.
The bearish view set Fair Value at £4.01 and focused on the risk that reliance on major engine customers and heavy investment needs for greener aviation technology could pressure net margins for years.
What The Results Changed For Melrose Industries
The most concrete update for Melrose Industries was the H1 2026 result. Revenue moved from £1,720m in H1 2025 to £1,873m in H1 2026, which backed the idea that demand was there, but net income slipped from £285m to £75m and net margin dropped from 16.6% to 4.0%. That margin squeeze supported the cautious case more than the optimistic one.
The practical lesson is simple. When a story leans on margin resilience, track net margin and profit alongside sales. For any other contractor or aerospace group you look at, check whether rising revenue is actually turning into higher earnings or whether costs are quietly rewriting the thesis.
What You Would Be Paying For In Melrose Industries Today
Melrose Industries now trades at £4.5, and the selected Narrative places its Fair Value above that level based on a cash flow centred view of the aerospace franchise.
The argument leans on aftermarket engines, restructuring and additive manufacturing. For the recent fall to look like an opening rather than a warning, a buyer must judge that cash generation and margins will progress despite operational setbacks.
"The engines risk and revenue sharing portfolio, with 17 of 19 programs already cash generative and the GTF expected to move to positive cash contribution as inspection costs fall away and upgraded configurations drive more customer funded shop visits, can create a step up in high margin aftermarket cash inflows that may not be fully reflected in longer term earnings forecasts."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 24% below our estimate - uses a dispersed, tech enabled partnership structure to attract experienced legal professionals.
- Company 2 - 30% below our estimate - rolls out upgraded adviser and direct platforms designed to deepen investor engagement.
- Company 3 - 26% below our estimate - adds automated production lines and expanded warehousing capacity to streamline order fulfilment.
Three companies from the same screener. Open the full list of 9 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com