
KLA (KLAC) Draws Fresh Analyst Attention, Is The Stock Fully Valued?
How recent analyst attention reframed KLA’s story
KLA (KLAC) has been back in the spotlight after a Zacks upgrade to Rank #2, reflecting a recent trend of higher earnings estimates and fresh commentary on its role in AI-focused chip manufacturing.
That attention did not appear from nowhere. Analysts have been revising their profit forecasts higher over the past three months, pointing to KLA’s process control tools and advanced packaging exposure as core pieces of current AI infrastructure investment themes.
Recent headlines around KLA’s AI exposure have come after a strong run, with the 30-day share price return of 6.05% and a year-to-date share price gain of 54.44% contributing to very large 5-year total shareholder returns of 544.91%.
Short-term momentum has cooled a little with the 90-day share price return falling 14.24%. However, the 1-year total shareholder return of 86.24% and roughly 7x total shareholder return over three years indicate that investors have been steadily pricing in both growth potential and higher perceived risk around AI-driven semiconductor spending and export restrictions.
Scan beyond KLA and map out other potential AI infrastructure beneficiaries with the curated list of 91 AI infrastructure stocks that is shaping chip capacity and data center build outs.
KLA looks like a clear winner in AI tooling, yet the share price has already moved hard on that story. Is this still a solid business at a fair tag, or now a quality company on an expensive ticket?
Most Popular Narrative: 16% Undervalued
On the most followed view, KLA’s fair value of $233.77 sits well above the recent $196.83 close, which puts the Zacks upgrade into clearer context for anyone weighing how much optimism is already in the price.
Rising AI infrastructure and high bandwidth memory investment is lifting wafer equipment demand, and KLA’s backlog of around US$12.5b with lead times that extend into 2027 and 2028 supports multi year visibility that can translate into higher revenue and earnings quality.
See why 109 investors see KLA as 16% undervalued.
Result: Fair Value of $233.77 (UNDERVALUED)
Still, KLA’s heavy exposure to China and the long dated US$12.5b backlog mean that tariff shifts or order pushouts could quickly challenge that underpriced narrative.
Find out about the key risks to this KLA narrative.
Another view on KLA’s valuation
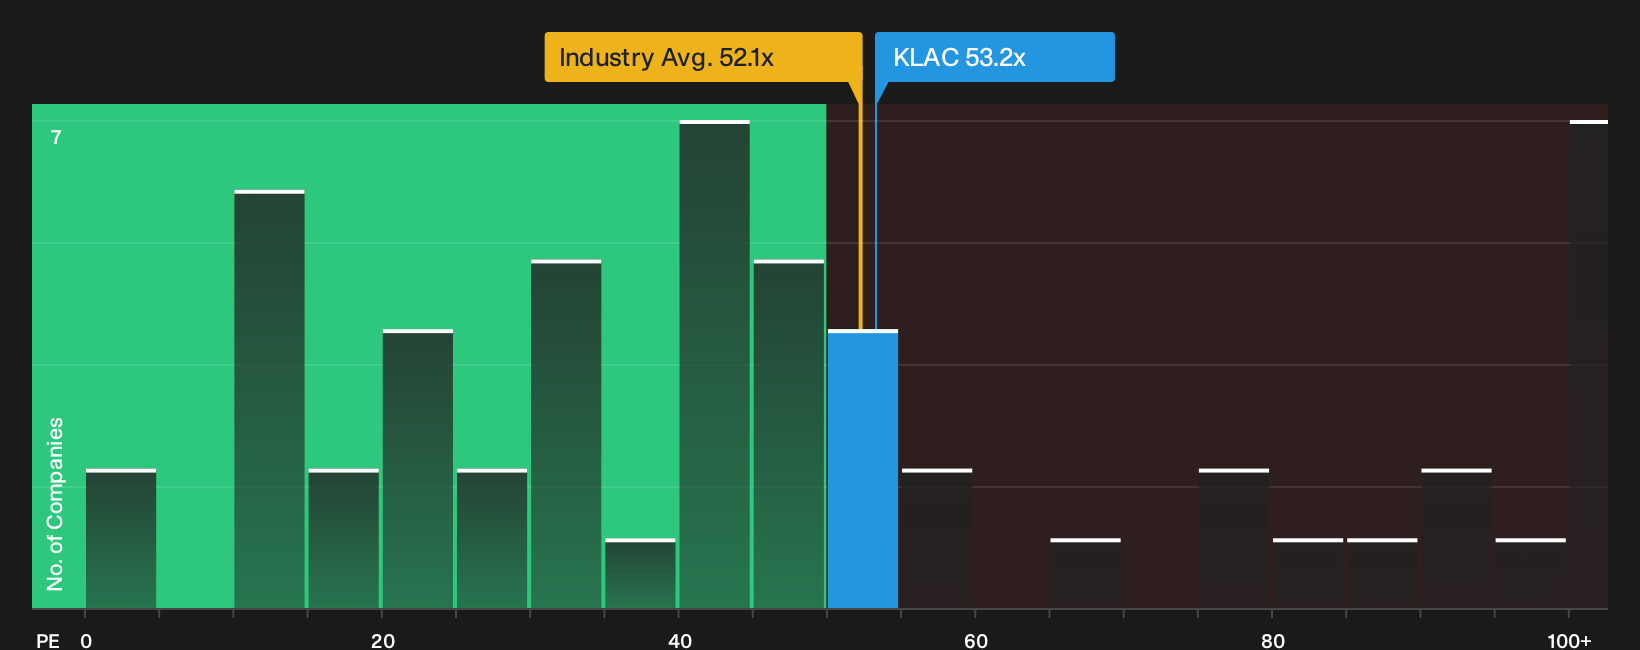
On price multiples, KLA looks far less relaxed than that 16% undervalued fair value would suggest. The current P/E of 53.2x sits above both the US Semiconductor sector at 52.1x and its own fair ratio estimate of 40.6x, which points to less margin for error if sentiment cools.
Put simply, the stock trades richer than peers and above the level our fair ratio indicates the market could move toward. Anyone leaning on the undervalued story needs to decide how comfortable they are paying up for this quality and AI exposure. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on KLA’s valuation story so far. Now move quickly, stress test the numbers yourself, and weigh the 2 key rewards and 1 important warning sign against your own view.
Looking for more ideas beyond KLA?
Do not stop at one ticker when there is a full menu of opportunities. Put KLA in context by stacking it against other potential candidates.
- Target stronger downside protection by scanning a 31 resilient stocks with low risk scores that keeps volatility in check while still focusing on resilient business quality.
- Hunt for possible mispriced opportunities by using a 29 high quality undervalued stocks that blends cash flow strength with balance sheet support.
- Spot potential steady income options through a 8 dividend fortresses that focuses on higher yield payouts with an eye on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com