
Hancock Whitney (HWC) Could Be 94% Undervalued But Its P E Premium Raises Questions
Recent Share Performance and What It May Signal
Hancock Whitney (HWC) has moved lower in the short term, with the share price down about 1% over the past day and roughly 6% over the past month. Over the past 3 months the decline is closer to 4%, which contrasts with a positive year to date return and a higher total return over the past year.
That mix of shorter term weakness and longer term gains gives investors a specific question: Is the market simply cooling after a stronger run, or is it reassessing what Hancock Whitney is worth today based on fundamentals rather than recent momentum?
Recent trading suggests that momentum in Hancock Whitney’s share price is fading in the short term, even as longer term total shareholder returns remain strong. The stock has eased back toward US$71.64, and that softer short term share price return likely reflects investors reassessing growth prospects and risks after a much stronger multi year total shareholder return profile that includes a 17.33% 1 year total shareholder return, a 3 year total shareholder return above 100%, and a 5 year total shareholder return of 70.95%. Taken together, these returns frame today’s pullback as a reset rather than a clean directional signal on valuation.
Compare Hancock Whitney's recent pullback and long term gains with other hand picked financial institutions by scanning the list of solid balance sheet and fundamentals (25 results) that share strong fundamentals and resilient balance sheets.
For Hancock Whitney, a small pullback after strong multi year gains leaves a practical question: Is most of the easy upside already behind the stock, or is the recent step down setting up more room ahead on valuation?
Preferred P/E Multiple for Hancock Whitney: Is It Justified?
Valuation work on Hancock Whitney starts with the P/E tag the market is placing on its earnings. The stock changes hands at a P/E of 13.5x, while peers in the US Banks group are closer to 11x and the broader industry average sits around 11.5x.
The P/E ratio compares the current share price to earnings per share. For a bank like Hancock Whitney, it reflects what investors are willing to pay today for each dollar of profit given its deposit base, lending mix, and fee income. A richer multiple usually signals that the market is pricing in steadier profitability, cleaner asset quality, or a more resilient business model compared with other lenders.
Hancock Whitney trades at a P/E that is higher than both its direct peer set at 11x and the US Banks industry at 11.5x. That gap suggests investors are paying a visible premium for its earnings stream. At the same time, the stock is described as good value when compared with an estimated fair P/E of 13.9x. This implies the current 13.5x level is not stretched against that benchmark and could reasonably converge toward that fair ratio if conditions stay consistent.
Explore the SWS fair ratio for Hancock Whitney.
Result: Price-to-earnings of 13.5x (OVERVALUED)
Still, the premium P/E leaves Hancock Whitney exposed if revenue or net income growth slows, or if broader US banking sector sentiment suddenly weakens.
Find out about the key risks to this Hancock Whitney narrative.
Another View on Hancock Whitney’s Value
The P/E premium presents Hancock Whitney as expensive compared with US bank peers, but the SWS DCF model suggests the opposite. It values the shares at about $139.30 per share, which is well above the recent $71.64 price and presents the stock as undervalued using that approach. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
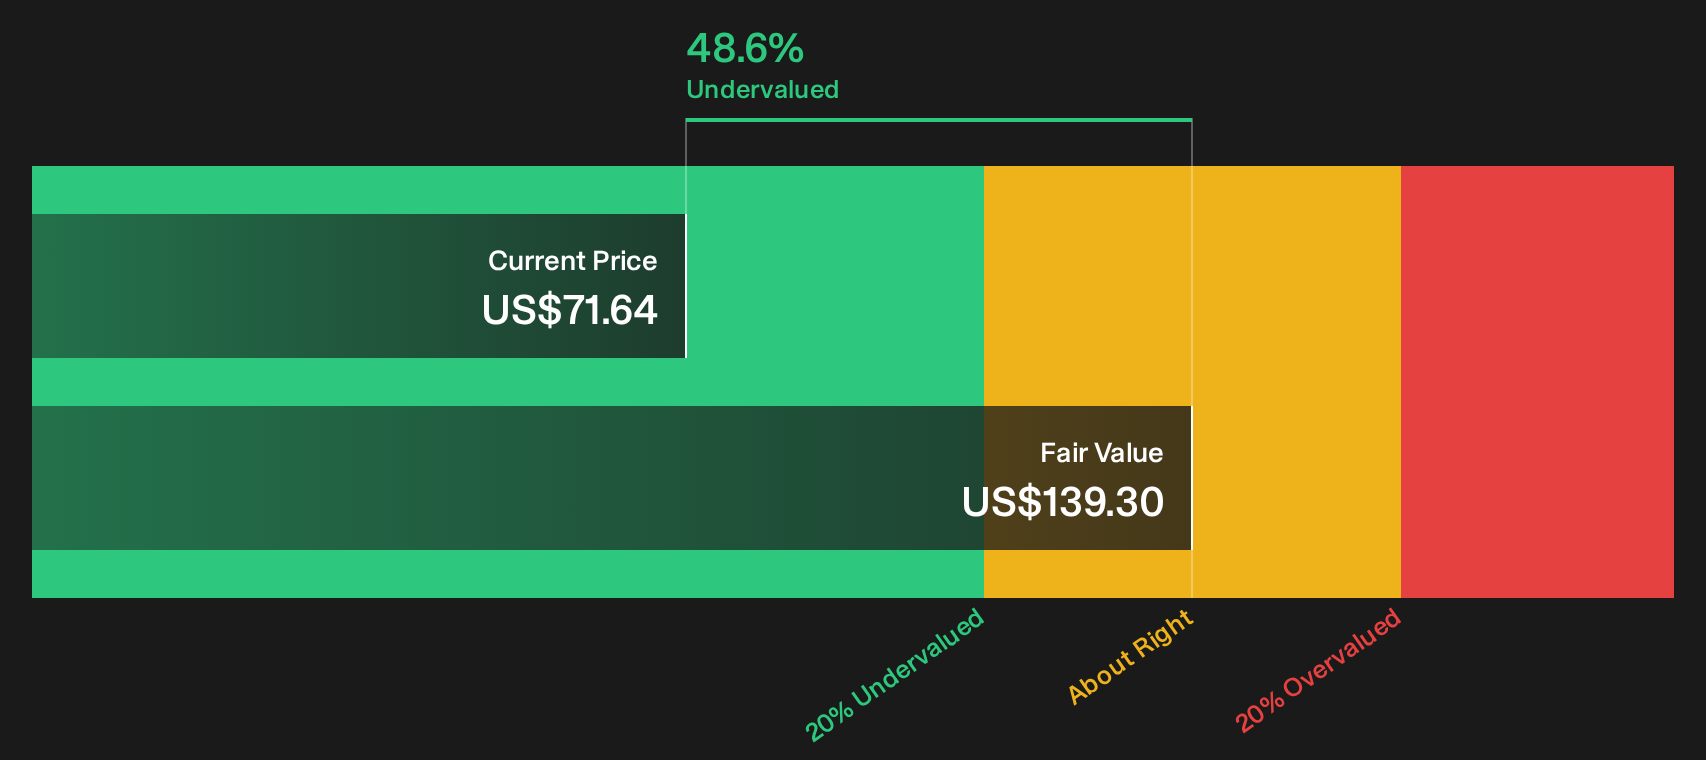
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hancock Whitney for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Hancock Whitney can feel confusing, so it may help to review the underlying data for yourself, then weigh the 3 key rewards and 1 important warning sign.
Ready To Hunt For Your Next Idea Beyond Hancock Whitney?
If Hancock Whitney has your attention, do not stop there. Broader opportunity often sits just outside the obvious choices, and missing it can cost real upside.
- Target resilient businesses first by checking companies on the 31 resilient stocks with low risk scores that pair steadier risk profiles with solid fundamentals.
- Spot potential mispricings early by filtering the market through the 29 high quality undervalued stocks where quality and value intersect more clearly.
- Get ahead of the crowd by reviewing the 20 high quality undiscovered gems before wider attention starts to narrow the opportunity set.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com