
How to Play Rubrik Stock at New All-Time Highs
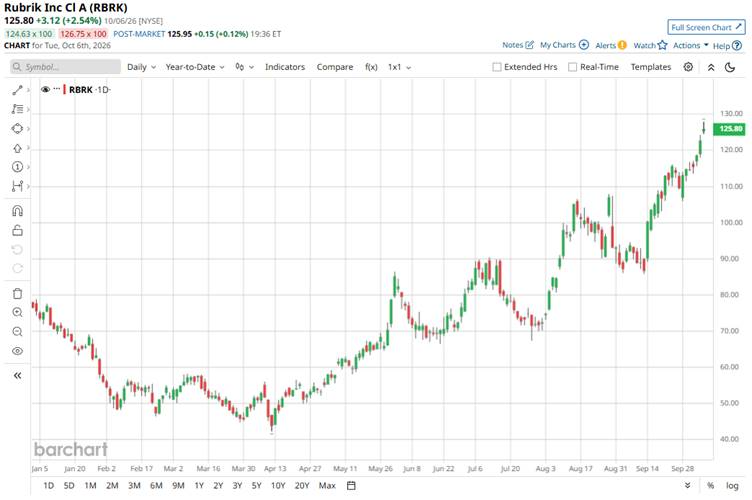
Rubrik (RBRK) is capturing investors’ attention as shares have pushed to a new all-time high of $127.90 on Oct. 6, extending a powerful rally in the cybersecurity stock. Shares have climbed sharply as investors increasingly focus on the growing need to secure data and workloads amid the rapid adoption of artificial intelligence (AI). As businesses accelerate AI adoption and expand their digital infrastructure, protecting sensitive data from increasingly sophisticated cyber threats has become a critical priority.
Rubrik’s focus on data security, cyber resilience, and recovery solutions positions the company to benefit from the two most hyped trends, AI expansion and rising cybersecurity threats. However, with the stock trading at record levels, investors must weigh its growth potential against valuation risks and the possibility of profit-taking following a sharp rally. Can Rubrik sustain its momentum, and is the stock still worth buying at these elevated levels?
About Rubrik Stock
Rubrik is a Palo Alto, California-based cybersecurity and data-resilience company focused on helping organizations protect, manage, and recover critical data. Its Rubrik Security Cloud platform combines data protection, cyber recovery, data security, and threat monitoring, with the company increasingly expanding its capabilities to address the security challenges associated with artificial intelligence. The company went public on the New York Stock Exchange in April 2024 and currently has a market cap of about $25.9 billion.
Rubrik has been one of the strongest performers in cybersecurity in 2026, with shares gaining roughly 64.5% year-to-date (YTD) and 53% over the past year as investors increasingly favor companies positioned to benefit from the AI-driven expansion of cybersecurity spending. The rally has accelerated in recent sessions, with RBRK rising 2.8% on Oct. 2, 3.5% on Oct. 5 and another 2.5% on Oct. 6, bringing its five-day gain to about 9.6%. On Oct. 6, the stock touched a fresh all-time high of $127.90 before closing at $125.80.
The recent momentum reflects a combination of improving fundamentals and enthusiasm around Rubrik’s positioning in AI security and cyber resilience.
Investor sentiment has also benefited from Rubrik’s expansion beyond traditional data backup into agentic AI security, identity resilience, and AI-driven cyber recovery. The company launched Rubrik AI, expanded its Agent Cloud capabilities, and announced a partnership with CrowdStrike Holdings (CRWD) to automate identity-attack detection and recovery. More recently, Rubrik said its AI platform is being used by one-third of its global customers, adding to the narrative that the company could become an important security layer as enterprises deploy autonomous AI agents.
The sharp advance has nevertheless pushed valuation higher, and Rubrik’s ability to sustain its rapid subscription growth and expand margins will likely determine whether the stock can maintain its record-setting trajectory.
The stock is currently trading at a premium compared to industry peers at 18.68 times sales.
Better-than-Expected Q2 Results
Rubrik reported its second-quarter fiscal 2027 results on Aug. 27, for the quarter ended July 31, delivering growth across its key operating metrics and raising its full-year outlook.
Revenue growth remained strong. Total revenue rose 38% year-over-year (YOY) to $427.3 million. Subscription revenue increased 37% to $407.2 million. On a basis normalized for material rights, revenue growth was even stronger at 43% YOY, highlighting the underlying momentum of the subscription business.
Rubrik’s recurring-revenue metrics were particularly encouraging. Subscription ARR increased 33% to $1.7 billion, while net new Subscription ARR increased 35% YOY. Cloud ARR climbed 39% to $1.5 billion, and adjusted net new Cloud ARR increased 20% YOY during the quarter. The company also ended the period with 3,084 customers generating at least $100,000 in Subscription ARR, up 23% from a year earlier.
Moreover, on an adjusted basis, Rubrik swung to non-GAAP EPS of $0.20 from a loss of $0.03 a year earlier and topped the consensus estimate. Subscription ARR contribution margin expanded substantially to 14% from 9.4%, signaling improving operating leverage. However, gross margins declined slightly, with non-GAAP gross margin at 81.0% versus 81.6%.
Cash generation was another positive. Operating cash flow increased to $76.8 million from $64.7 million, while free cash flow rose to $65.7 million from $57.5 million. Rubrik finished July with $1.8 billion in cash, cash equivalents, and short-term investments, providing substantial financial flexibility as it continues investing in AI and cybersecurity capabilities.
Meanwhile, for the third quarter, Rubrik expects revenue of $429 million to $431 million, non-GAAP Subscription ARR contribution margin of approximately 14%, and non-GAAP EPS of $0.07 to $0.09. For the full fiscal year, the company now expects Subscription ARR of $1.88 billion to $1.885 billion, revenue of $1.685 billion to $1.693 billion, non-GAAP EPS of $0.47 to $0.53, and free cash flow of $323 million to $333 million.
Analysts predict loss per share to be around $1.19 for fiscal 2027, an improvement of around 29.6% YOY, and again improve by 26.9% annually to $0.87 in fiscal 2028.
What Do Analysts Expect for Rubrik Stock?
On Sept. 23, Baird maintained its “Outperform” rating on Rubrik and raised its price target to $139 from $130. Baird’s bullish view centers on Rubrik’s positioning in cybersecurity and data resilience as enterprises increasingly adopt AI and agentic AI systems.
In the same month, Wedbush initiated coverage of Rubrik with an “Outperform” rating and a $120 price target, while adding the stock to its “Best Ideas List.”
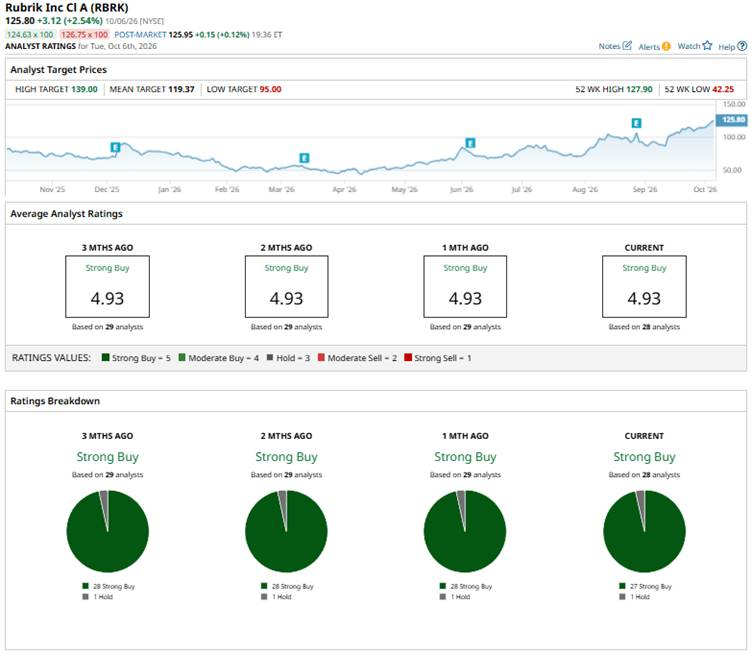
Wall Street remains bullish on RBRK with an overall consensus “Strong Buy” rating. Of the 28 analysts covering the stock, 27 advise a “Strong Buy,” and one recommends a “Hold” rating.
While the stock has already surged past the average analyst price target of $119.37, the Street-high target price of $139 suggests that the stock could further rise by 10.5%.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.