
Vylor (VYLR) Could Be 14% Below Fair Value As Governance Reset Begins
Vylor (VYLR) has just overhauled its governance framework, with a fully amended certificate of incorporation and bylaws adopted ahead of the October 1, 2026 effectiveness date. This provides investors with fresh context for assessing the recently listed stock.
Vylor has had a choppy debut period, with the share price down 16.9% over the past 30 days and 13.0% over 90 days, yet still showing a 7.7% year to date share price gain and a 39.3% one year total shareholder return. This may hint that recent index reshuffling and capital markets activity are prompting investors to reassess both its risk profile and longer term potential.
Scan how Vylor’s governance reset compares with other potential opportunities by checking companies on the 20 high quality undiscovered gems that may still be flying under the radar.
After a rough first month and with a governance overhaul in motion, Vylor now trades around $72.99 with an implied discount to some valuation estimates. Does that recent stumble still leave the risk reward tilted toward buyers, or not?
Most Popular Narrative: 14% Undervalued
Against Vylor’s last close of $72.99, the most widely followed narrative pegs fair value at $85, which implies a discount that hinges on how the royalty heavy genetics platform plays out over time.
The long dated licensing targets of over US$0.5b in 2027 and up to US$2b by 2040, against a roughly US$4b Americas corn and soy licensing market, create scope for Vylor to compound an asset light revenue stream that can support higher free cash flow conversion than current expectations assume.
See why 1 investors see Vylor as 14% undervalued.
Result: Fair Value of $85 (UNDERVALUED)
Still, Vylor’s bullish script unravels quickly if royalty income ramps more slowly than hoped, or if investors refuse to pay a premium P/E multiple.
Find out about the key risks to this Vylor narrative.
Another View: Vylor Looks Expensive On Earnings
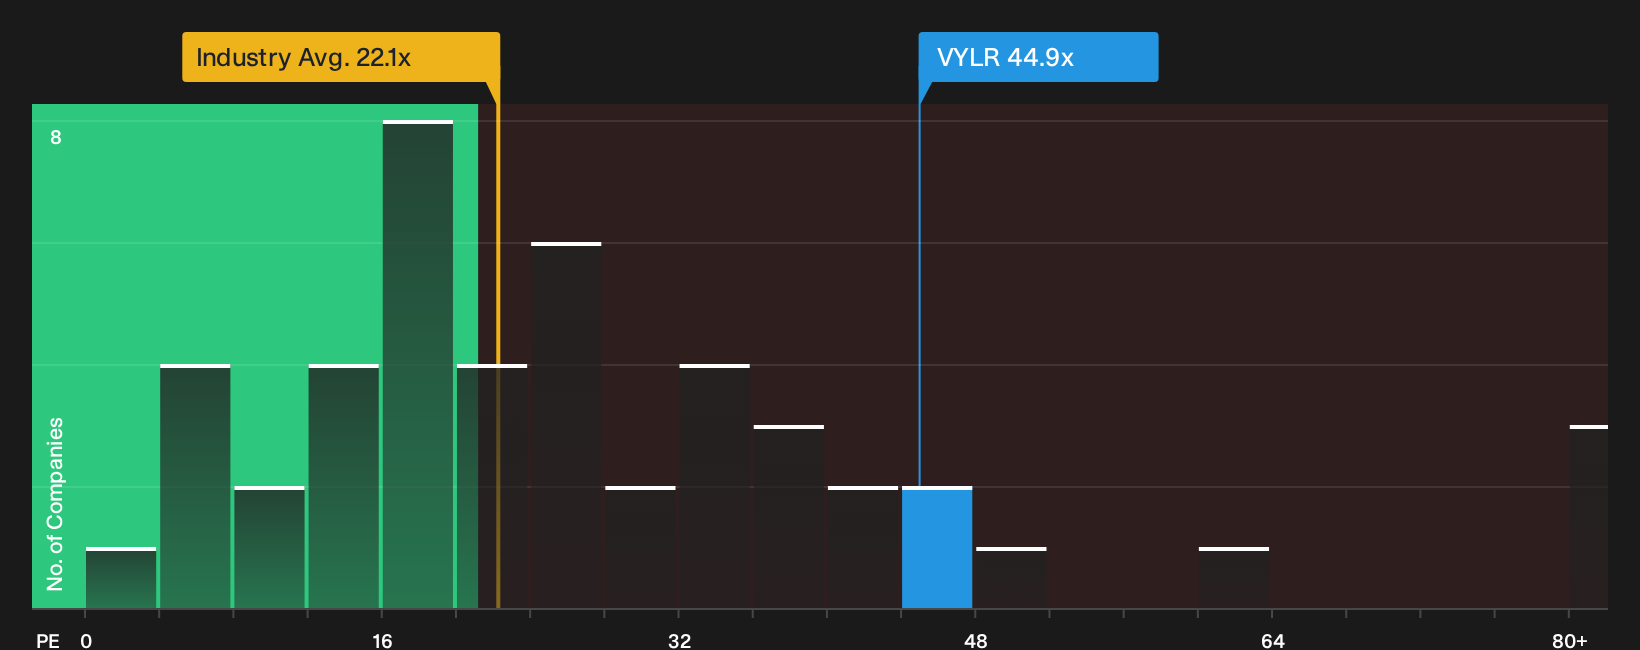
There is a catch. On a plain P/E lens, Vylor trades at about 44.9x earnings, which is roughly double both the US Chemicals industry on 22.4x and the peer average on 14.1x, and also well above a fair ratio of 22.8x that the market could eventually lean toward.
If sentiment shifts away from premium multiples, that gap gives you valuation risk on the downside as much as potential reward if the current pricing holds or stretches further. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Vylor’s valuation and governance reset can create pressure to act fast, yet this is exactly when closer inspection helps most. Before you rush to any conclusion, weigh both the potential upsides and the red flags by checking the 2 key rewards and 1 important warning sign.
Looking for more Vylor sized ideas?
If Vylor has sharpened your focus on pricing, risk and potential, broaden that edge by scanning other opportunities that might fit your style before the crowd does.
- Target better value by lining up companies that combine quality and attractive pricing with the 29 high quality undervalued stocks.
- Build a sturdier core by focusing on payouts that work harder for you with the 8 dividend fortresses.
- Dial down stress by filtering for businesses with stronger finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com