
Missed Ashmore Group's Rally? Here Is What Holders Saw
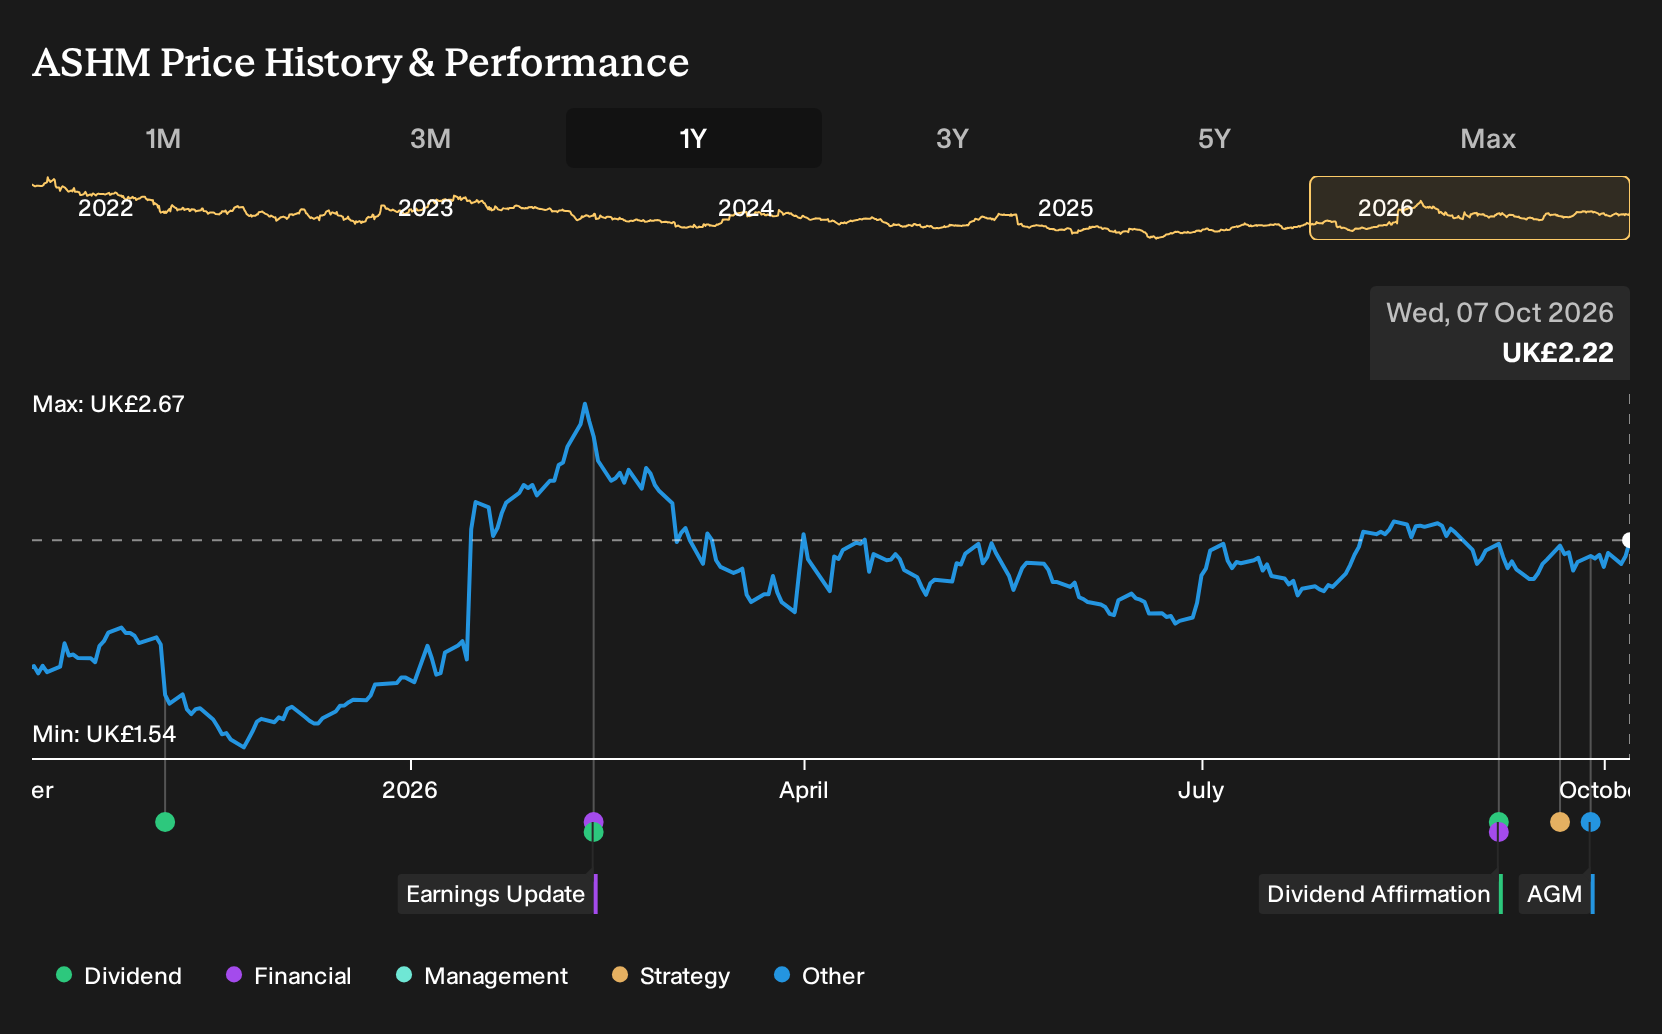
If you had glanced at Ashmore Group in October 2025, you would have seen a specialist in emerging markets facing fee pressure, profit margin questions, and sharply different analyst fair values. For Ashmore Group shareholders, the return over the past year was 36.0%, including dividends. If you had bought then, you would now be weighing that gain against fresh results where revenue and net income moved in different directions, and asking which signal mattered more at the start.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Ashmore Group. Zero in on 8 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Ashmore Group
The shares cost £1.8 at the start of the period, and anyone looking at Ashmore Group then was really choosing between two grounded stories rather than a single obvious read.
The bullish narrative pointed to a fair value of £2.4. Supporters expected revenue to grow 8.3% a year and were comfortable with profit margins shrinking from 57.0% to 36.3% as the business focused on higher fee emerging market strategies.
The more cautious view anchored on a fair value of £1.56. That side assumed revenue would decline 4.8% annually, with profit margins moving from 50.2% to 41.1% as fee pressure and market volatility weighed on earnings.
What The Results Tested For Ashmore Group
The clearest datapoint for Ashmore Group was the split between revenue and profit. Total revenue moved from £64.9m in H2 2025 to £71.8m in H2 2026, while net income slipped from £44.1m to £33.9m and net margin fell from 68.0% to 47.2%. That mix of higher sales and weaker profitability cut both ways for the bullish and cautious stories.
The hinge assumption here was margin resilience. When you assess another asset manager, track whether net margin moves in the same direction as revenue, and judge any growth claim against that pairing.
What Today's Ashmore Group Price Already Assumes
Ashmore Group now trades at £2.22, with this Narrative’s Fair Value sitting below that quote rather than above it. The gap reflects concerns that the share price already builds in a meaningful recovery in earnings power.
The Narrative asks you to focus on fee pressure, seed capital swings, and whether higher margin local offices can keep offsetting those headwinds. A buyer at today’s price has to judge that these local platforms keep growing fast enough for their richer fee mix to balance ongoing pressure on group management fee margins.
"Equities and alternatives now represent a larger share of Ashmore Group assets and carry higher average fee rates. However, continued industry fee pressure and the guided 1 basis point erosion in group management fee margin every 12 to 24 months imply that future product mix shifts may not fully offset pricing compression, which would weigh on net revenue and earnings."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Looking Beyond Ashmore Group
Ashmore Group operates in capital, mandates, and allocation choices. Your money shifts on screens before it reaches those funds.
Those flows depend on a global network that moves payments between banks, shops, and governments. It processes digital transactions without taking on consumer lending risk.
Instead of holding credit exposure, this business collects a fee whenever money moves electronically. Once those payment pipes exist, each extra transaction adds limited additional cost.
As more spending transitions away from cash, that toll-road model stands out. You decide whether owning allocators like Ashmore Group is enough, or whether the underlying payment rails deserve more attention.
One Narrative has already put a figure on it. → Uncover the company trading 13% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com