
Magnite (MGNI) Could Be 15% Undervalued After Debt Repricing Lowers Interest Costs
Magnite (MGNI) is back in focus after repricing its $358 million senior secured term loan and $175 million revolving credit facility, cutting interest margins and freeing up cash that would otherwise go to lenders.
For investors watching Magnite, the repricing news lands on top of a strong run, with the share price at US$25.24 and a year to date share price return of 57.16% alongside a 90 day share price return of 18.94%. The 1 year total shareholder return of 32.25% and 3 year total shareholder return of about 3.4x suggest longer term holders have already seen meaningful gains, and recent contract wins and lower debt costs are likely shaping how the market prices both its growth potential and risk profile.
Spot opportunities alongside Magnite by scouting 20 high quality undiscovered gems that share strong fundamentals yet still fly under most investors' radar.Magnite now trades about 9% below one estimate of intrinsic value and roughly 18% under the average analyst target after this rally. Is that a genuine discount, or is the market pricing in real execution risk?
Most Popular Narrative: 15% Undervalued
On the most followed view, Magnite screens as modestly undervalued, with a fair value estimate of $29.67 against the recent $25.24 close. This puts the focus firmly on whether the business can earn into that gap over time.
Analysts are assuming Magnite's revenue will grow by 7.7% annually over the next 3 years.
Analysts assume that profit margins will shrink from 22.5% today to 14.7% in 3 years time.
See why 12 investors see Magnite as 15% undervalued.
Result: Fair Value of $29.67 (UNDERVALUED)
Still, the Magnite story can break if big CTV partners shift spend in house or if expected benefits from Google AdTech remedies arrive more slowly than analysts model.
Find out about the key risks to this Magnite narrative.
Another View: What Magnite’s P/E Is Telling You
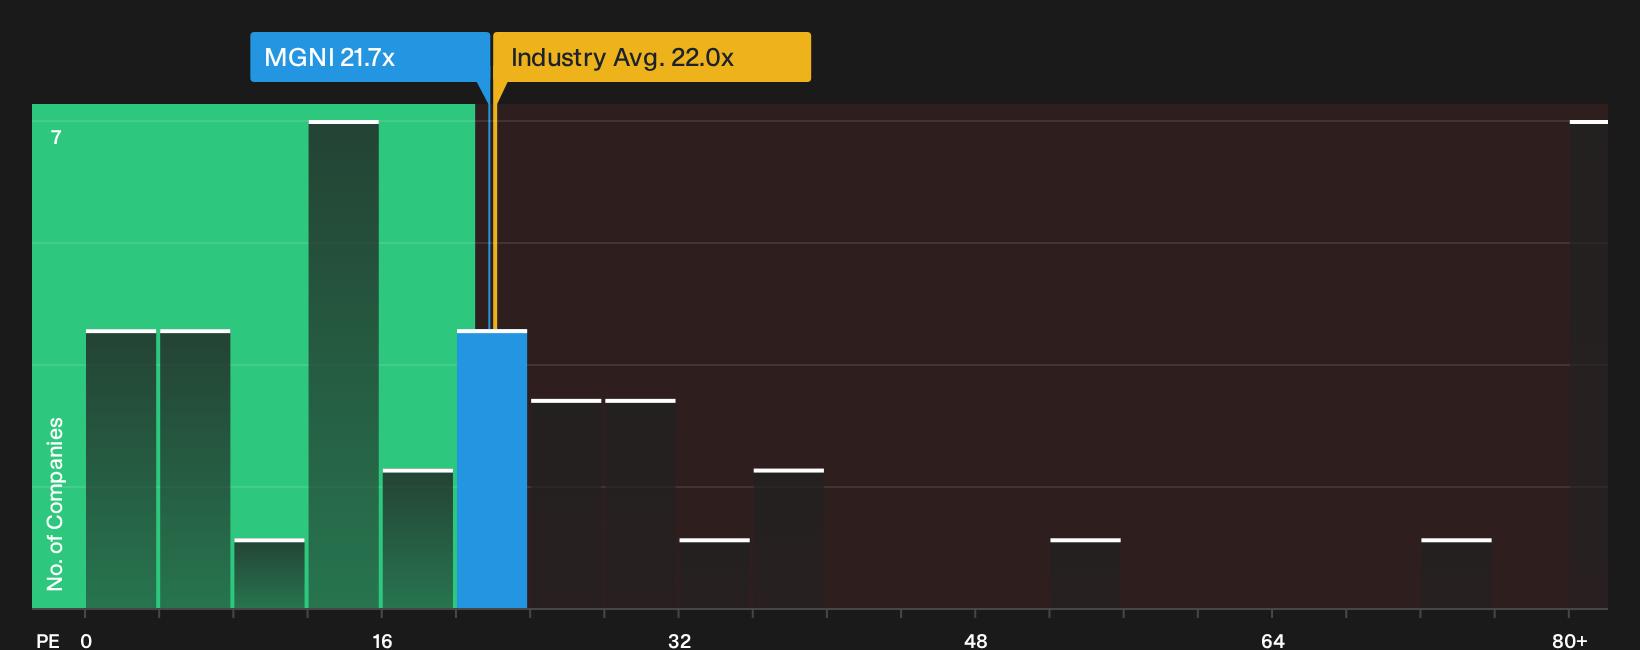
There is a catch. On simple earnings multiples, Magnite does not look obviously cheap. The stock trades on a P/E of 21.7x, slightly above the US Media industry at 21.3x and well ahead of a fair ratio estimate of 13.9x. This points to real valuation risk if expectations cool.
That gap means investors are already paying up versus what the fair ratio suggests the market could move toward over time, while peers on average sit far higher at 63.8x. Is this a premium you are comfortable underwriting, or a signal to demand a wider margin of safety before committing fresh capital?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Bullish or cautious after all this Magnite discussion? The fastest way to cut through the noise is to inspect the full data yourself and weigh both sides. To see how optimism around future upside stacks up against the concerns investors are flagging, start with the 2 key rewards and 1 important warning sign.
Want more ideas beyond Magnite?
If Magnite has your attention, do not stop with a single stock story. Broadening your watchlist can help you compare quality, risk and income potential side by side.
- Target resilient compounding potential by scanning a 29 high quality undervalued stocks that combines solid financials with prices that still look compressed against fundamentals.
- Prioritise strength and staying power by reviewing a list of solid balance sheet and fundamentals (25 results) where healthier funding and liquidity support steadier business performance.
- Build a cash flow stream by focusing on a 8 dividend fortresses that aims to pair meaningful yields with businesses that can keep those payouts funded.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com