
Accelerant Holdings (ARX) Stock Looks Priced At A Premium To Sales
Accelerant Holdings has seen its share price climb over the past year, which puts a spotlight squarely on what investors are paying for each dollar of its sales. With the stock now changing hands at US$19.75, the question is whether that tag is supported by the insurer's current revenue base.
- The stock is up 31.8% over the past year. Anyone looking at Accelerant Holdings today is effectively asking if that share price move lines up with its sales power.
- The business leans heavily on how efficiently it turns written premiums into sustainable revenue, which can shape how much investors are prepared to pay relative to its sales line.
- The analysts covering Accelerant Holdings have run their own numbers. See what analysts think Accelerant Holdings's shares could be worth.
The stock's next move may depend on whether Accelerant Holdings' recent price can be squared with the sales it currently generates.
If you are weighing whether Accelerant Holdings' 31.8% one year return lines up with what investors pay for each dollar of revenue, it can help to compare that question across 29 high quality undervalued stocks.
Is Accelerant Holdings Getting Expensive on Sales?
P/S fits Accelerant Holdings because investors often look at revenue capacity first for insurers that are still working toward consistent earnings.
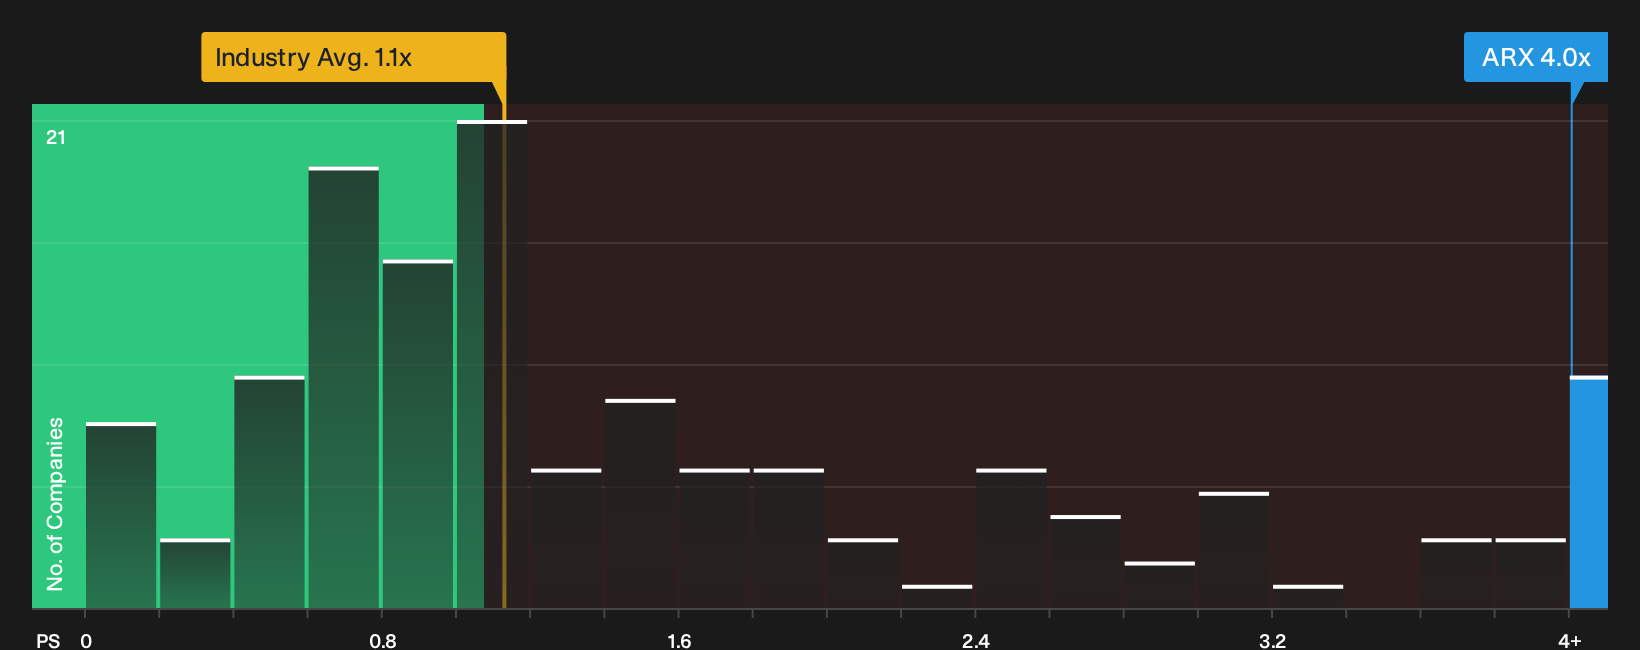
On this lens, the stock trades around 4.0x P/S, compared with an Insurance industry average near 1.1x and a peer group closer to 6.3x. That leaves Accelerant Holdings priced well above the broad sector on sales, although it does not reach the richer levels seen across similar peers.
The Fair Ratio model, which blends factors like profitability profile, risk and sector context, points to a lower multiple than the one the shares currently carry. That gap means the current 4.0x P/S screens as overvalued on this framework, so anyone buying at today’s tag is paying a premium for each dollar of revenue relative to what this model suggests. Explore the numbers behind Accelerant Holdings's P/S valuation.
The Accelerant Holdings Narrative: What Would Justify Today's Price?
Narratives for Accelerant Holdings pick up where the P/S puzzle leaves off by spelling out what kind of revenue trajectory, margin profile and earnings power would need to show up for the current share price to look materially higher or lower in hindsight. Rather than relying on a single multiple or model point, each narrative lays out the specific assumptions behind its fair value view so you can weigh those against Accelerant Holdings' actual results as they arrive, all within Simply Wall St's Community page.
One of the top community narratives on Accelerant Holdings: roughly fairly valued
"Greater use of third party insurers, with a medium term aim for roughly two thirds of the portfolio, reduces reliance on Accelerant’s own balance sheet…"
Discover why this Narrative puts Accelerant Holdings at roughly fairly valued.
One more angle on Accelerant Holdings that could change how you see the stock
Price to sales and community narratives tell you what the market is paying today, and professional coverage adds another lens on where this insurer might be a few years from now. Explore where analysts expect Accelerant Holdings to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com