
PTC Therapeutics (PTCT), What Is Behind The Latest Attention?
PTC Therapeutics (PTCT) has drawn fresh attention after recent trading left the share price at $63.23, with returns down over the past week, month, and past 3 months. Investors now weigh rare-disease exposure against ongoing losses.
Recent trading has followed a steady loss of momentum for PTC Therapeutics, with the 30 day share price return down 8.76% and the 90 day move weaker. However, the 3 year total shareholder return of around 185% still paints a very different long run story.
Scan how PTC Therapeutics compares with other rare-disease and healthcare players by reviewing the hand-picked 35 healthcare AI stocks that could be preparing for their next big move.
PTC Therapeutics now trades at a steep discount to analyst targets and estimated fair value, even as it carries ongoing losses and recent share price weakness. Is that a bargain on rare-disease assets, or justified caution on the risks ahead?
Most Popular Narrative: 38% Undervalued
Against a last close of $63.23 and a narrative fair value of about $101.29, the gap around PTC Therapeutics centers on how durable its rare-disease engine can be.
The company's ongoing launch strategy for Sephience includes early patient and payer engagement, swift access programs, and leveraging established commercial infrastructure across multiple developed and emerging markets (U.S., EU, Japan, Brazil, LATAM), all occurring within a period of expanding reimbursement and growing healthcare coverage for high-impact rare disease treatments. This is enabling accelerated topline growth and sustained operating leverage.
See why 5 investors see PTC Therapeutics as 38% undervalued.
Result: Fair Value of $101.29 (UNDERVALUED)
Still, the bullish view on PTC Therapeutics hinges on a narrow product set and continued losses, so any Sephience setback or Translarna disruption could quickly unwind it.
Find out about the key risks to this PTC Therapeutics narrative.
Another View on PTC Therapeutics Valuation
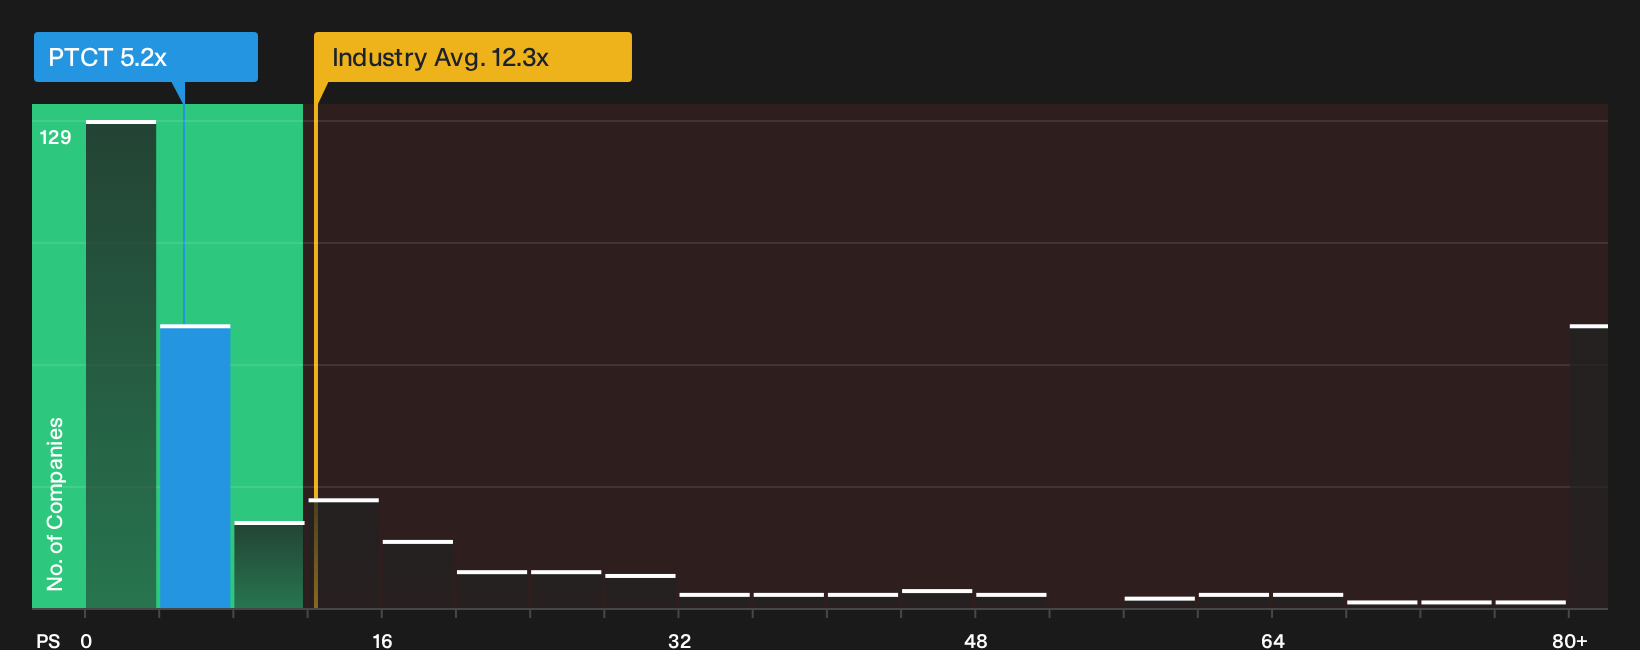
The first story on PTC Therapeutics leans heavily on future cash flows and analyst targets. A different lens uses the current P/S ratio of 5.2x against a fair ratio of 4.9x and an industry level of 12.1x, as well as a peer average of 6.2x. That mix points to a stock that screens cheap versus biotech rivals yet slightly rich versus its own fair ratio. This raises a straightforward question: is the bigger risk overpaying a little now, or missing a potential rerating if sentiment shifts toward rare-disease platforms?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around PTC Therapeutics can be confusing. Check the numbers, weigh both the risk flags and potential upsides, then review the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond PTC Therapeutics?
Before you move on, put this research to work by lining up a few fresh ideas through the Simply Wall Street Screener so you are not relying on a single story.
- Target resilience first and check out companies on our 31 resilient stocks with low risk scores that aim to pair steadier risk profiles with room for upside.
- Hunt for quality at a discount by reviewing the 29 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect them.
- Prioritize balance sheet strength and scan the list of solid balance sheet and fundamentals (25 results) to focus on businesses with financial foundations built to handle shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com