
Walker & Dunlop (WD) Shares Dropped, So What Is Behind The Move?
Walker & Dunlop (WD) has been in the spotlight after arranging more than US$630.6m in fixed-rate financing for nine multifamily properties across six states, plus a separate US$86.5m bridge loan in Virginia.
Despite arranging large financings across multifamily assets, Walker & Dunlop’s share price has retreated sharply, with the 30-day share price return down 20.3% and the year-to-date share price return down 42.17%, while the 1-year total shareholder return has fallen 54.85%. This suggests momentum has been fading even as deal activity and management changes keep investor attention high.
Capitalize on the recent pressure in Walker & Dunlop by scanning a hand-picked 29 high quality undervalued stocks that share solid fundamentals with discounted market expectations.Walker & Dunlop now trades far below where it started the year, even as it remains active in arranging large multifamily financings. Is most of the repricing already done, or is the gap to fair value still wide?
Most Popular Narrative: 40.4% Undervalued
Walker & Dunlop’s most followed narrative anchors fair value at $57, well above the last close of $33.96. This frames the current selloff as a sizeable discount that requires strong execution to close.
Ongoing refinancing and construction activity in a higher rate setting, including recent large multifamily, mixed use, office and workforce housing deals in Miami, Manhattan, Jersey City and other markets, keeps Walker & Dunlop well positioned to generate fee income from a sustained recapitalization cycle that can support revenue and earnings.
See why 1 investors see Walker & Dunlop as 40% undervalued.
Result: Fair Value of $57 (UNDERVALUED)
Still, the Walker & Dunlop narrative can break if higher interest costs keep pressuring financing volumes or if competitive hiring pulls away key originators.
Find out about the key risks to this Walker & Dunlop narrative.
Another View: What Multiples Say About Walker & Dunlop
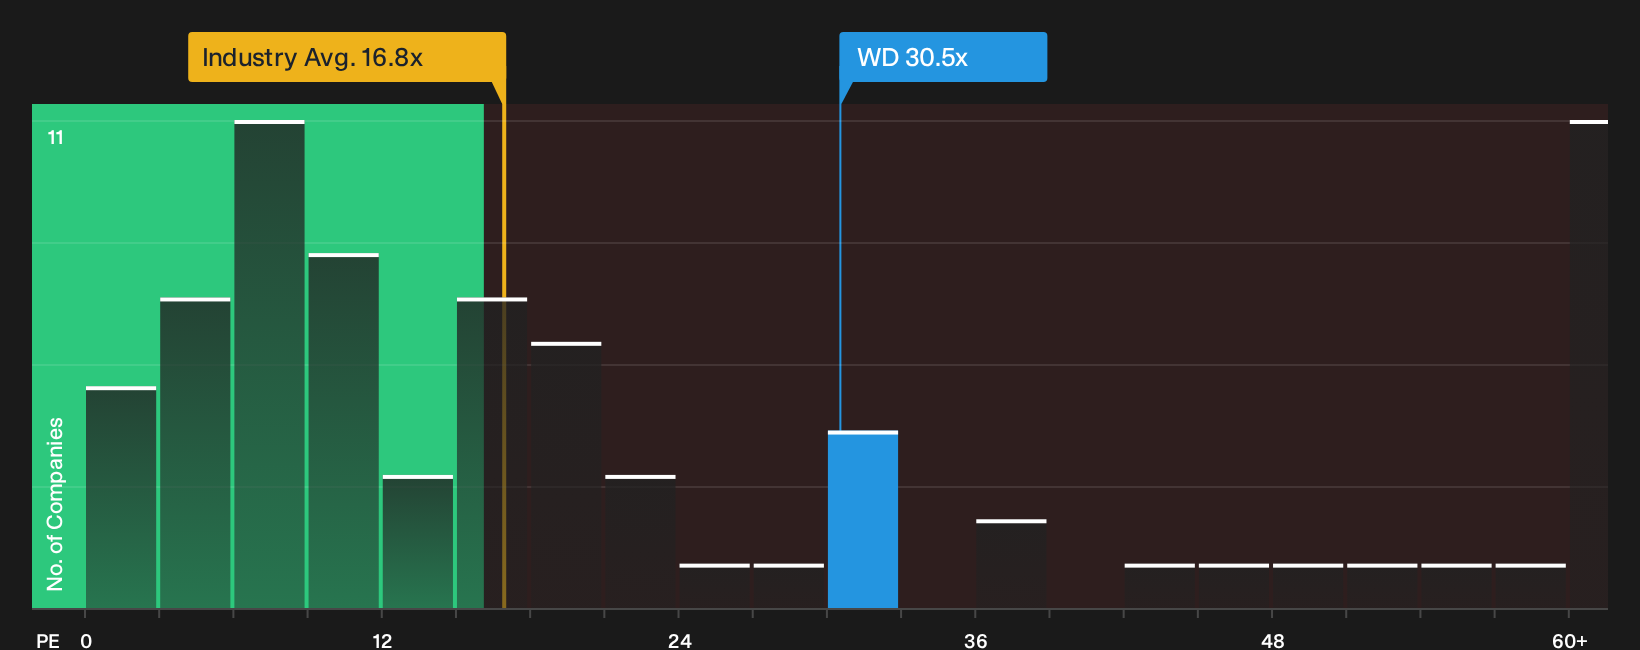
That $57 fair value anchors on future earnings power. A simple P/E check paints a very different picture. Walker & Dunlop trades on 30.5x earnings, while the US Diversified Financial industry sits at 16.9x, its peer group at 9.2x and the fair ratio at 17.7x. That is a steep premium. If the share price moved closer to the fair ratio, recent buyers could face more downside before any upside case plays out. How comfortable are you paying growth pricing when the broader market is assigning much cheaper tags to similar businesses?
See what the numbers say about this price in our valuation breakdown, then decide which story you trust more: the optimistic narrative or the current earnings multiple. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Walker & Dunlop is clearly split. This is exactly why you should move quickly, pull up the full data set, and weigh both sides for yourself using our breakdown of 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Walker & Dunlop?
If Walker & Dunlop has your attention, do not stop here. The smartest moves often come from comparing several strong candidates side by side.
- Target resilient balance sheets that can handle shocks by scanning a focused list of solid balance sheet and fundamentals (25 results) built around financial strength and staying power.
- Hunt for quality trading below what the market is pricing in by working through a curated 29 high quality undervalued stocks with fundamentals front and center.
- Zero in on companies that many investors overlook by reviewing a tightly filtered 20 high quality undiscovered gems that pairs solid metrics with limited attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com