
Is Old Second Bancorp (OSBC) Undervalued Or Is Its Recent Rally Already Priced In?
Old Second Bancorp (OSBC) has drawn fresh attention after its recent close at $24.66, prompting investors to reassess the regional lender’s valuation, return profile, and fundamentals in the current banking sector backdrop.
Recent trading has been choppy for Old Second Bancorp, with the share price slipping 1.6% over the last session and down 4.1% over 30 days. However, the 90-day share price return of 7.9% and year-to-date gain of 26.6% point to momentum that has been strong over a longer stretch, supported by a 1-year total shareholder return of 44.7% and 3-year total shareholder return of 86.3% that keep the longer term picture firmly in positive territory.
Scan how Old Second Bancorp compares with other regionals showing firm balance sheets and earnings power by reviewing our hand picked list of solid balance sheet and fundamentals (25 results) today.
The sharp year-to-date climb along with a recent pullback leaves Old Second Bancorp at an interesting crossroads. Is the price now echoing business progress, or just catching a sentiment swing as investors re-rate regional banks?
Preferred P/E of 13.6x: Is It Justified for Old Second Bancorp?
Valuation checks flag Old Second Bancorp as fully priced on earnings against its peers, even though the shares screen as cheap relative to one DCF based fair value estimate.
The preferred yardstick here is the P/E ratio. OSBC trades on 13.6x earnings, which is slightly above both the estimated fair P/E of 12.2x and a peer average of 13.5x. That places the stock on a premium multiple despite the separate indication that the share price is trading 51.4% below one fair value estimate based on projected cash flows.
P/E simply compares what investors pay for each dollar of profit. For banks such as Old Second Bancorp, this often reflects the market view on the durability of earnings, the quality of the loan book, and the outlook for returns on equity. A higher P/E usually implies investors are willing to pay more today because they are comfortable with the earnings profile.
On that basis, OSBC looks slightly expensive on headline earnings. The 13.6x P/E is above the US Banks industry average of 11.5x and above the 12.2x level that one fair value model suggests the multiple could trend toward. That price tag implies the market is already assigning a premium relative to many regional lenders.
Explore the SWS fair ratio for Old Second Bancorp.
Result: Price-to-Earnings of 13.6x (OVERVALUED)
Still, any stumble in Old Second Bancorp’s loan book quality, or a shift in regional credit conditions, could quickly challenge that premium P/E story.
Find out about the key risks to this Old Second Bancorp narrative.
Another View: Our DCF Model Sees Old Second Bancorp Very Differently
The P/E math presents Old Second Bancorp as expensive, yet the SWS DCF model suggests the opposite. On that framework, OSBC at $24.66 sits about 51.4% below an estimated future cash flow value of $50.76, which presents the same stock as heavily undervalued instead.
Both methods are examining the same bank through different lenses, so the key question for investors is which lens feels more reliable for Old Second Bancorp right now.
Look into how the SWS DCF model arrives at its fair value.
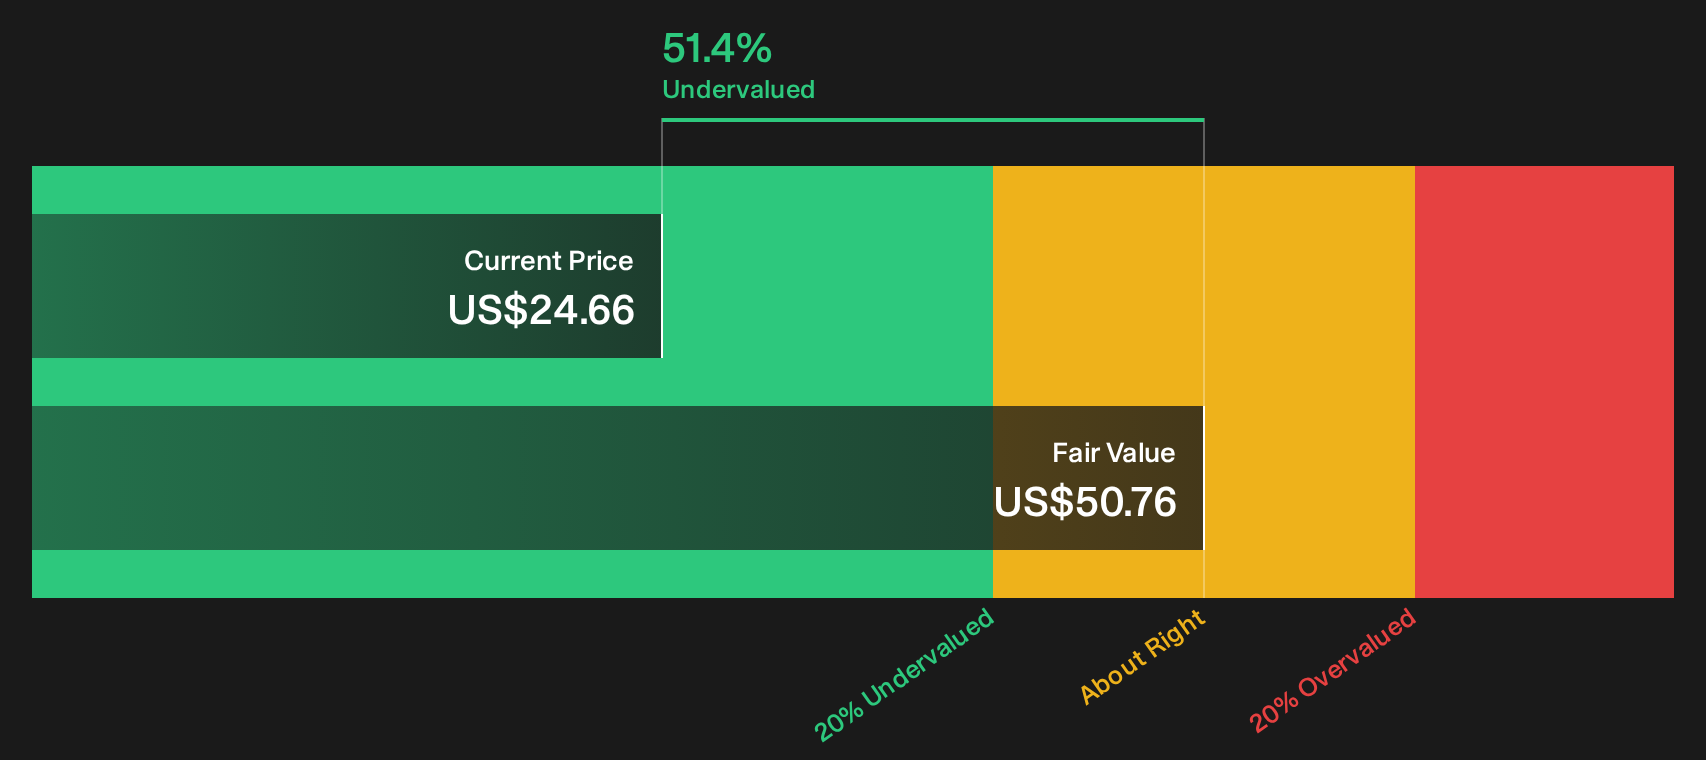
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Old Second Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Old Second Bancorp’s valuation and fundamentals can be confusing, so consider reviewing the data while it is current and weigh both sides for yourself with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Old Second Bancorp?
Do not stop your research with Old Second Bancorp. Broaden your watchlist with fresh ideas that match your risk comfort and income goals while the market keeps moving.
- Target potential mispricing by scanning a curated mix of quality companies trading below estimated value using the 29 high quality undervalued stocks.
- Build a steadier income stream by checking out dividend payers filtered for higher yields and resilience using the 8 dividend fortresses.
- Reduce portfolio stress by focusing on financially robust businesses with strong balance sheets using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com