
Is Arcosa (ACA) Fully Valued As Its Fixed Income Call Tests The Balance Sheet Story?
Arcosa (ACA) is back in focus ahead of its fixed income call on October 7, 2026, drawing attention to how this infrastructure supplier’s balance sheet and financing choices intersect with the current equity story.
Recent trading has been calmer, yet the broader move has been strong. At a latest share price of US$146.40, Arcosa’s year to date share price return of 37.09% and 1 year total shareholder return of 57.95% point to building momentum rather than a short-lived spike. This backdrop gives extra weight to any balance sheet signals that emerge from the October 7 fixed income call.
Scan other infrastructure suppliers showing similar momentum by reviewing our curated 43 power grid technology and infrastructure stocks alongside Arcosa ahead of the October 7 fixed income call.
Arcosa now trades almost in line with analyst targets after a steep run, and only at a slight discount to one fair value estimate. Is that restraint misplaced optimism, or measured caution about what comes next for the stock?
Most Popular Narrative: Fairly Valued
At a last close of $146.40 against a narrative fair value of about $146.67, Arcosa is being priced almost exactly in line with what the most followed view considers reasonable. This puts extra emphasis on how future execution matches those embedded expectations.
The ongoing shift toward sustainability, electrification and climate resilient infrastructure continues to favor Arcosa’s pivot toward Construction Products and Engineered Structures. This sharper focus, combined with the CRH cash offer at about 11.5x guided 2026 adjusted EBITDA including synergies, supports the view that future revenue and margin potential is already reflected in a fuller valuation.
See why 3 investors see Arcosa as 0% undervalued.
Result: Fair Value of $146.67 (ABOUT RIGHT)
Still, Arcosa’s reliance on public infrastructure funding and the earnings hit from the recent 9.54% revenue and 59.75% net profit declines could upset that fair value narrative.
Find out about the key risks to this Arcosa narrative.
Another View on Arcosa’s Valuation
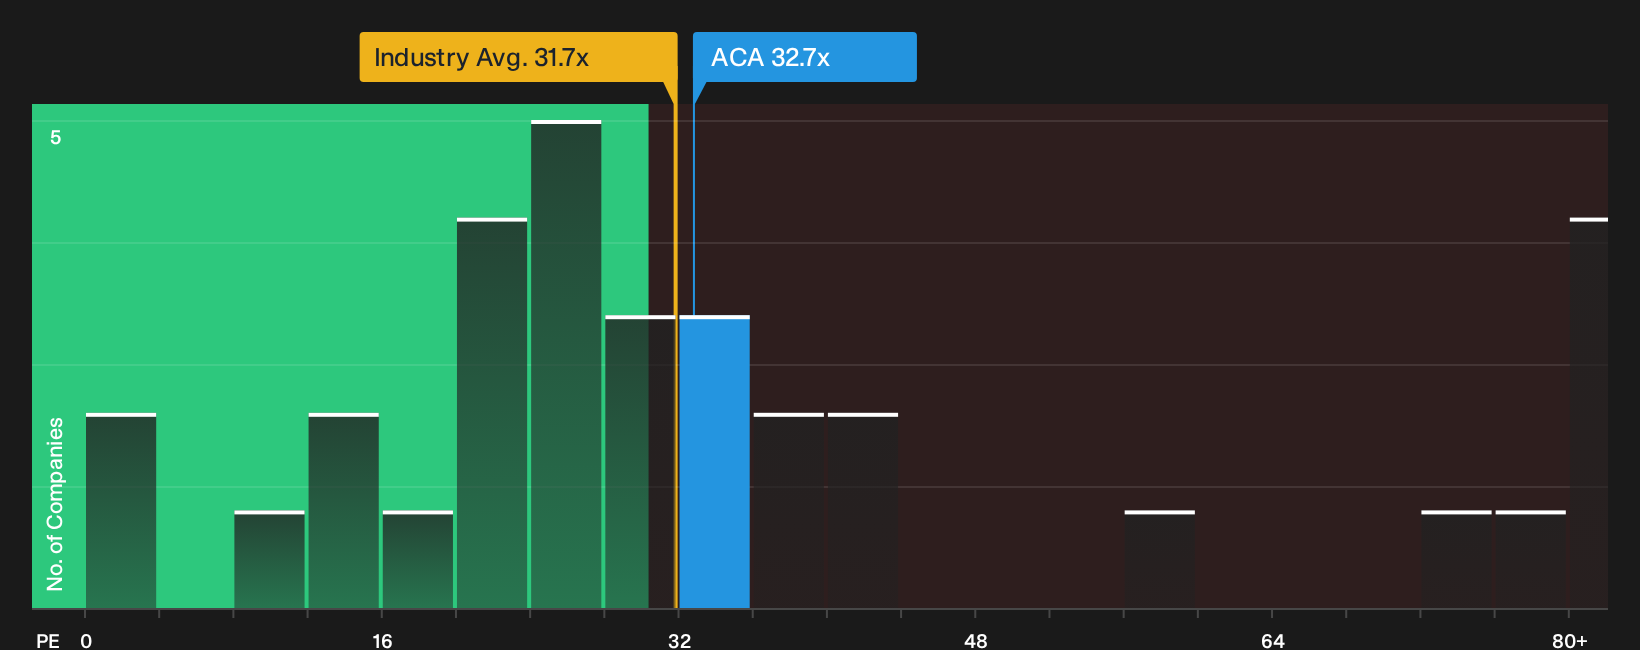
The fair value narrative around Arcosa leans heavily on future earnings and the CRH offer multiple. A simple P/E cross check tells a sharper story. The stock trades at 32.7x earnings, roughly in line with the US Construction sector at 32.8x, yet well above a fair ratio of 14.3x that the market could eventually lean toward. That gap frames more downside risk if sentiment cools than upside from re rating, so the real question is how confident you are that current enthusiasm holds.
To pressure test that gap using earnings based pricing, review the valuation breakdown and how the numbers stack up against peers, the wider industry and the fair ratio view in our full analysis, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Arcosa is divided, with some investors focused on the risks and others on the potential rewards. To evaluate the situation for yourself, move quickly and review the balance of 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Arcosa?
You have already done the hard work understanding Arcosa. Do not stop there when a wider set of opportunities could sharpen your overall portfolio decisions.
- Target stability by reviewing companies with resilient finances and low risk profiles using our 31 resilient stocks with low risk scores.
- Hunt for potential bargains by scanning our 29 high quality undervalued stocks that combine quality fundamentals with pricing that may not fully reflect them yet.
- Strengthen your income stream by checking companies in our 8 dividend fortresses that pair higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com