
TotalEnergies (ENXTPA:TTE) Stock Still Offers Earnings Value After A 131% Run
TotalEnergies has delivered a powerful run for long term holders, yet the recent cooling in the share price puts a simple question back on the table for anyone looking at the stock today. After such a strong stretch, is the current valuation still grounded in what the business earns, or has sentiment moved ahead of its earnings power.
- Over the past 5 years, TotalEnergies has returned 131.4%, which puts meaningful weight on whether that share price climb is still supported by the company’s earnings profile.
- Management’s plan through 2030 to grow oil and gas output alongside higher shareholder returns can influence how investors think about future earnings capacity and the durability of cash generation that sits behind today’s P/E and related multiples.
- Your read on TotalEnergies is one view; the desks covering it have another. See what analysts think TotalEnergies's shares could be worth.
The issue now is whether the earnings of TotalEnergies are strong and reliable enough to justify the current share price after such a long stretch of gains.
If you are weighing whether TotalEnergies at €75.42 still matches its earnings profile, a focused stock screen built around similar quality filters can be a useful second reference point, starting with solid balance sheet and fundamentals stocks screener (207 results).
Is TotalEnergies Still Cheap on Earnings?
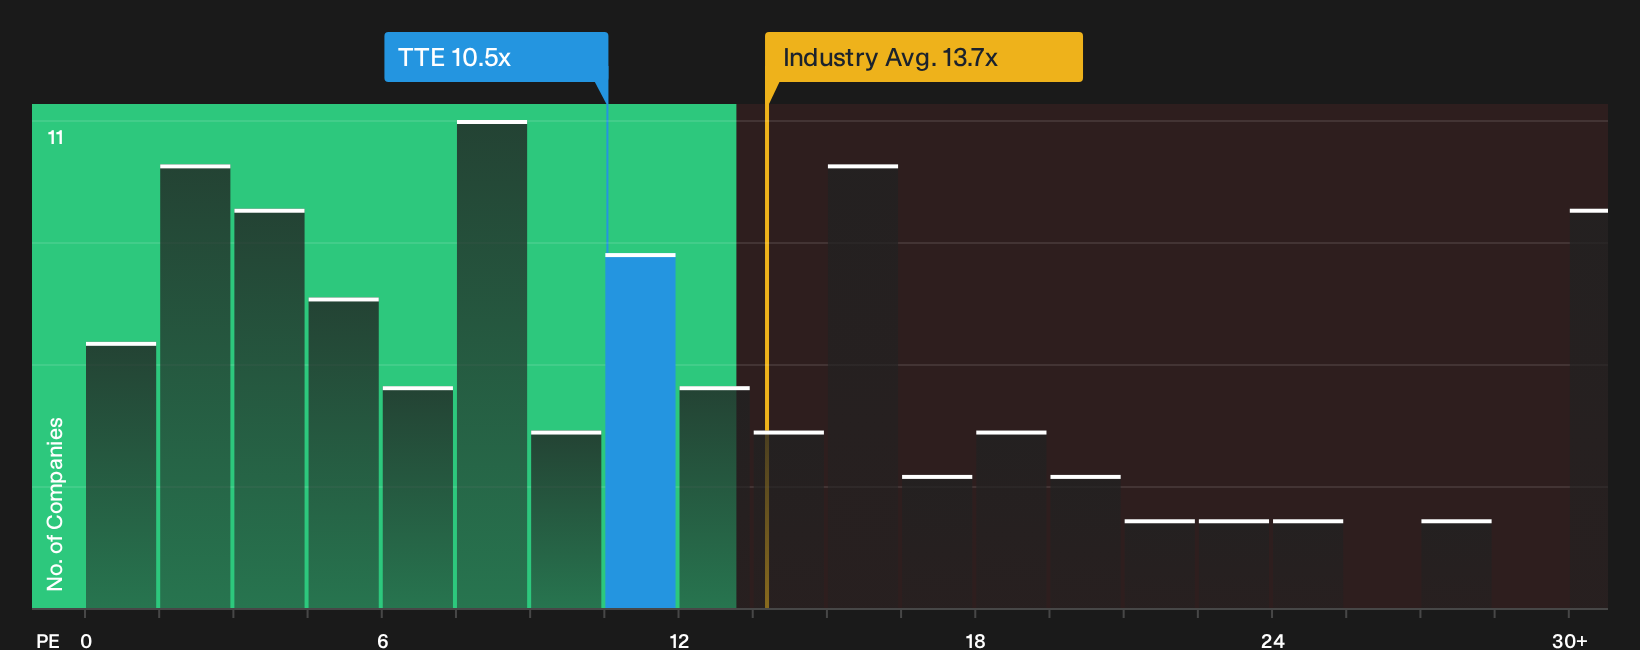
The P/E ratio works well for TotalEnergies because earnings and cash flow are central to how investors judge large integrated oil and gas groups. At a P/E of 10.5x, the stock trades slightly below the Oil and Gas industry average of 12.8x and also under the peer group on roughly 11.4x, so the market is not placing a premium multiple on the current earnings stream.
The Fair Ratio model, which estimates the P/E level you might expect once growth prospects, profitability, size and risk are factored in, points to a higher multiple than where TotalEnergies is priced today, which leans toward the shares looking undervalued on this metric. Because management is publicly targeting higher shareholder returns through 2030, the current discount to both peers and that tailored benchmark suggests recent announcements have not fully reset the valuation. Explore the numbers behind TotalEnergies's P/E valuation.
The TotalEnergies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation question for TotalEnergies leaves off by spelling out what growth, profitability and earnings paths would need to play out for the shares to look meaningfully higher or lower than today. Each narrative lays out its own set of assumptions behind a fair value view, so you can compare that framework with how TotalEnergies' results and capital plans evolve on the Community page over time.
Community views on TotalEnergies are split between those who see extra upside in the multi energy shift and others who think the current pricing already captures most of the story.
Bull case: 14% undervalued
"A resilient business model that balances volatile hydrocarbon cycles with growing renewable and power generation divisions, together with ongoing buybacks..."
Discover why this Narrative puts TotalEnergies at 14% undervalued.
Bear case: roughly fairly valued
"Intensifying global policy action on the energy transition, coupled with accelerating regulatory pressure to reduce emissions, threatens to erode long-term oil and gas demand..."
Explore why this Narrative puts TotalEnergies at roughly fairly valued.
The missing question for TotalEnergies, who is steering this ship and on what pay incentives
Valuation work only goes so far if you do not know which executives are pulling the levers, how their rewards are structured, and whether those pay packets really line up with your interests. See who runs TotalEnergies and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com