
Missed QuickLogic's Run? What Holders Had To Believe
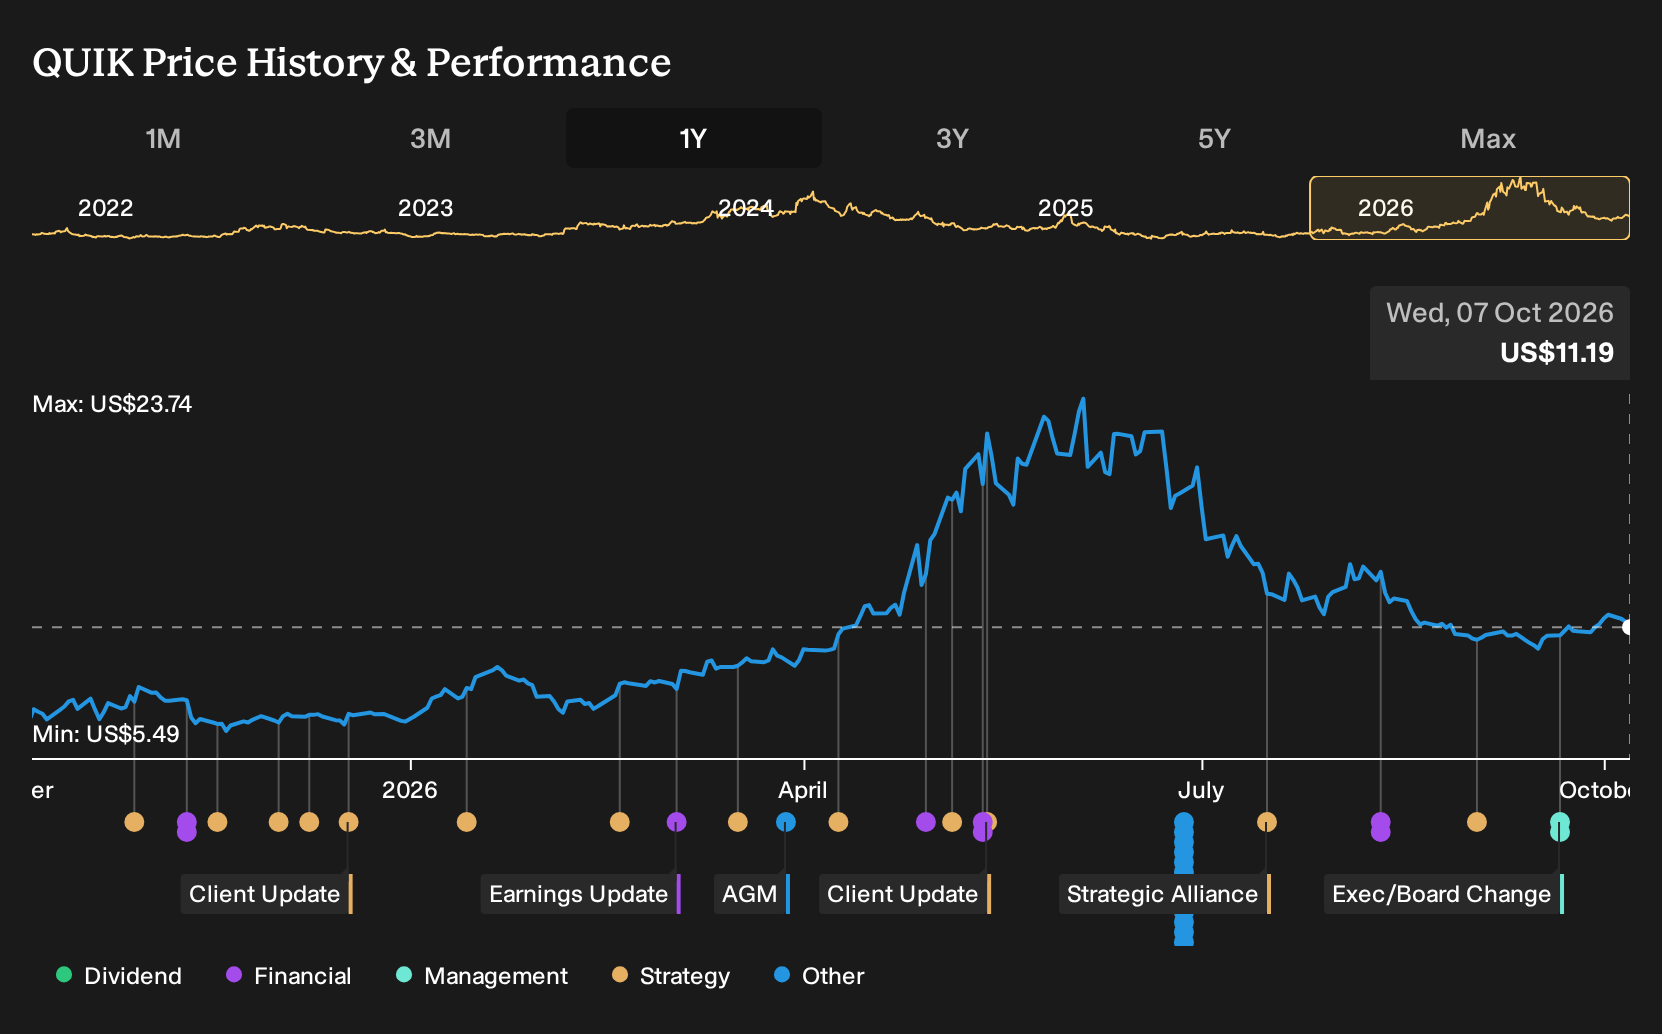
If QuickLogic was on your watchlist rather than in your portfolio, the return may sting. Holding QuickLogic over the past year would have returned 71.1%, including dividends. That kind of move begs a simple question: what clues were already on the table before it happened? If analysts were banking on an onshore, rad hard FPGA push and an IP heavy storefront model to reshape the business, which of those assumptions would you have treated as credible enough to act on?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made QuickLogic harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Two QuickLogic Stories Investors Had To Weigh
The shares cost US$6.68 at the start of the period, and QuickLogic sat between two sharply different but plausible stories about its future.
On the optimistic side, the bull Narrative put Fair Value at US$7.97, or 19% above the start price. This view hinged on 26.3% revenue growth and profit margins reaching 14.1% within three years.
The more cautious view set Fair Value at US$5.95, or 11% below the start price. This perspective stressed dependence on a few long-cycle government and aerospace contracts as a key source of volatility.
What The Results Changed For QuickLogic
The clearest fresh fact for QuickLogic holders was the Q2 2026 report. Revenue was US$5.482m versus US$3.687m a year earlier, and the loss narrowed from US$2.661m to US$0.882m as net margin improved from 72.2% negative to 16.1% negative. That supported the optimistic case on direction, yet profitability remained unproven, so the cautious lens on risk still mattered.
The lesson to draw is straightforward: when a thesis leans heavily on margin expansion, track the reported net margin every quarter and test whether the trend is moving toward the target or stalling.
What QuickLogic's Price Move Now Asks You To Believe
QuickLogic trades at US$11.19 today, after a 71.1% gain over the past year. The selected Narrative sets its Fair Value above that level and ties the gap to how its radiation hardened FPGA and eFPGA plans might reshape future economics.
The same Narrative flags heavy dependence on a few long-cycle defense and aerospace contracts and rising R&D needs. Anyone paying today’s price has to judge whether customer concentration can stay manageable while new programs and IP licensing grow strongly enough to support that higher figure.
"While QuickLogic's accelerated investments in proprietary rad-hard FPGAs and advanced eFPGA IP target expanding demand from AI-enabled edge devices and US defense supply chain localization, the company's heavy reliance on a concentrated set of long-cycle government and aerospace contracts heightens the risk of revenue volatility and leaves future top-line growth exposed to project delays or cancellations."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 35% below our estimate - convert subsea project demand into longer-term, higher margin services engagements.
- Company 2 - 33% below our estimate - turn technology-focused backlog into complex data center and modular construction projects.
- Company 3 - 24% below our estimate - supply advanced GPU hardware and integrated AI software stacks for data centers.
That is three of the list. See all 25 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com