
E Infrastructure Backlog Growth Could Shape The Case For Sterling Infrastructure Stock
- Sterling Infrastructure recently appointed Katherine Hargis as Senior Vice President, General Counsel, Chief Compliance Officer, and Corporate Secretary, bringing experience from legal and governance roles at Key Energy Services and U.S. Concrete.
- Hargis’ background in enterprise compliance, cybersecurity, human capital, and risk management looks important as Sterling Infrastructure works through a multibillion-dollar E Infrastructure backlog tied to data centers and manufacturing megaprojects.
- The focus now turns to how Sterling Infrastructure's investment narrative may be influenced by this leadership change in legal and compliance.
Scan how Sterling Infrastructure fits into the broader buildout of data centers and megaprojects by comparing it with our hand-picked 91 AI infrastructure stocks list.
Sterling Infrastructure Investment Narrative Recap
Sterling Infrastructure is built around a simple belief. You need to think record E-Infrastructure work tied to data centers, manufacturing sites and power projects will keep converting from backlog into revenue at healthy margins. The short term swing factor is how smoothly that US$6b plus backlog turns into cash while project complexity, labor needs and cost inflation stay manageable.
The biggest current risk is that mega project awards or data center capital spending slow, which would hit that E-Infrastructure engine. Katherine Hargis stepping in as General Counsel and Chief Compliance Officer looks important but not a game changer for near term demand. It matters more for execution discipline on large, higher risk jobs.
The most relevant context for this management change is Sterling Infrastructure’s push deeper into mission critical E-Infrastructure work like data centers, semiconductor facilities and large manufacturing plants. That shift raises legal, contract and compliance stakes, since individual projects can be very large and highly customized with strict customer requirements.
Hargis brings experience in enterprise compliance, governance, cybersecurity and risk management from Key Energy Services and U.S. Concrete. That background lines up with Sterling’s need to oversee complex contracts, protect margins and control downside on disputes or project issues. For investors, the announcement sits squarely in the execution bucket, supporting the existing catalysts rather than redefining them.
Sterling Infrastructure's narrative projects US$6.1b revenue and US$1.2b earnings by 2029. That profile assumes 21.0% yearly revenue growth and an earnings increase of about US$768.5m from US$431.5m today.
Uncover why Sterling Infrastructure's fair value indicates a 58% potential upside to its current price that could narrow quickly as investors re-rate the stock.
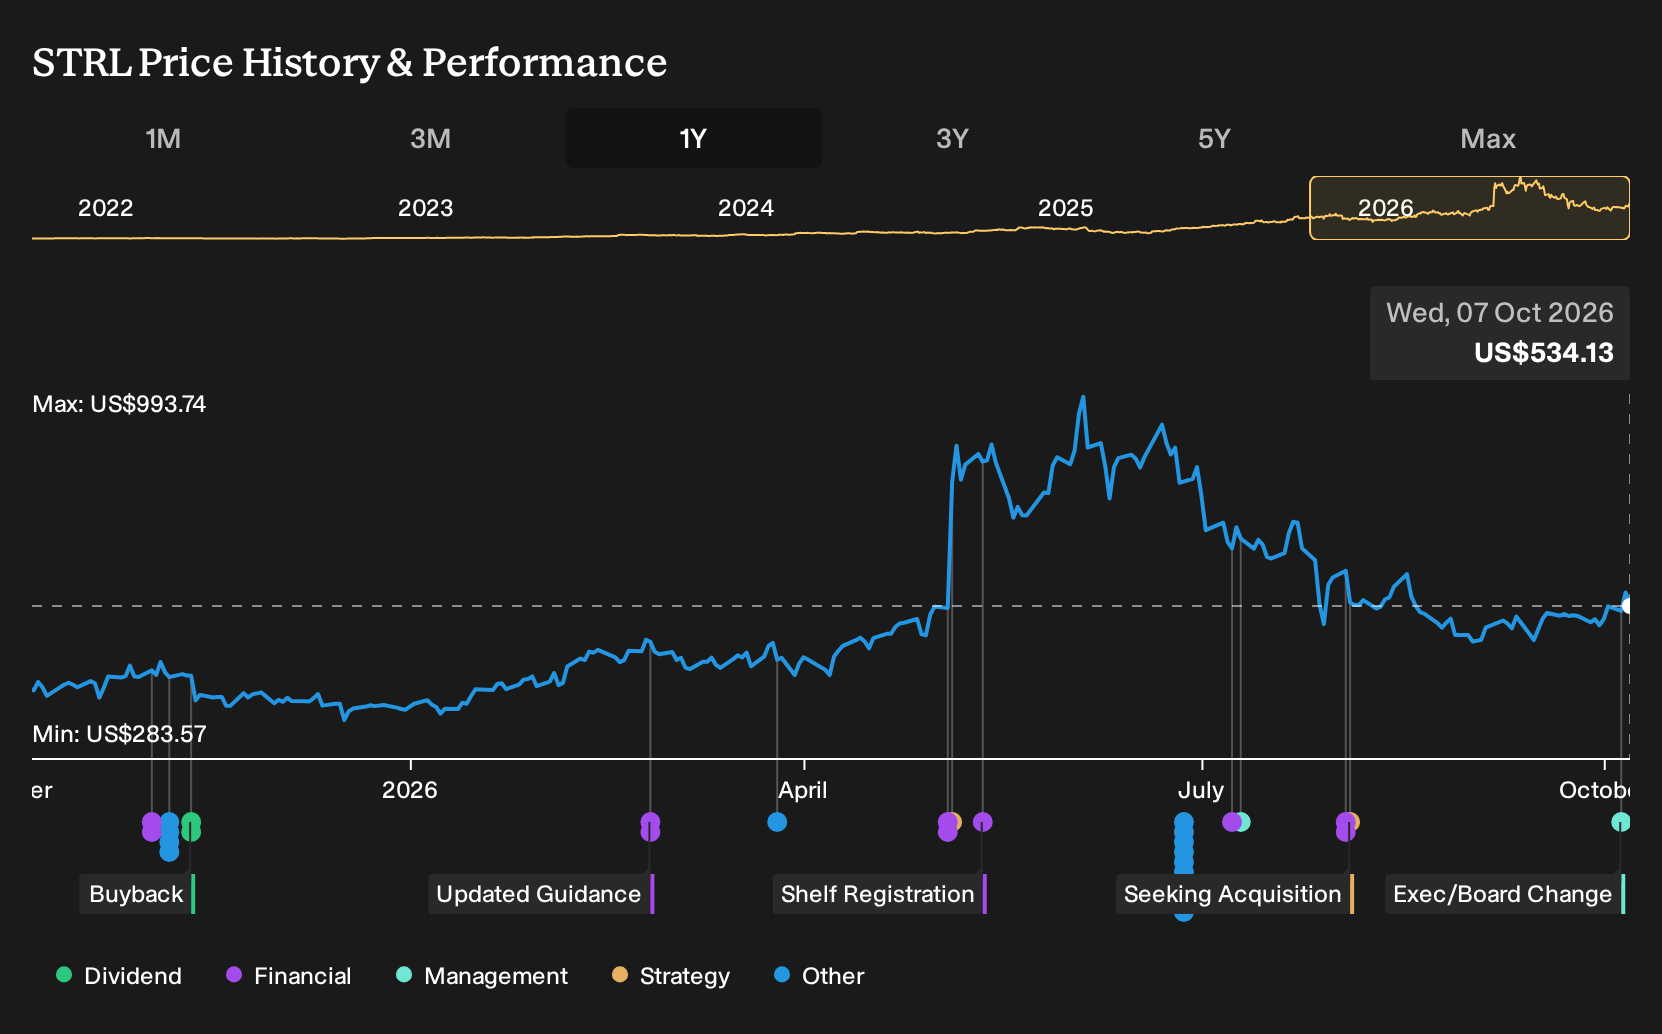
Exploring Other Perspectives
Some of the most optimistic analysts see the real catalyst for Sterling Infrastructure in accelerating AI and data center builds. Before this leadership change, they were already modeling revenue of about US$4.5b and earnings near US$1.0b by 2029. You should expect those bullish narratives to evolve as the new General Counsel settles in.
Explore 3 other Sterling Infrastructure fair value estimates, including one that suggests as much as 87% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sterling Infrastructure research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sterling Infrastructure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sterling Infrastructure's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sterling Infrastructure?
If you want to stress test your thesis on Sterling Infrastructure, it helps to compare it with other businesses that share similar qualities or offer very different risk and reward profiles. The Simply Wall St Screener can help you quickly filter the market down to a manageable shortlist that fits your style.
- Prefer resilient businesses with steadier profiles and fewer surprises? Use the 31 resilient stocks with low risk scores to surface candidates that aim for smoother journeys through the cycle.
- If balance sheet strength is your anchor, check out the list of solid balance sheet and fundamentals (25 results) and focus on companies that pair financial resilience with underlying business fundamentals.
- Hunting for opportunities the broader market may not be paying attention to yet? Start with the 20 high quality undiscovered gems and see which quieter stories line up with your return expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com