
Exploring 3 Undiscovered Gems in Global Markets
In the current landscape, global markets have been navigating mixed signals from economic indicators, with major U.S. stock indexes showing varied performance amidst concerns over inflation and interest rates. As investors weigh these factors, small-cap stocks in particular are drawing attention due to their potential for growth and resilience in uncertain times. When exploring undiscovered gems within this sector, it's crucial to consider companies that demonstrate strong fundamentals and adaptability to changing market conditions.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Goodbaby International Holdings | 6.30% | -1.33% | 24.07% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
| Bastide Le Confort Médical | 263.37% | 2.00% | -22.93% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
ALEC Holdings PJSC (DFM:ALEC)
Simply Wall St Value Rating: ★★★★★☆
Overview: ALEC Holdings PJSC is a construction company based in the United Arab Emirates with a market capitalization of AED6.65 billion.
Operations: ALEC Holdings PJSC generates revenue primarily from Building and Infrastructure Construction Services, contributing AED9.84 billion, followed by Related Businesses at AED4.48 billion and Energy at AED5.37 billion. The company faces eliminations amounting to -AED3.45 billion in its financial reporting, impacting overall revenue figures.
ALEC Holdings PJSC, a noteworthy player in the construction sector, recently showcased impressive sales growth with AED 4.38 billion for Q2 2026 compared to AED 2.89 billion last year. Despite this revenue surge, it reported a net loss of AED 16.34 million against a previous net income of AED 122.93 million, reflecting challenges in maintaining profitability amidst expansion efforts. The company boasts high-quality earnings and trades at an attractive valuation, being priced at 47% below its estimated fair value while having more cash than its total debt and well-covered interest payments (18.6x EBIT coverage).
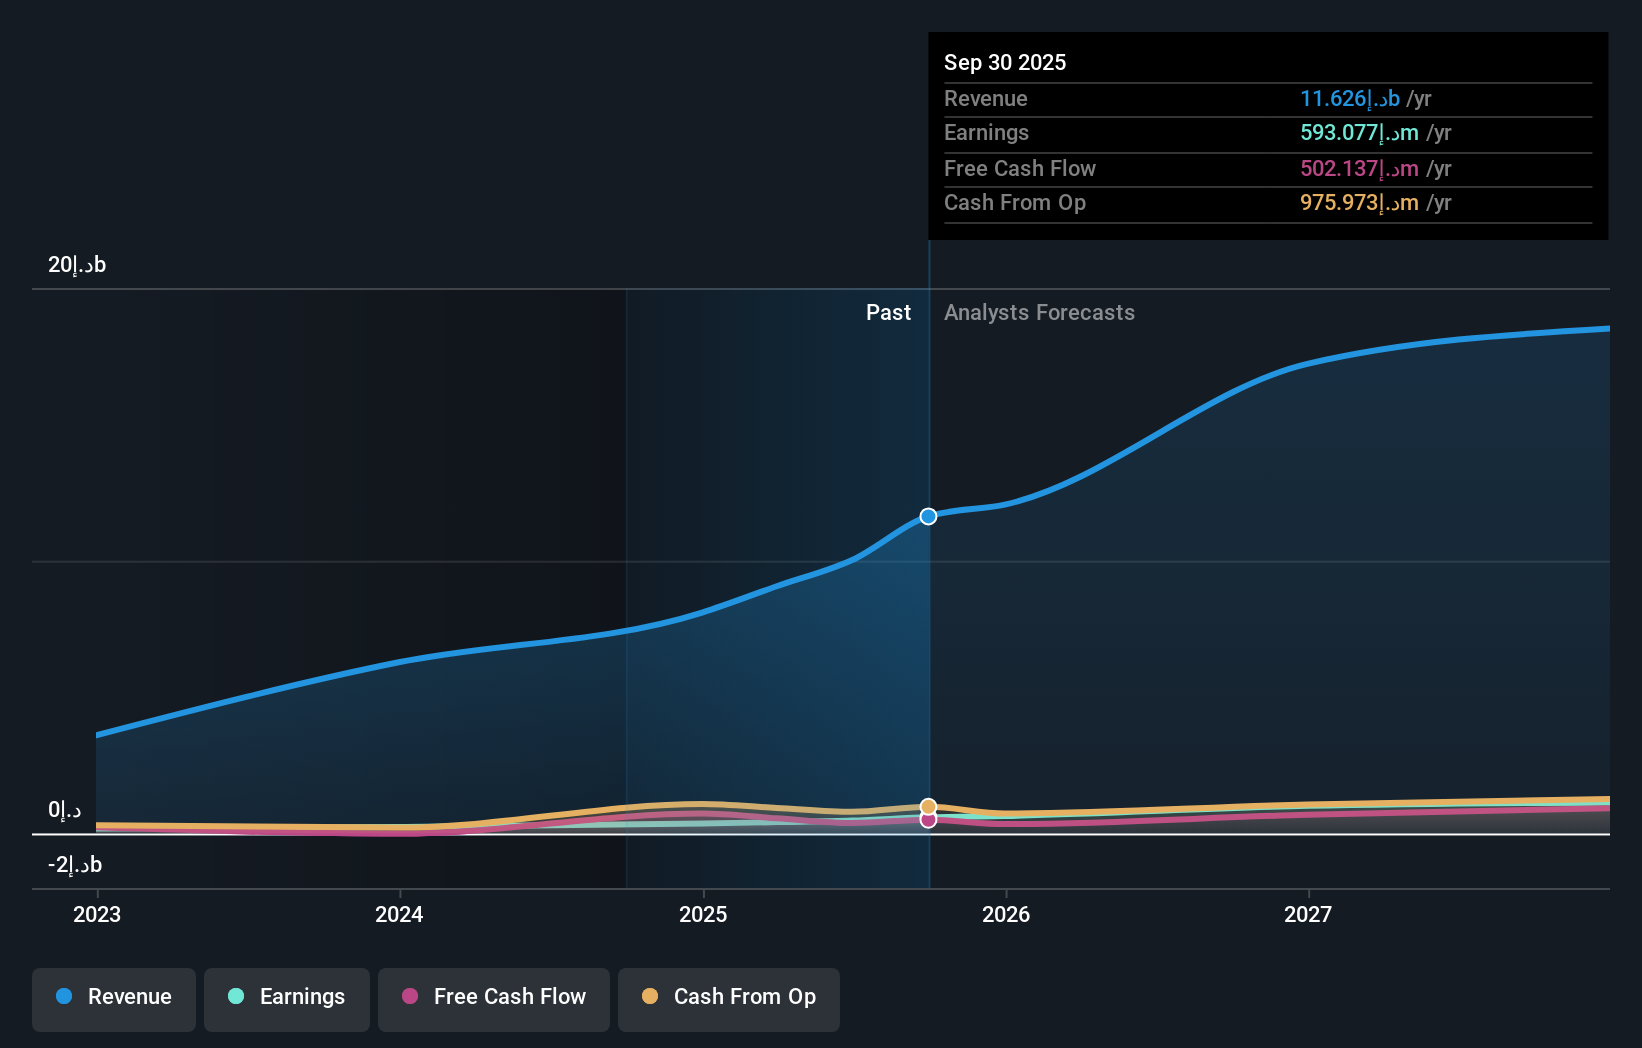
Maharah for Human Resources (SASE:1831)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Maharah for Human Resources Company provides manpower services to both public and private sectors in Saudi Arabia and the United Arab Emirates, with a market capitalization of SAR2.30 billion.
Operations: The company generates revenue primarily from its Corporate segment, which contributes SAR3.02 billion, and the Individual segment, contributing SAR539.29 million. Facility Management adds SAR92.43 million to the overall revenue stream. The company's net profit margin is a key financial metric to monitor for assessing profitability trends over time.
Maharah for Human Resources, a nimble player in the market, has shown impressive growth with earnings up 94.3% over the past year, outpacing its industry peers. The company reported second-quarter sales of SAR 930 million and net income of SAR 54 million, reflecting strong performance compared to last year's figures of SAR 755 million and SAR 44 million respectively. Despite a debt-to-equity ratio increase to 33.2% over five years, their interest payments are well covered by EBIT at an impressive 8.5 times coverage. Trading at a notable discount of approximately half its estimated fair value suggests potential upside for investors eyeing value opportunities within this sector.
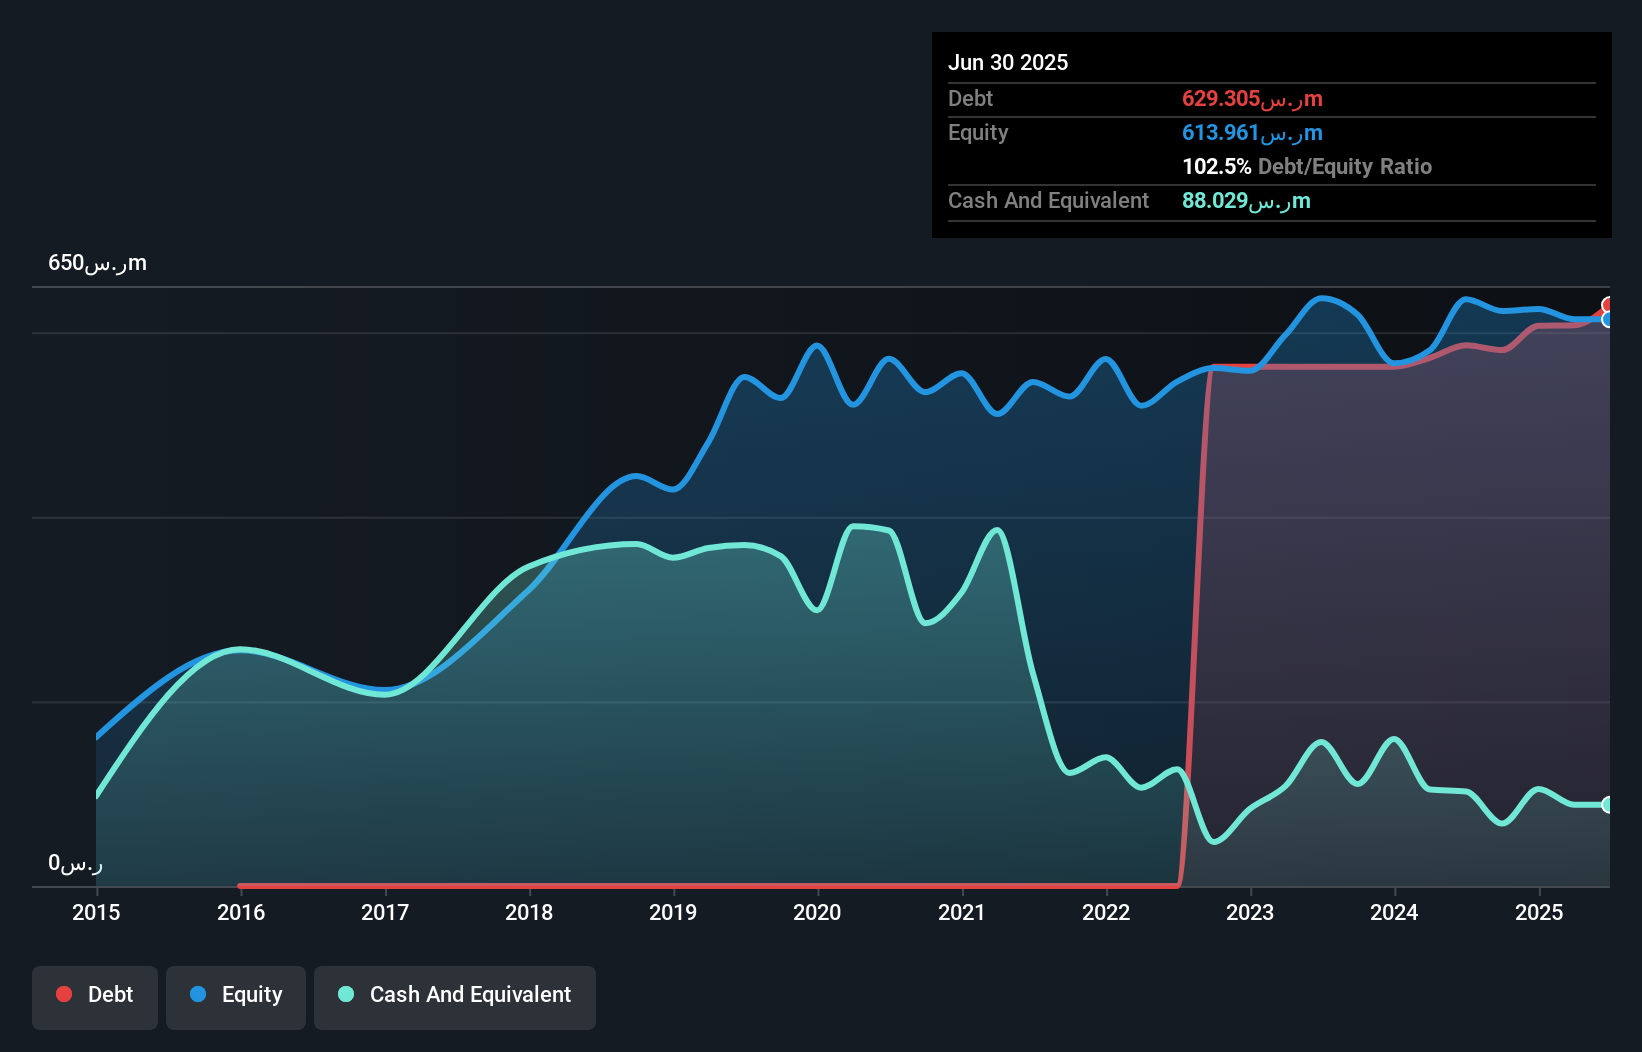
Weichai Heavy Machinery (SZSE:000880)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Weichai Heavy Machinery Co., Ltd. specializes in the production and sale of medium- and high-speed diesel engines, generator sets, propulsion systems, and integrated power systems for China's marine and power generation sectors, with a market cap of CN¥11.07 billion.
Operations: The company generates revenue primarily from the General Equipment Manufacturing Industry, amounting to CN¥7.60 billion.
Weichai Heavy Machinery, a smaller player in the machinery sector, has shown impressive growth with earnings up 60.6% over the past year, outpacing industry averages. It seems their strategic focus on diesel engines and related products is paying off, as evidenced by a recent sales increase to CNY 4.04 billion from CNY 2.58 billion last year. Despite an increased debt-to-equity ratio of 2.9% over five years, the company holds more cash than total debt, suggesting financial stability. Trading at an attractive value compared to peers and industry norms enhances its appeal for potential investors seeking growth opportunities within this niche market.
- Dive into the specifics of Weichai Heavy Machinery here with our thorough health report.
Understand Weichai Heavy Machinery's track record by examining our Past report.

Next Steps
- Navigate through the entire inventory of 168 Global Undiscovered Gems With Strong Fundamentals here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com