
How Oak Hill Parkway Opening Will Impact Fluor Stock (FLR)
- Fluor and joint venture partner Balfour Beatty have completed and opened the US$677 million Oak Hill Parkway project in southwest Austin. The project rebuilt about seven miles of U.S. 290 and SH 71 with new flyovers, overpasses and multimodal access.
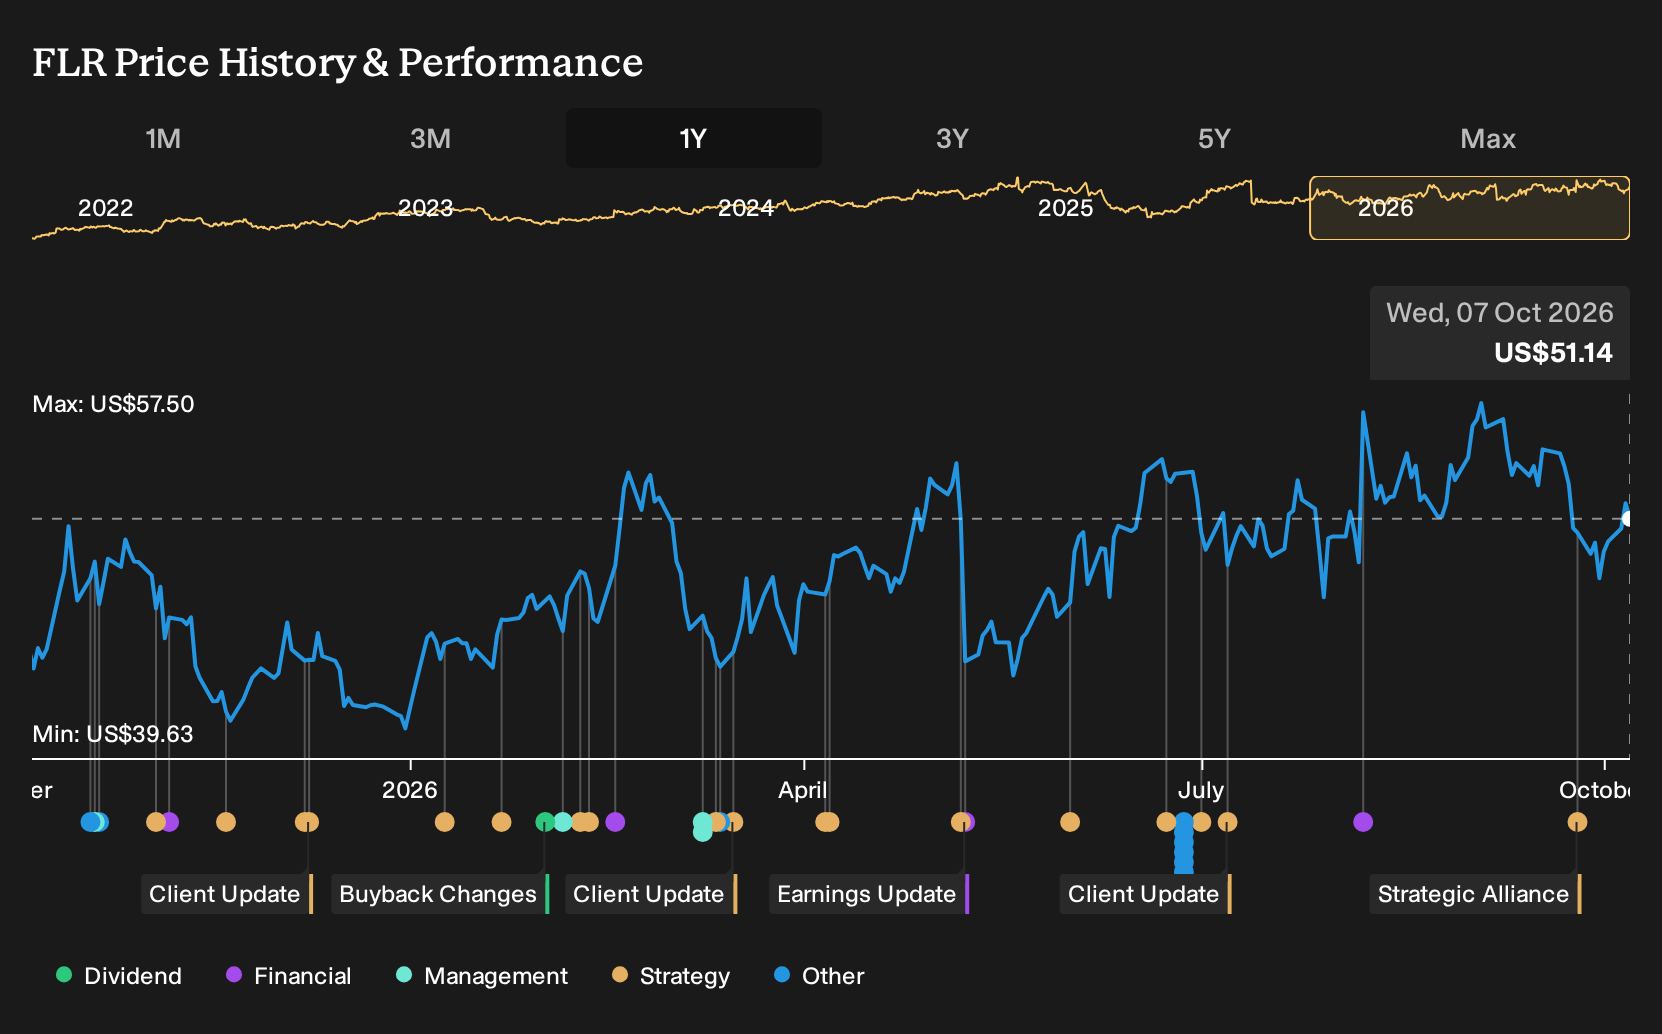
- This delivery adds another large reference project to Fluor's portfolio at a time when reported Q2 2026 awards of more than US$6 billion and a US$26.9 billion backlog indicate a substantial amount of contracted work in front of the business.
- Investors can now consider how Fluor's investment narrative could be affected by the Oak Hill Parkway completion and opening milestone.
Compare Fluor's latest contract win with other large project builders by scanning 43 power grid technology and infrastructure stocks tied to major infrastructure spending and grid upgrades.
Fluor Investment Narrative Recap
To own Fluor, you need to believe the company can keep turning a large US$26.9b backlog and an asset light, reimbursable heavy project mix into steadier earnings and cash. The Oak Hill Parkway opening supports that view by showing complex road and interchange work moving through to completion, but it does not fundamentally change the near term story.
The key short term catalyst is execution on current EPC projects without more lump sum surprises after the US$37 million mining charge and recent guidance trim. The biggest risk remains further margin pressure from productivity issues or currency swings, which could pull adjusted EBITDA guidance lower again if problems repeat.
The Oak Hill milestone connects most directly to Fluor’s backlog and award momentum in infrastructure and transport related work. Awards above US$6b in Q2 2026 and the current backlog level give the business a significant pool of contracted activity, and delivered projects like Oak Hill help validate that pipeline with real world outcomes for clients.
For you as an investor, the question is whether projects of this scale can be delivered consistently under the newer contracting approach without repeating legacy issues. Successful delivery supports the idea that Fluor can use its prospect pipeline, including LNG, mining, nuclear and power, to improve earnings and cash flow, while execution missteps would keep the risk side of the thesis front of mind.
Fluor's narrative projects US$19.7b revenue and US$497.9m earnings by 2029. This assumes 8.3% yearly revenue growth and an earnings increase of about US$2.5b from current earnings of a US$2.0b loss.
Uncover why Fluor's fair value indicates a 21% potential upside to its current price before the market begins to close that gap.
Exploring Other Perspectives
Some of the most optimistic analysts think the real swing factor for Fluor is not road work like Oak Hill, but how quickly legacy loss projects roll off. Before this news, the bullish camp was modeling about US$22.0b of revenue and US$743.4m of earnings by 2029, far above consensus. You may want to compare those expectations with your own and decide whether Oak Hill shifts your view.
Explore 4 other Fluor fair value estimates, including one that suggests as much as 40% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fluor research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Fluor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fluor's overall financial health at a glance.
Looking For More Ideas Beyond Fluor?
If Fluor has sharpened your focus on construction, infrastructure and contracted cash flows, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles.
- For investors who care most about quality at a sensible entry point, scan a curated 29 high quality undervalued stocks that pair strong fundamentals with what our models flag as attractive pricing.
- If capital preservation and balance sheet strength sit at the top of your checklist, focus on companies in the list of solid balance sheet and fundamentals (25 results) that may offer sturdier financial foundations.
- Income seekers who want yield with some built in resilience can review a set of 8 dividend fortresses that aim to combine regular payouts with robust underlying businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com