
Graham (GHM) Dropped, So Why Is It Still Drawing Attention?
Graham (GHM) has been drawing attention after recent share price moves, with the stock closing at $84.34. Investors are weighing this performance against its year to date and 1 year total return profile.
Recent trading has cooled, with the share price down 4.46% over the past day and 22.33% over 90 days. However, Graham still shows strong momentum when viewed through its 49.72% 1 year total shareholder return and very large 5 year total shareholder return multiple.
Scan beyond Graham to see how it compares with 20 high quality undiscovered gems, which have been quietly building strong long term total returns.
After a pullback that follows a very strong multi year run, the question around Graham is simple: Has most of the upside already played out, or does the current valuation still leave room ahead?
Most Popular Narrative: 38% Undervalued
Graham's most followed narrative pegs fair value at $135, which sits well above the recent $84.34 close and presents the stock as materially discounted by that lens.
Record $500 million backlog, with 35 to 40 percent expected to convert in the next 12 months and a multiyear book-to-bill profile above one times, supports sustained revenue growth and enhances earnings visibility.
See why 1 investors see Graham as 38% undervalued.
Result: Fair Value of $135 (UNDERVALUED)
Still, Graham's heavy exposure to long cycle defense programs and early stage space and nuclear markets could quickly challenge this upbeat narrative if funding or adoption slows.
Find out about the key risks to this Graham narrative.
Another View on Graham’s Valuation
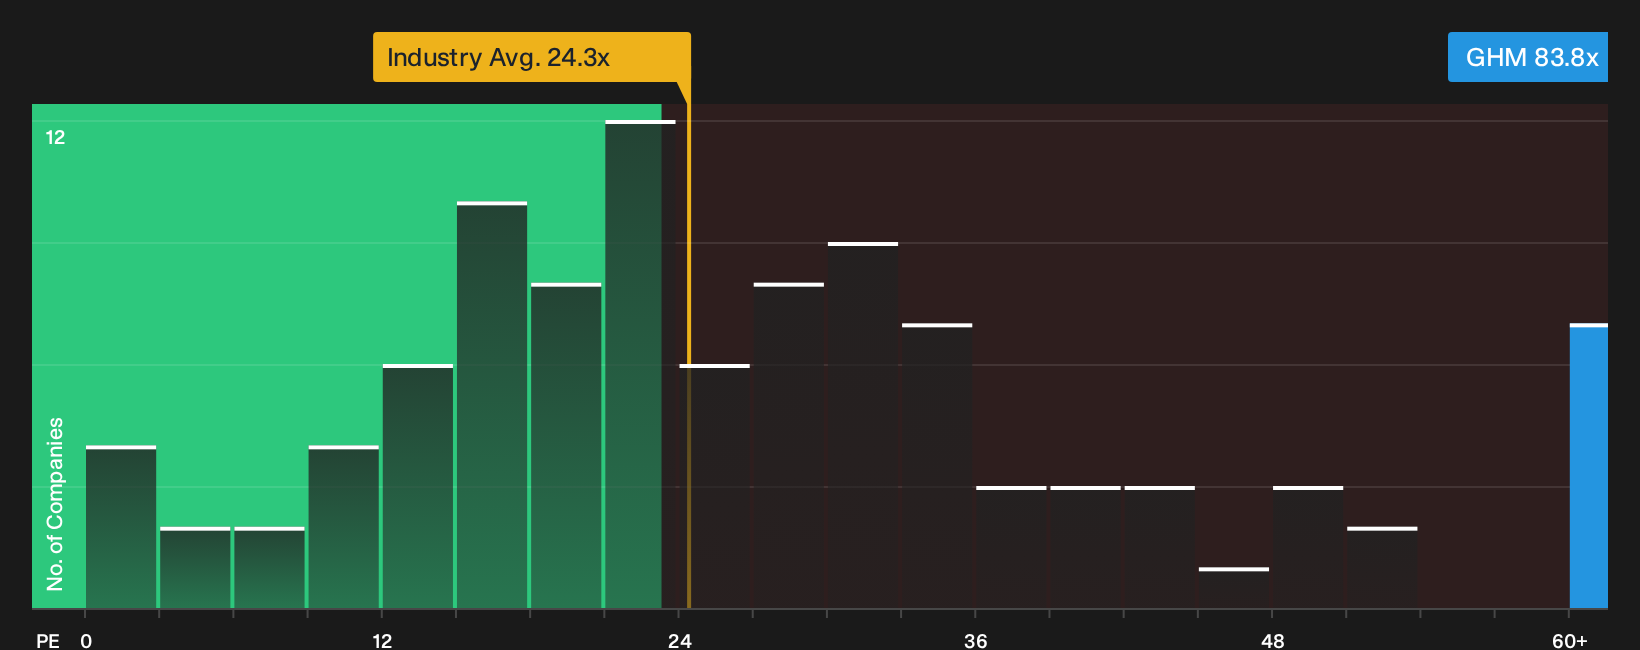
The fair value story around Graham looks very different once price multiples enter the frame. The stock trades on a P/E of 83.8x, compared with a fair ratio of 34.1x, a US Machinery industry average of 25x, and a peer group around 36.6x. That kind of gap points to real valuation risk if sentiment cools or growth expectations reset.
For readers weighing what this richer multiple might mean in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or a clear message, Graham’s story only becomes useful once you test the numbers yourself and pressure test the assumptions. If you want a fast way to benchmark the bright spots that investors are focusing on, start with the 2 key rewards
Looking for more investment ideas beyond Graham?
If Graham has you rethinking what belongs in your portfolio, do not stop here. The right watchlist can help reshape your overall return profile over time.
- Target underappreciated opportunities before the crowd by scanning the 29 high quality undervalued stocks, which focuses on companies that combine stronger fundamentals with pricing that has not fully caught up.
- Strengthen the income side of your portfolio with the 8 dividend fortresses, designed for investors who care about dependable cash flows, not just headline growth stories.
- Sleep easier through market noise by focusing on the 31 resilient stocks with low risk scores, where resilient balance sheets and steadier risk profiles take priority.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com