
Brookdale Senior Living (BKD) On Zacks Upgrade Is The Stock A Bargain Or Priced Right
Analyst Upgrade Puts Brookdale Senior Living in Focus
Zacks recently upgraded Brookdale Senior Living (BKD) to its highest rating based on rising earnings estimates and improving business fundamentals, drawing fresh investor attention to a stock that has been under pressure in recent months.
Recent trading tells a mixed story. Brookdale Senior Living’s share price has slipped around 8.5% over the past month and roughly 29.5% over the last three months. However, the 1-year total shareholder return of about 32.6% and 3-year total shareholder return above 150% indicate that longer term holders have still seen strong gains. This suggests that the recent pullback reflects a shift in near term risk perception more than a reset of the entire investment case.
Compare Brookdale Senior Living’s upgrade-driven story with a curated set of healthcare peers by scanning 35 healthcare AI stocks for potential breakout opportunities in the sector.
Brookdale Senior Living now trades well below the average analyst target, even after that Zacks upgrade and a sharp three month slide. Is this a genuine discount, or a warning the market is pricing in correctly?
Most Popular Narrative: 37% Undervalued
Brookdale Senior Living last closed at $10.77 while the most followed narrative anchors fair value at $17.00 per share. The current price implies a steep discount that investors need to weigh against the assumptions behind that estimate.
The ongoing shift in consumer preference toward aging in place and advancements in home healthcare technology threaten to cap or reverse occupancy growth, risking sustained declines in revenue and undermining the current expectation of strong pricing power across Brookdale's portfolio.
Persistent labor shortages and wage inflation in the U.S. service sector are likely to continue pushing operating expenses higher, significantly narrowing net operating margins even if occupancy rates stabilize near current levels.
See why 1 investors see Brookdale Senior Living as 37% undervalued.
Result: Fair Value of $17.00 (UNDERVALUED)
Still, if Brookdale Senior Living sustains occupancy above 80% and continues to refresh older communities, the bearish cash flow story could appear too harsh.
Find out about the key risks to this Brookdale Senior Living narrative.
Another View: SWS DCF Flags Brookdale Senior Living As Expensive
The earlier $17.00 fair value narrative leans on analyst earnings and multiples. A second lens, our DCF model, points the other way. With Brookdale Senior Living at $10.77 versus an estimated future cash flow value of $8.02, the shares screen as overvalued on this approach. Which story do you trust when cash generation is the anchor?
Look into how the SWS DCF model arrives at its fair value.
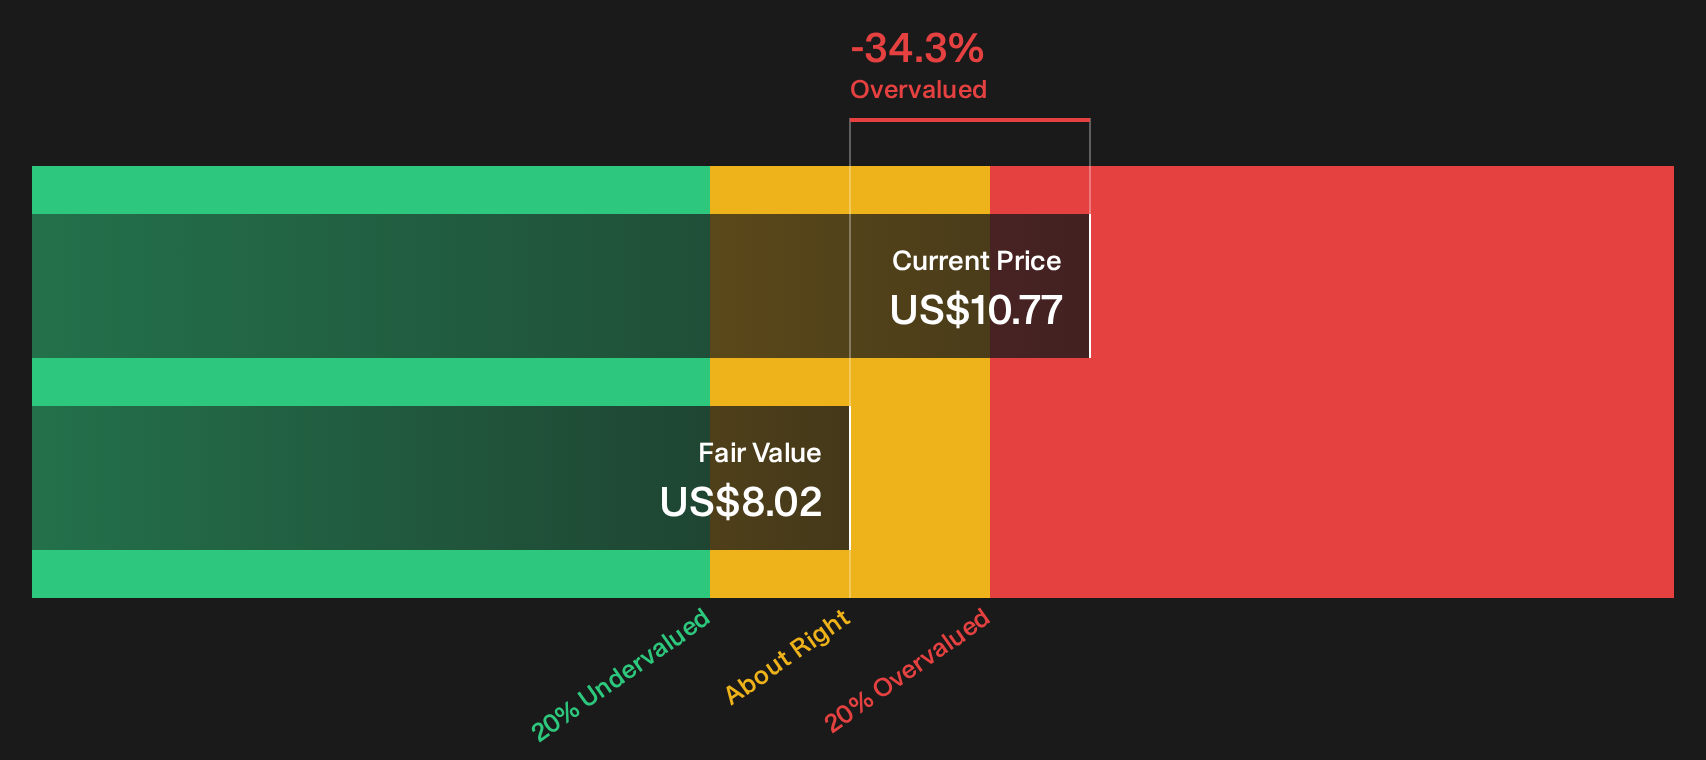
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brookdale Senior Living for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals run through the Brookdale Senior Living story, so if you care about both upside potential and real risks, move fast and stress test the thesis yourself with 2 key rewards and 1 important warning sign.
Hunting Beyond Brookdale Senior Living?
If Brookdale Senior Living has put the sector on your radar, do not stop here. Fresh ideas often come from comparing very different kinds of opportunities.
- Target potential bargain entries by scanning companies on our value focused list with 29 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by reviewing a 31 resilient stocks with low risk scores that screens for stronger risk profiles.
- Spot future leaders before the crowd by checking a 20 high quality undiscovered gems that highlights lesser known businesses with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com