
WD-40 (WDFC) Just Gave Investors Something To Think About
WD-40 (WDFC) has drawn fresh attention after a recent price of US$201.50 and a share performance that declined about 3% over the past month and 16% in the past 3 months.
For context, WD-40 shares have eased over the past quarter, with a 90 day share price return that declined 15.8%. However, the year-to-date share price return is positive, and the 1 year total shareholder return of 6.7% points to modest longer term momentum supported by dividends.
Compare WD-40's recent share pullback with other resilient, cash generative businesses by scanning our hand picked 31 resilient stocks with low risk scores that have been filtered for lower risk profiles and sturdier fundamentals.
WD-40 now trades at a sizeable discount to analyst targets even after that recent slide. Is the market correctly pricing in caution, or has sentiment pushed the shares too far below fair value?
Most Popular Narrative: 34% Undervalued
Against WD-40's last close of $201.50, the most followed narrative anchors on a higher fair value of $305, built on firm views about growth, margins, and required return at a 7.24% discount rate.
The company has captured only about one quarter of its estimated global potential for WD-40 Multi-Use Product and a little over one tenth for WD-40 Specialist, and continued geographic expansion and deeper penetration in large markets such as India, China and Latin America are key focus areas for pursuing additional revenue growth and potentially expanding earnings power.
See why 0 investors see WD-40 as 34% undervalued.
Result: Fair Value of $305 (UNDERVALUED)
Still, the bullish WD-40 story could be knocked off course if regional growth lags management goals or if higher input and freight costs squeeze margins again.
Find out about the key risks to this WD-40 narrative.
Another View on WD-40's Valuation
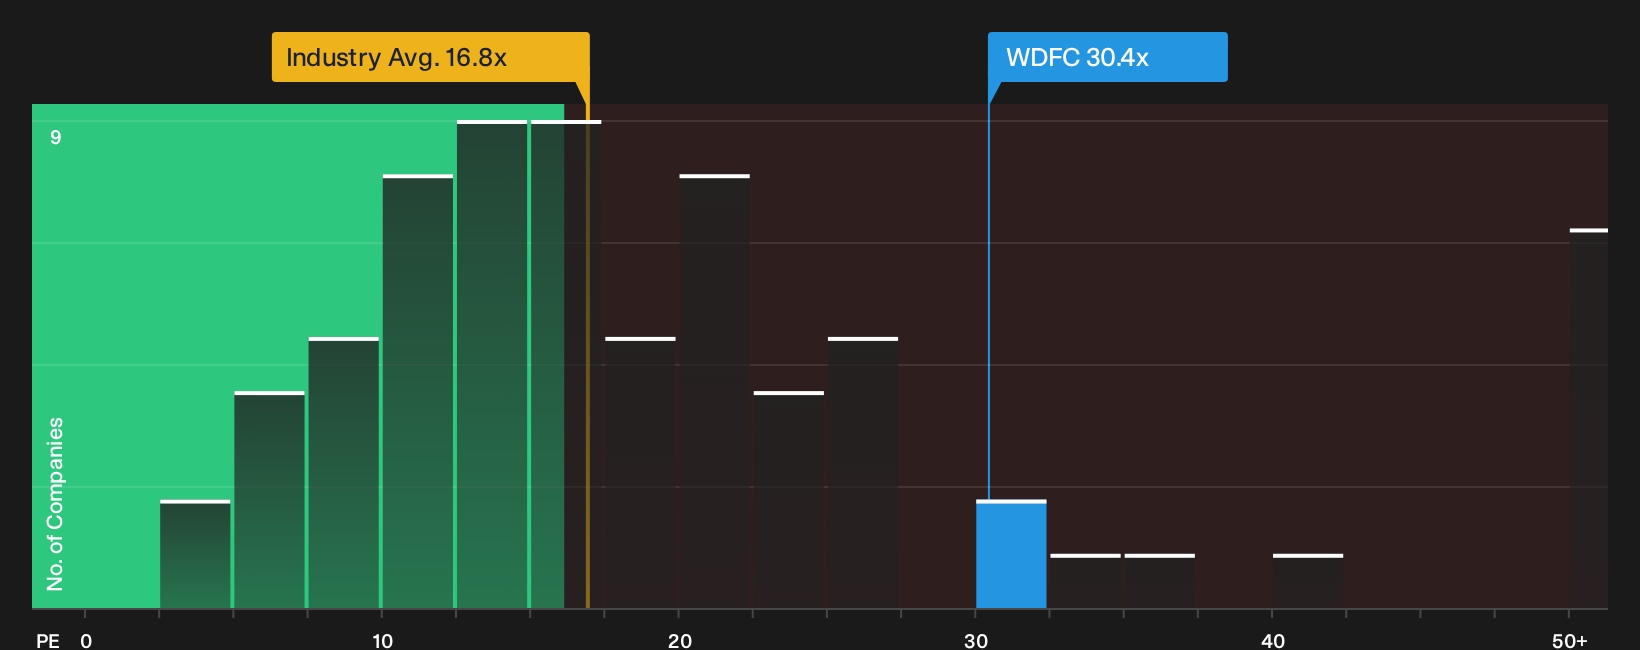
WD-40 may look inexpensive against a $305 fair value narrative, but the current P/E of 30.4x presents a very different picture. That level is well above the 16.7x average for the Global Household Products group and more than double the 14.1x fair ratio.
In practice, that gap means investors are already paying a premium multiple that could compress if sentiment cools or earnings delivery falls short. The question is whether you are comfortable with that valuation risk at today’s price or prefer to wait for the P/E to move closer to the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That valuation debate around WD-40 cuts both ways, which makes this a moment to move quickly and stress test the numbers yourself. To see why some investors remain optimistic about the upside, review the 3 key rewards.
Looking for more investment ideas beyond WD-40?
If WD-40 has you thinking harder about price, quality, and risk, do not stop here. Broader opportunity often sits just outside your current watchlist.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results) that consistently screen for financial strength.
- Hunt for mispriced quality by scanning the 29 high quality undervalued stocks that highlight companies with attractive metrics and room for investor attention.
- Build a cash flow focused watchlist by checking the 8 dividend fortresses that filter for higher yielding businesses with potential income appeal.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com