
Is China Overseas Land & Investment (SEHK:688) A Bargain Following Fresh Earnings Data?
China Overseas Land & Investment (SEHK:688) is trading around HK$13.06 after recent data showed annual revenue of HK$182.47b and net income of HK$11.12b. These figures give investors fresh numbers to reassess the property developer.
Recent trading has been fairly steady, with the share price up 4.2% over the past 90 days and a 1-month share price return of 1.2% around the current HK$13.06 level. However, the 1-year total shareholder return has slipped 0.4% and longer term 3 and 5 year total shareholder returns have also declined, suggesting momentum has cooled even as some investors reassess China Overseas Land & Investment on fresher earnings data and perceived risk.
Scan beyond China Overseas Land & Investment and compare its recent performance and fundamentals with a curated set of 184 high quality undervalued stocks that currently screen well on quality and valuation.
China Overseas Land & Investment has barely moved over the past year, yet analyst targets and intrinsic value estimates sit well above the HK$13.06 price. How much of that gap looks justified by the fundamentals?
Price-to-Earnings of 11x: Is it justified?
On simple earnings terms, China Overseas Land & Investment trades on a P/E of 11x, which places the HK$13.06 share price at a lower earnings multiple than the peer average but above the wider Hong Kong real estate industry.
The P/E ratio compares the current share price with earnings per share, so it gives you a quick sense of how much investors are paying for each unit of profit. For a large property developer like China Overseas Land & Investment, this lens matters because profit quality, earnings volatility and sector sentiment can all influence how rich or cheap that earnings stream looks.
Analyst data indicates that earnings are forecast to grow 10.97% per year, while recent history shows profit growth has been under pressure, with earnings declining 20.1% over the past year and falling 26.8% per year over the last 5 years. Against that backdrop, an 11x P/E that screens as good value versus the peer average multiple of 14.8x suggests the market could be assigning a lower price to those forecast profits than it might if the track record were smoother. At the same time, the current P/E is described as expensive versus the Hong Kong real estate industry average of 9.2x, a gap that signals investors are still willing to pay a premium relative to the broader sector, possibly reflecting the group’s scale, balance sheet or perceived earnings quality. The estimated fair P/E of 14.8x sits meaningfully higher than the current 11x level. That is the kind of divergence that can close either through price moves, earnings changes or both.
Explore the SWS fair ratio for China Overseas Land & Investment.
Result: Preferred multiple of Price-to-Earnings of 11x (UNDERVALUED).
Still, the share price drift over 1, 3 and 5 years and earnings pressure in recent periods show how quickly sentiment on China Overseas Land & Investment could sour again.
Find out about the key risks to this China Overseas Land & Investment narrative.
Another View on China Overseas Land & Investment’s Valuation
There is a different signal once the SWS DCF model is brought into the picture. On that view, China Overseas Land & Investment at HK$13.06 trades below an estimated future cash flow value of HK$31.21, which points to a very wide upside gap. This raises the question of whether that represents a margin of safety or a sign that the cash flow assumptions are too optimistic.
Look into how the SWS DCF model arrives at its fair value.
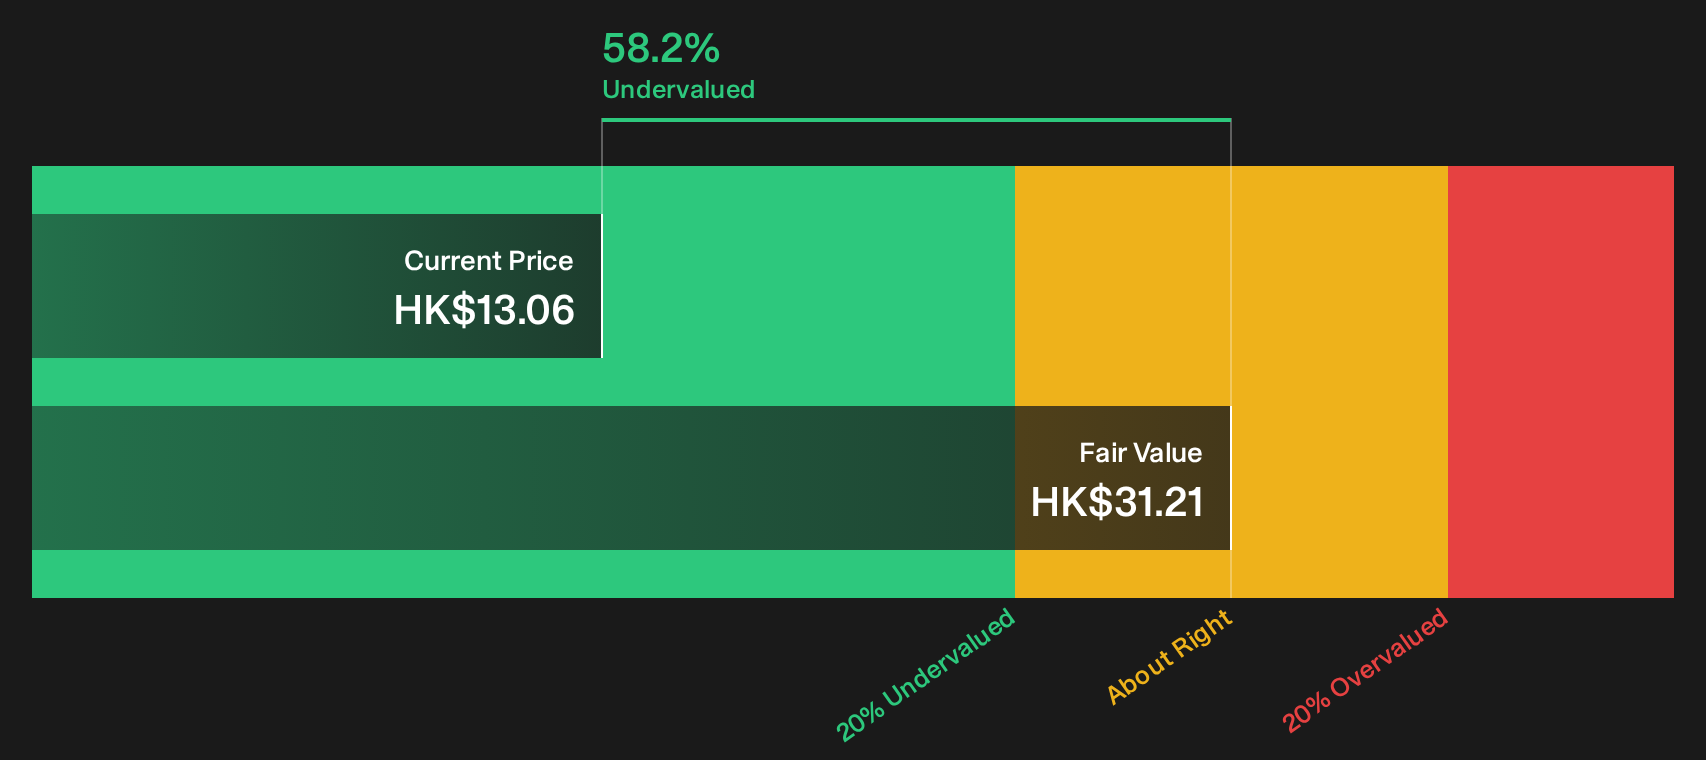
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Overseas Land & Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the mix of risk and potential reward around China Overseas Land & Investment matches your own read of the numbers? Dig into the figures, pressure test the assumptions, and then weigh the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond China Overseas Land & Investment?
China Overseas Land & Investment gives you plenty to think about, but your portfolio deserves a wider bench of ideas that fit different roles and risk levels.
- Target higher income potential by reviewing a curated 224 dividend fortresses that may appeal if you want yield with supporting fundamentals.
- Hunt for resilience by focusing on a list of solid balance sheet and fundamentals (207 results) that can help you stress test your portfolio against tougher conditions.
- Spot tomorrow’s potential leaders early by scanning a focused 619 high quality undiscovered gems before the crowd turns its attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com