
InPost (ENXTAM:INPST) Extends Its Strong Run, Is It Still 11% Undervalued?
InPost (ENXTAM:INPST) has drawn fresh attention after recent trading data showed a 3.6% gain over the past day, contrasting with a flat month and roughly unchanged performance over the past 3 months.
That single day move sits on top of a much stronger backdrop, with a year to date share price return of 48.6% and a 1 year total shareholder return of 48.0%, which points to momentum that has been building rather than fading.
Scan what that price swing in InPost might be hinting at, then size it up against other fast movers with the 619 high quality undiscovered gems.
InPost now trades around €15.45, with analyst targets pointing higher and an intrinsic value estimate sitting slightly above the current quote. Is the market discounting real risks, or being overly cautious about the story so far?
Most Popular Narrative: 10.6% Undervalued
On the most followed view, InPost is worth €17.28 per share, which sits above the last close of €15.45 and frames the recent surge against a still supportive long term thesis built on parcel locker scale and execution.
Ongoing expansion and network densification across key European markets, especially via M&A (Yodel, Sending) and rapid APM (locker) deployment, including battery-powered units from Bloq.it, are allowing InPost to capture outsized parcel volume growth and extend its out-of-home leadership, supporting sustained double-digit revenue growth and operating leverage.
See why 25 investors see InPost as 11% undervalued.
Result: Fair Value of €17.28 (UNDERVALUED)
Still, rising competition for parcel volumes and the heavy investment load around Yodel and other acquisitions could quickly challenge the upbeat narrative around InPost.
Find out about the key risks to this InPost narrative.
Another View on InPost’s Valuation
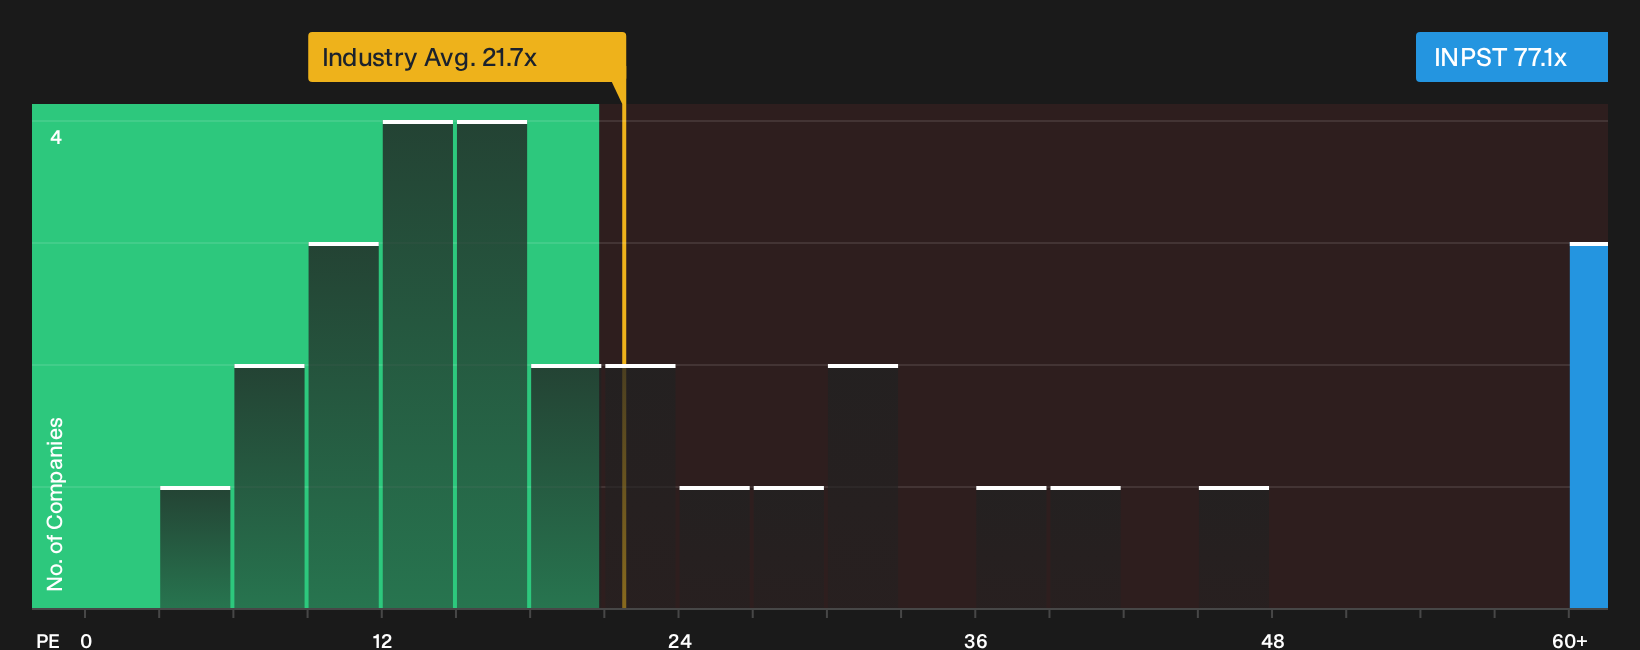
On price alone, InPost tells a very different story. The shares trade on a P/E of 77.1x, which is far above the European Logistics average of 21.9x, well above the peer average of 12.8x, and almost double the fair ratio of 39.1x. This raises the question of how much optimism is already baked in.
To see how that premium lines up with the underlying numbers, take a closer look at the valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or quiet conviction around InPost; either way this is the moment to test the numbers yourself and see where you land. To weigh up the bright spots against the pressure points in one place, start with the 1 key reward and 2 important warning signs.
Looking for more ideas beyond InPost?
If InPost has sharpened your focus, use that momentum to scan other opportunities now, rather than waiting for the next headline to move first.
- Chase underappreciated quality by checking companies on the 184 high quality undervalued stocks.
- Prioritise resilience and capital strength through the list of solid balance sheet and fundamentals (207 results).
- Target consistency and lower volatility profiles with the 225 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com