
InterDigital (IDCC) Dividend News Puts Its Undervalued Narrative To The Test
Dividend announcement puts InterDigital in focus
InterDigital (IDCC) has declared a US$0.75 cash dividend with an ex dividend date of October 14, 2026, prompting renewed attention on how the stock rewards shareholders today.
Recent trading has been choppy for InterDigital, with a 1-day share price decline of 2.5% but a 90-day share price return of 24.23%. The 1-year total shareholder return is down 4.94%, and the 5-year total shareholder return is up more than 4x. This suggests momentum has cooled in the short term after a strong multi year run as investors weigh this new dividend against existing expectations.
Scan how InterDigital’s dividend move compares with other income ideas by reviewing a hand picked group of 8 dividend fortresses across the market.
Bulls point to InterDigital’s long licensing reach and fresh income stream, while bears focus on a softer 1 year return after a multi year surge. Which side does the current valuation actually support next?
Most Popular Narrative: 29% Undervalued
InterDigital’s most followed narrative pegs fair value around $462.67 per share, which sits well above the last close at $330.80, so the current dividend is landing on a stock that narrative followers see as underpriced on their long range assumptions.
The shift in InterDigital’s licensing mix toward streaming and cloud video services, supported by the Amazon agreement that currently recognizes revenue on a conservative estimate during arbitration, leaves scope for higher recurring revenue and earnings if the final award comes in above the booked level.
See why 20 investors see InterDigital as 29% undervalued.
Result: Fair Value of $462.67 (UNDERVALUED)
Still, the bullish InterDigital story leans heavily on the Amazon arbitration outcome and on keeping enforcement costs in check, which could both pressure earnings if they break the current script.
Find out about the key risks to this InterDigital narrative.
Another View: InterDigital’s P/E Sends A Different Signal
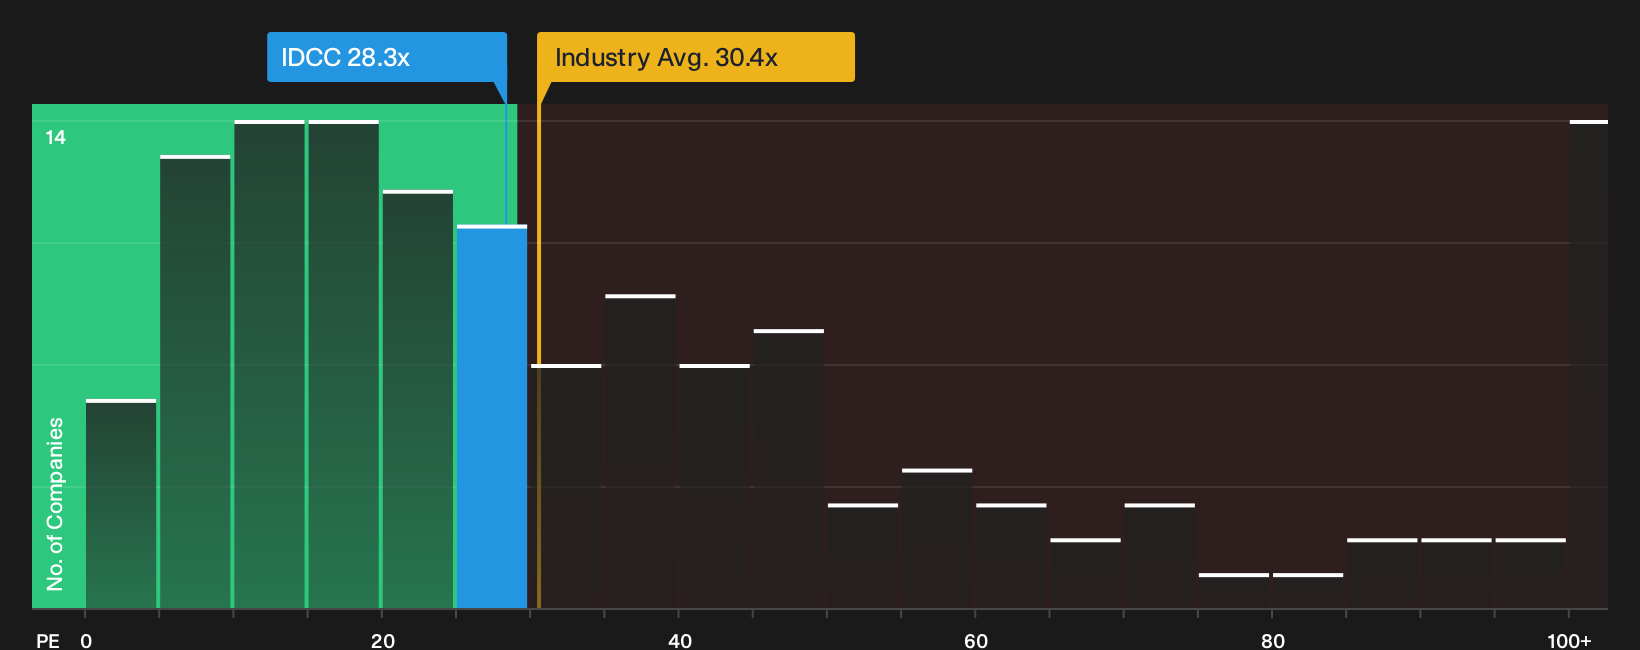
InterDigital’s most popular narrative frames the stock as 29% undervalued, yet the SWS P/E work paints a more cautious picture. The current P/E of 28.3x sits below the US Software group at 30.4x and well under peers at 45.7x, but above the 25.3x fair ratio.
That gap means the share price already bakes in richer expectations than the fair ratio suggests the market could move toward, even if it still looks cheaper than many software peers. For anyone weighing the dividend and the bullish story, this may be either a margin of safety or a valuation stretch that could limit upside if growth underwhelms.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on InterDigital’s dividend and valuation can pull you in both directions, so move quickly to review the data and frame your own stance, then weigh those findings against the 3 key rewards.
Looking for more InterDigital style investment ideas?
If you only stop at InterDigital, you risk missing other opportunities that better fit your goals, risk tolerance, and income needs across the market.
- Target resilient compounding potential by scanning a 29 high quality undervalued stocks that may offer stronger upside relative to current market expectations.
- Prioritise sleep at night stability by reviewing a 31 resilient stocks with low risk scores that focuses on resilience when conditions get uncomfortable.
- Spot tomorrow’s potential leaders early by checking a 20 high quality undiscovered gems that filters for quality fundamentals before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com