
Did Private Credit Model Launch Just Shift Moody's (MCO) Investment Narrative?
- Moody’s and Allvue Systems recently launched the Moody’s Analytics EDF-X Private Credit Model, a forward looking tool built on de-identified private credit performance data to flag early borrower stress across a market that Moody’s projects could approach US$4b by 2030.
- The model separately tracks soft warning signs such as covenant waivers and payment in kind arrangements before hard credit events, which could make Moody’s analytics more embedded in how private lenders monitor portfolios, evaluate managers and allocate capital.
- We will now examine how Moody’s push into private credit specific risk analytics could reshape the broader investment narrative around the company.
Scan how Moody's move into private credit risk analytics compares with other lenders sharpening their toolkits by reviewing the curated list of solid balance sheet and fundamentals (25 results).
Moody's Investment Narrative Recap
To back Moody’s as a shareholder, you really need to believe the firm can keep growing high margin analytics and ratings while integrating its data more tightly into client workflows. The EDF-X Private Credit Model fits that story but does not change the near term swing factor, which remains issuance levels and demand for risk tools.
The biggest operational risk still sits in a potential cooldown after strong recent activity and in whether Moody’s Analytics unit economics match expectations as disclosure improves. A high debt load and heavy capital return ambitions add another pressure point if cash generation or restructuring benefits fall short.
The EDF-X Private Credit Model launch is the clearest recent announcement tied to existing catalysts. It leans directly into rising interest in private credit tools and builds on Moody’s push to get decision grade analytics embedded inside client systems rather than sold as standalone reports.
This kind of product also lines up with the firm’s AI and workflow integrations with large cloud providers. Execution risk is practical rather than conceptual. Moody’s needs to scale adoption across Allvue’s user base, prove the model’s usefulness in portfolio monitoring and manager evaluation, and show that this translates into durable, recurring Analytics revenue.
What The Current Moody's Consensus Is Really Asking You To Believe
Moody's narrative projects US$9.8b revenue and US$3.5b earnings by 2029. That rests on analysts baking in 6.4% yearly revenue growth and an earnings increase of about US$700m from US$2.8b today.
Uncover why Moody's fair value indicates a 25% potential upside to its current price that could narrow quickly.
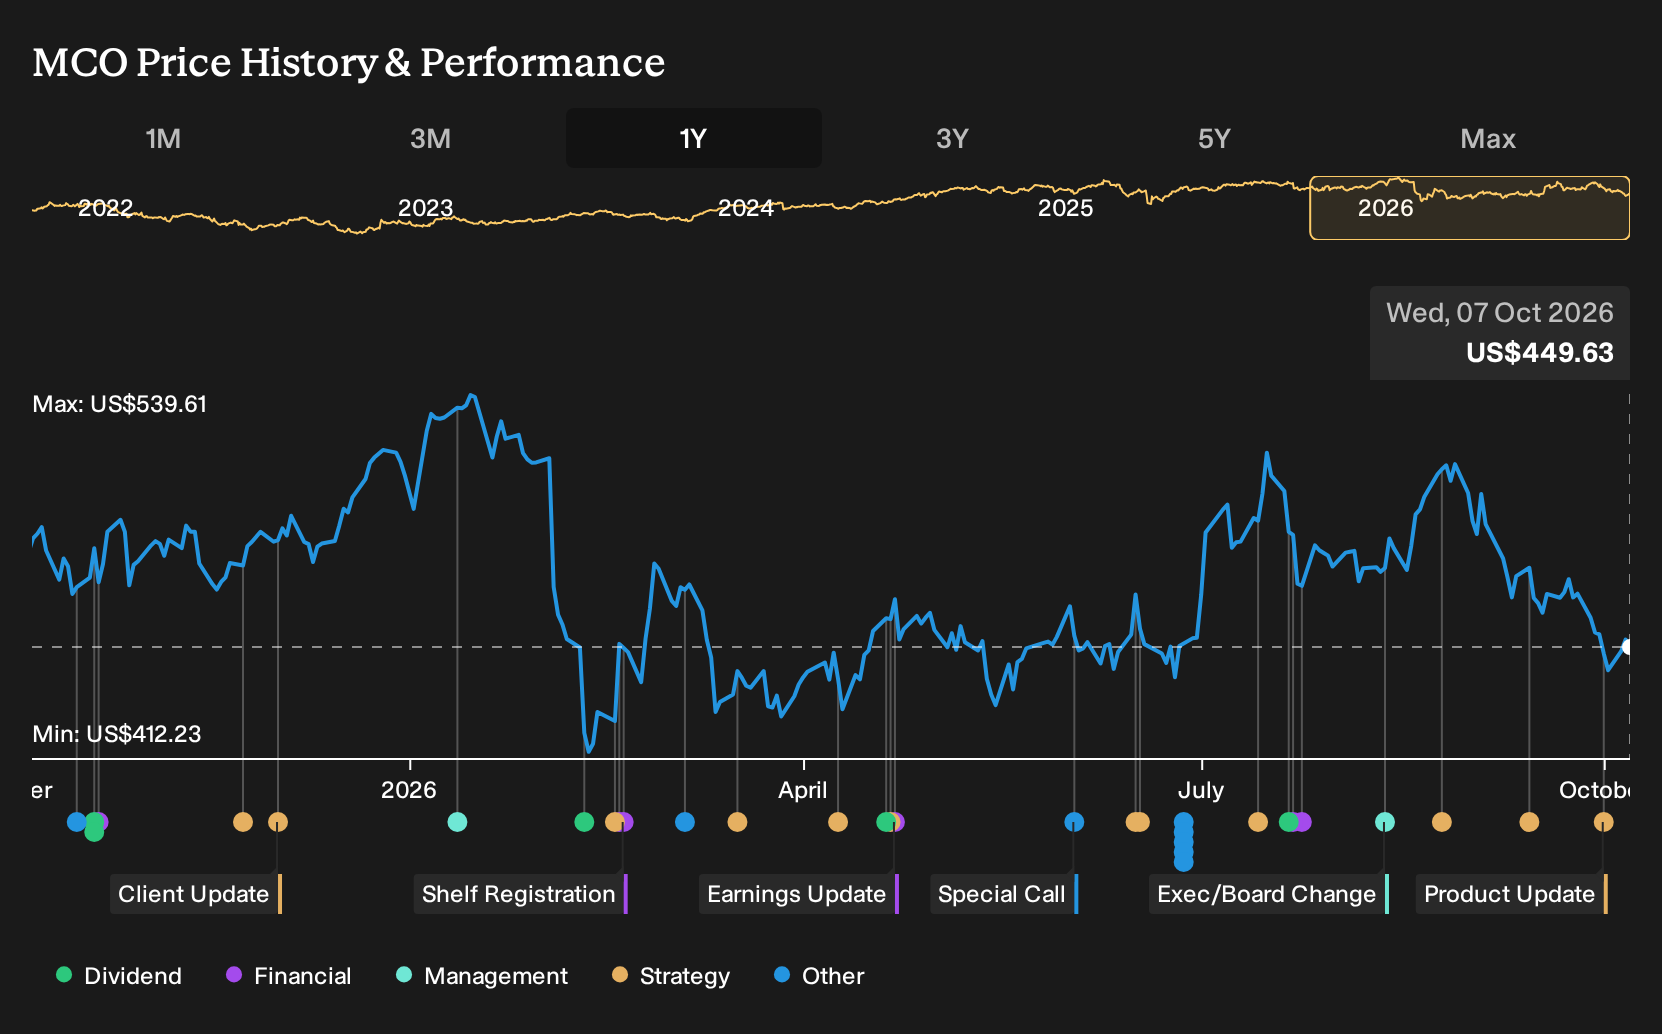
Exploring Other Perspectives
Eight fair value views from the Simply Wall St Community put Moody’s between about US$428 and US$562, with some contributors seeing far richer upside than others. These opinions do not yet factor in the new private credit model or the private credit transaction momentum, so treat them as a baseline and explore how your own expectations differ.
Explore 7 other Moody's fair value estimates, including one that suggests as much as 25% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Moody's research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Moody's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Moody's overall financial health at a glance.
Looking For More Ideas Beyond Moody's?
If you want to stress test your thesis on Moody's and see how it stacks up against other opportunities, the Simply Wall St Screener helps you scan the wider market through different lenses and filter down to a watchlist that fits your own risk and return preferences.
- If you care most about quality at a reasonable entry point, compare Moody's to companies flagged as potential value opportunities using our 29 high quality undervalued stocks.
- For investors who prefer resilience and lower downside risk, weigh Moody's against a 31 resilient stocks with low risk scores that have more stable profiles.
- If capital strength and cleaner financial structures matter most to you, round out your research by checking a list of solid balance sheet and fundamentals (25 results) that could complement or compete with Moody's in your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com