
European Stock Picks That May Offer Value In October 2026
As European equities face volatility due to elevated oil prices and rising sovereign bond yields, investors are keenly observing the market for potential value opportunities amid concerns over inflation and restrictive monetary policies. In this environment, identifying undervalued stocks becomes crucial, as these may offer a chance to capitalize on market fluctuations while navigating the broader economic uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| XTB (WSE:XTB) | PLN135.00 | PLN266.63 | 49.4% |
| Valmet Oyj (HLSE:VALMT) | €26.64 | €52.68 | 49.4% |
| PORR (WBAG:POS) | €30.05 | €59.76 | 49.7% |
| Orthex Oyj (HLSE:ORTHEX) | €4.57 | €8.89 | 48.6% |
| Lindab International (OM:LIAB) | SEK125.30 | SEK250.27 | 49.9% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €11.56 | €22.65 | 49% |
| Huuuge (WSE:HUG) | PLN23.40 | PLN45.85 | 49% |
| Grupa Pracuj (WSE:GPP) | PLN54.80 | PLN108.49 | 49.5% |
| Erste Group Bank (WBAG:EBS) | €110.60 | €219.96 | 49.7% |
| Apator (WSE:APT) | PLN25.90 | PLN49.19 | 47.3% |
Here we highlight a subset of our preferred stocks from the screener.
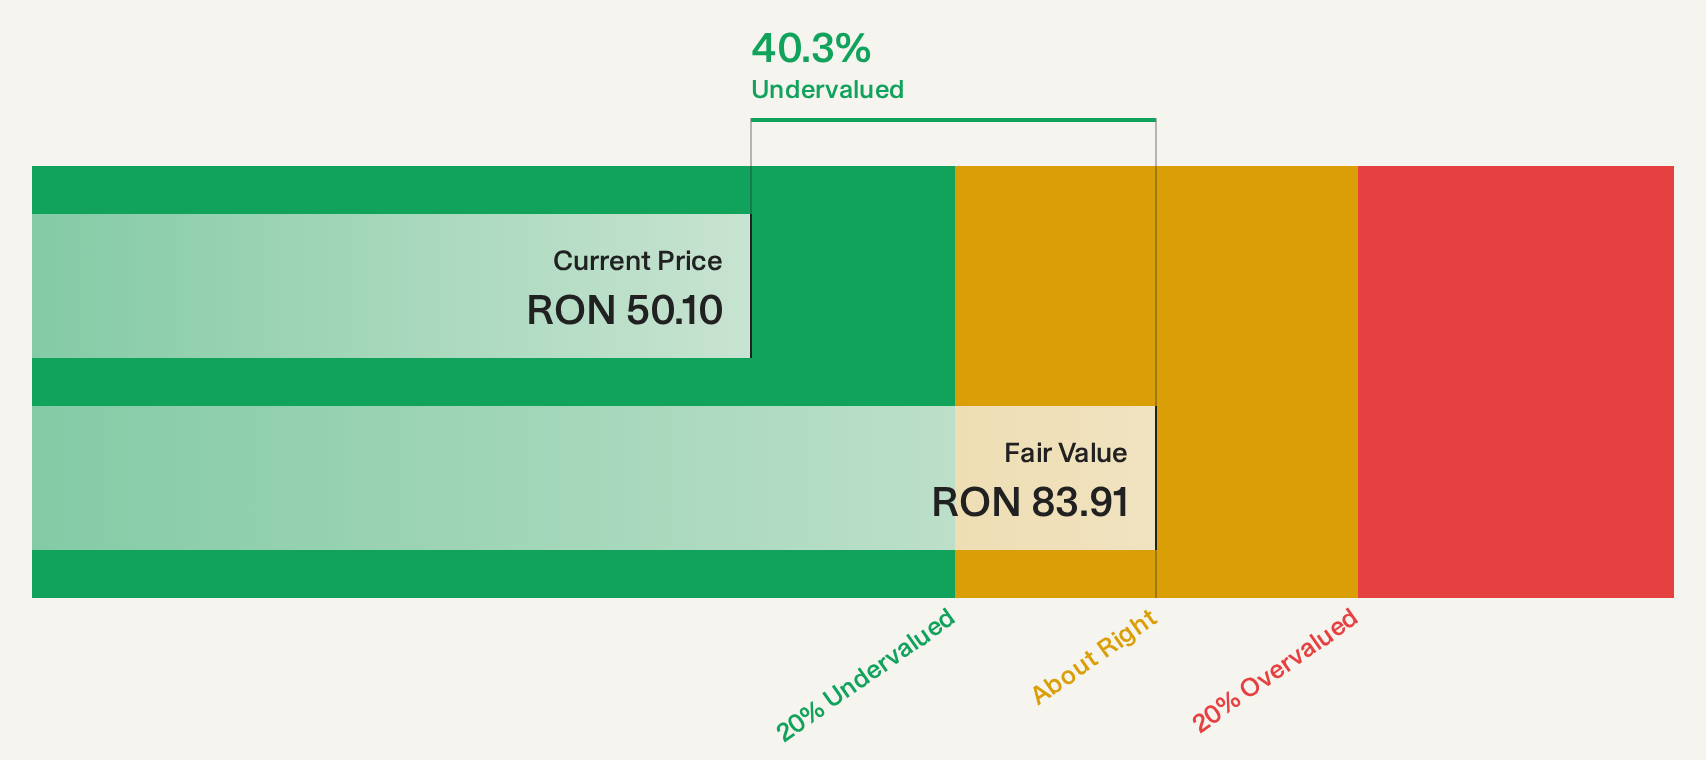
Societatea Energetica Electrica (BVB:EL)
Overview: Societatea Energetica Electrica S.A., along with its subsidiaries, operates in the construction and maintenance of electricity distribution networks in Romania, with a market cap of RON17.25 billion.
Operations: The company generates revenue primarily from Electricity and Natural Gas Supply (RON8.89 billion), Electricity Distribution (RON5.34 billion), External Electricity Network Maintenance (RON85.11 million), and Electricity Generation (RON21.06 million).
Estimated Discount To Fair Value: 39.5%
Societatea Energetica Electrica appears undervalued based on discounted cash flow analysis, trading significantly below its estimated future cash flow value. Despite recent earnings growth and a promising cogeneration plant project in Craiova, revenue and earnings growth forecasts remain modest compared to the Romanian market. The company faces challenges with high debt levels but offers good relative value within its industry. Recent projects align with long-term decarbonization strategies, potentially enhancing future operational efficiency.
- Our earnings growth report unveils the potential for significant increases in Societatea Energetica Electrica's future results.
- Get an in-depth perspective on Societatea Energetica Electrica's balance sheet by reading our health report here.
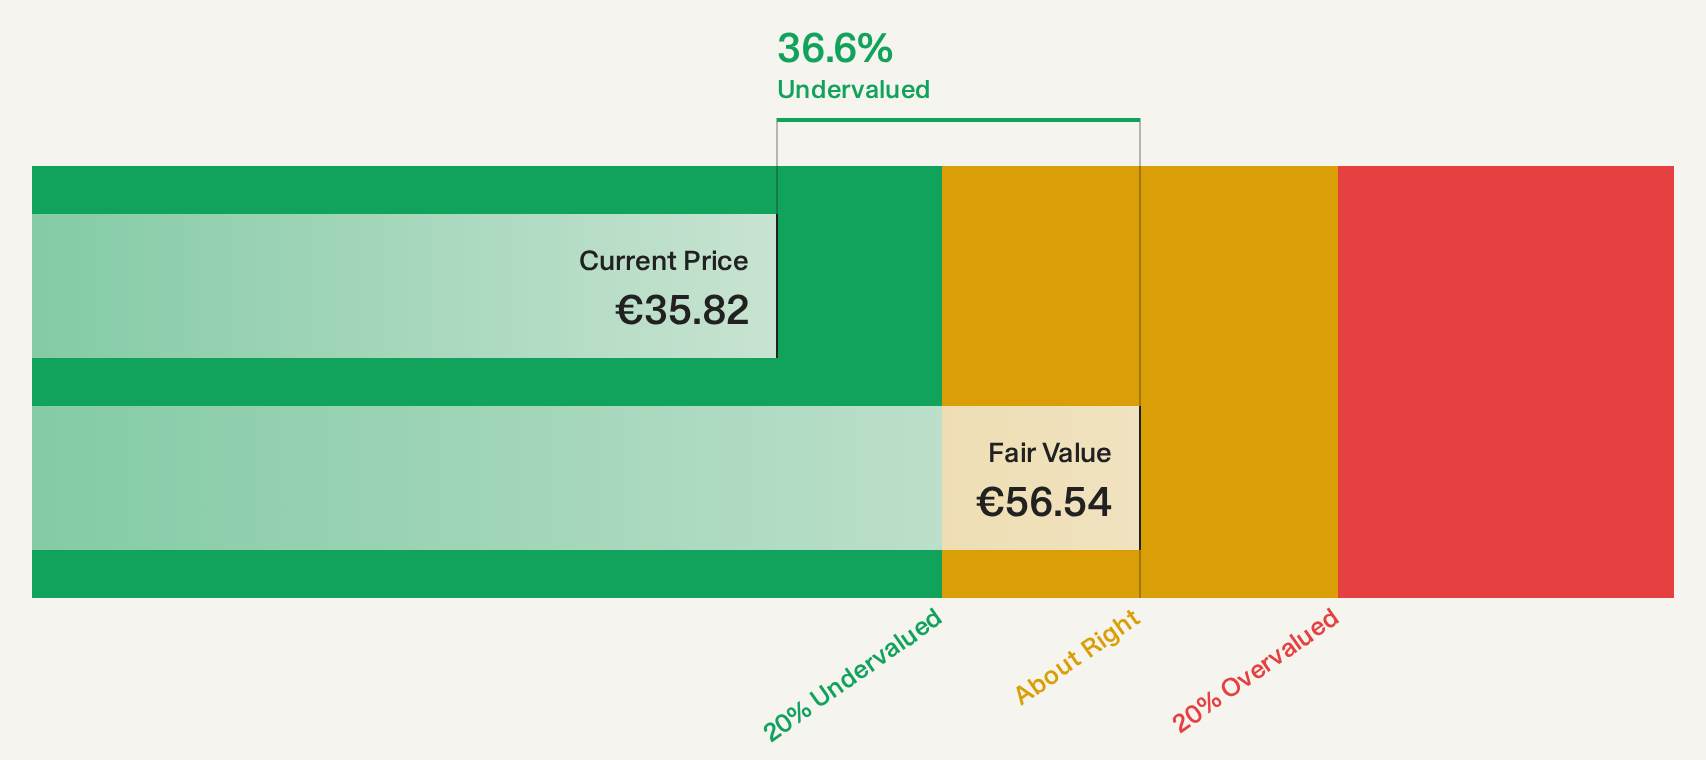
SBM Offshore (ENXTAM:SBMO)
Overview: SBM Offshore N.V. provides floating production solutions to the offshore energy industry worldwide and has a market capitalization of €5.82 billion.
Operations: The company's revenue is derived from two main segments: Turnkey, which generated $3.17 billion, and Lease and Operate, which contributed $2.68 billion.
Estimated Discount To Fair Value: 37.8%
SBM Offshore is trading significantly below its estimated future cash flow value, with a share price of €34.94 against a projected value of €56.19. Despite recent earnings growth and a completed buyback tranche worth €99.88 million, revenue and earnings are forecast to decline over the next three years, contrasting with the Dutch market's growth expectations. The company maintains high debt levels but offers good relative value compared to peers and industry standards.
- Upon reviewing our latest growth report, SBM Offshore's projected financial performance appears quite optimistic.
- Take a closer look at SBM Offshore's balance sheet health here in our report.
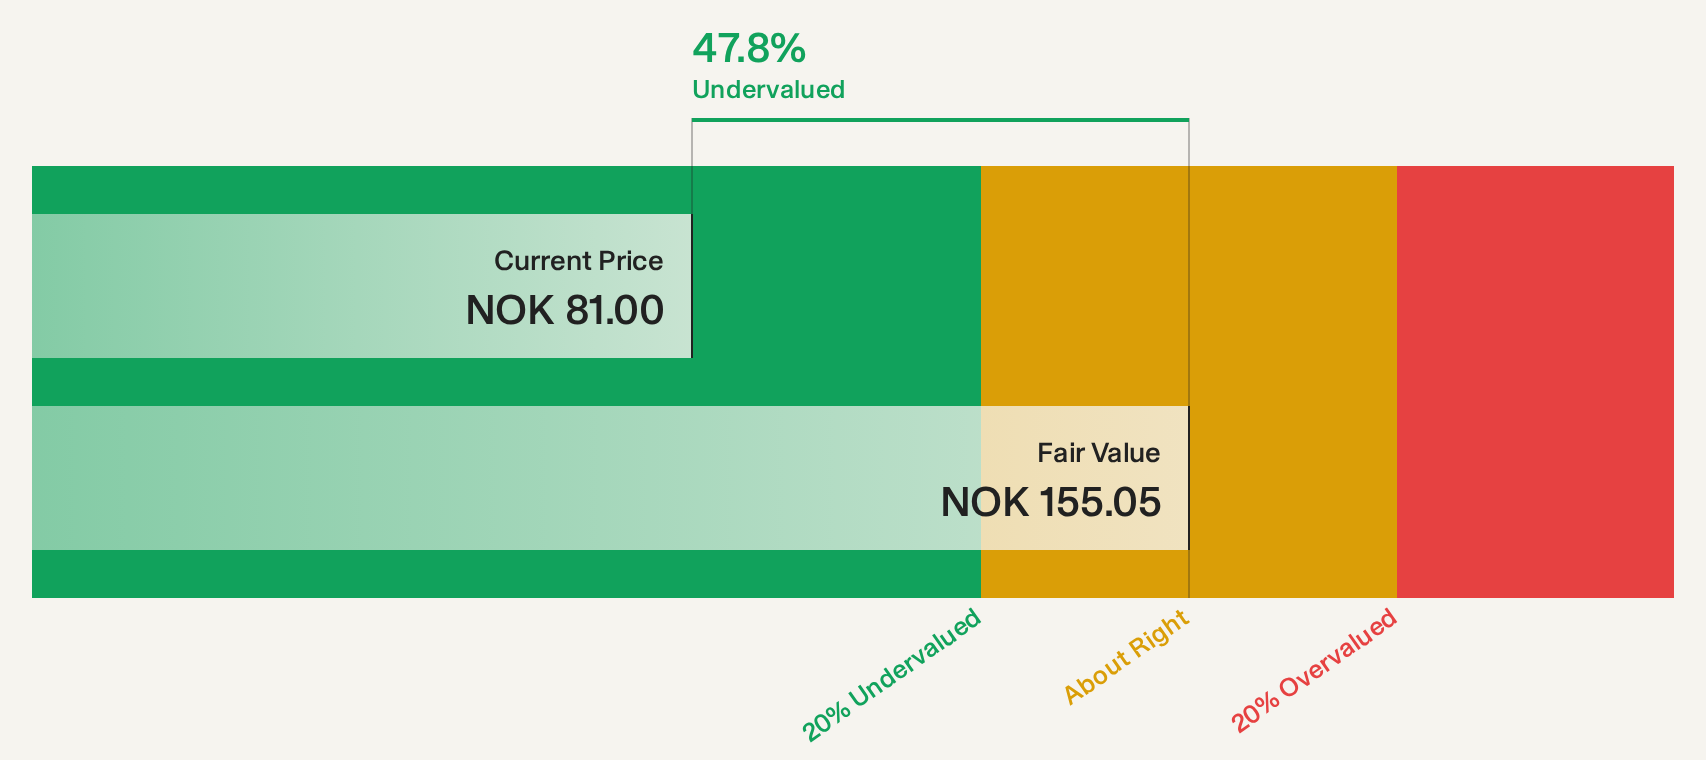
Sentia (OB:SNTIA)
Overview: Sentia ASA, along with its subsidiaries, operates in the construction industry in Norway and Sweden with a market cap of NOK8.41 billion.
Operations: The company's revenue is derived from its operations in HENT, which generated NOK9.73 billion, and Sentia Sweden, contributing NOK2.84 billion.
Estimated Discount To Fair Value: 45.9%
Sentia ASA is trading at a significant discount to its estimated future cash flow value, with a share price of NOK 83.4 against an estimated value of NOK 154.3. Recent earnings growth was strong, but future profit growth is expected to lag behind the Norwegian market average. Revenue projections are more promising, outpacing local market expectations. The company's dividend yield of 6.59% is not well covered by earnings, and recent executive changes may impact financial strategy moving forward.
- The analysis detailed in our Sentia growth report hints at robust future financial performance.
- Click here to discover the nuances of Sentia with our detailed financial health report.
Summing It All Up
- Navigate through the entire inventory of 65 Undervalued European Stocks Based On Cash Flows here.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com