
Snap (SNAP) Could Be 21% Undervalued On Specs Funding Push
Shareholder pressure has moved back onto Snap (SNAP) after hedge fund Blue Duck Capital Partners urged the company to sell a minority stake in its Specs augmented reality glasses unit to raise dedicated external funding.
Snap’s recent trading has been choppy. The share price is at US$5.81 after a 7.59% 7-day share price return and a 23.62% 90-day share price return, yet total shareholder return over five years has declined 92.25%. This signals pressure despite short term momentum building around moves like the proposed Specs funding push.
Spot potential re-ratings beyond Snap by scanning a curated group of 20 high quality undiscovered gems with stronger long-term share price resilience than this 5-year drawdown suggests.Snap is back in the spotlight after the Specs push, yet the shares still sit on a steep five year drawdown. Does it make more sense to lean in at US$5.81 or wait for a cheaper entry as the valuation stacks up next?
Most Popular Narrative: 21% Undervalued
On the most followed narrative, Snap’s fair value estimate of about $7.33 sits above the recent $5.81 close. This puts the Specs funding debate in the shadow of a wider long term valuation gap.
Accelerating innovation in augmented reality (AR), including the upcoming public launch of Specs AR glasses in 2026 and continuous expansion of the AR developer ecosystem, positions Snap to benefit from both increased user engagement and the creation of premium advertising and subscription revenue streams, which can boost top-line revenue and improve gross margins over time.
See why 71 investors see Snap as 21% undervalued.
Result: Fair Value of $7.33 (UNDERVALUED)
Still, the bullish Snap narrative can unravel quickly if digital ad competition keeps squeezing its share of budgets or if Specs adoption remains slower than hoped.
Find out about the key risks to this Snap narrative.
Another View On Snap’s Valuation
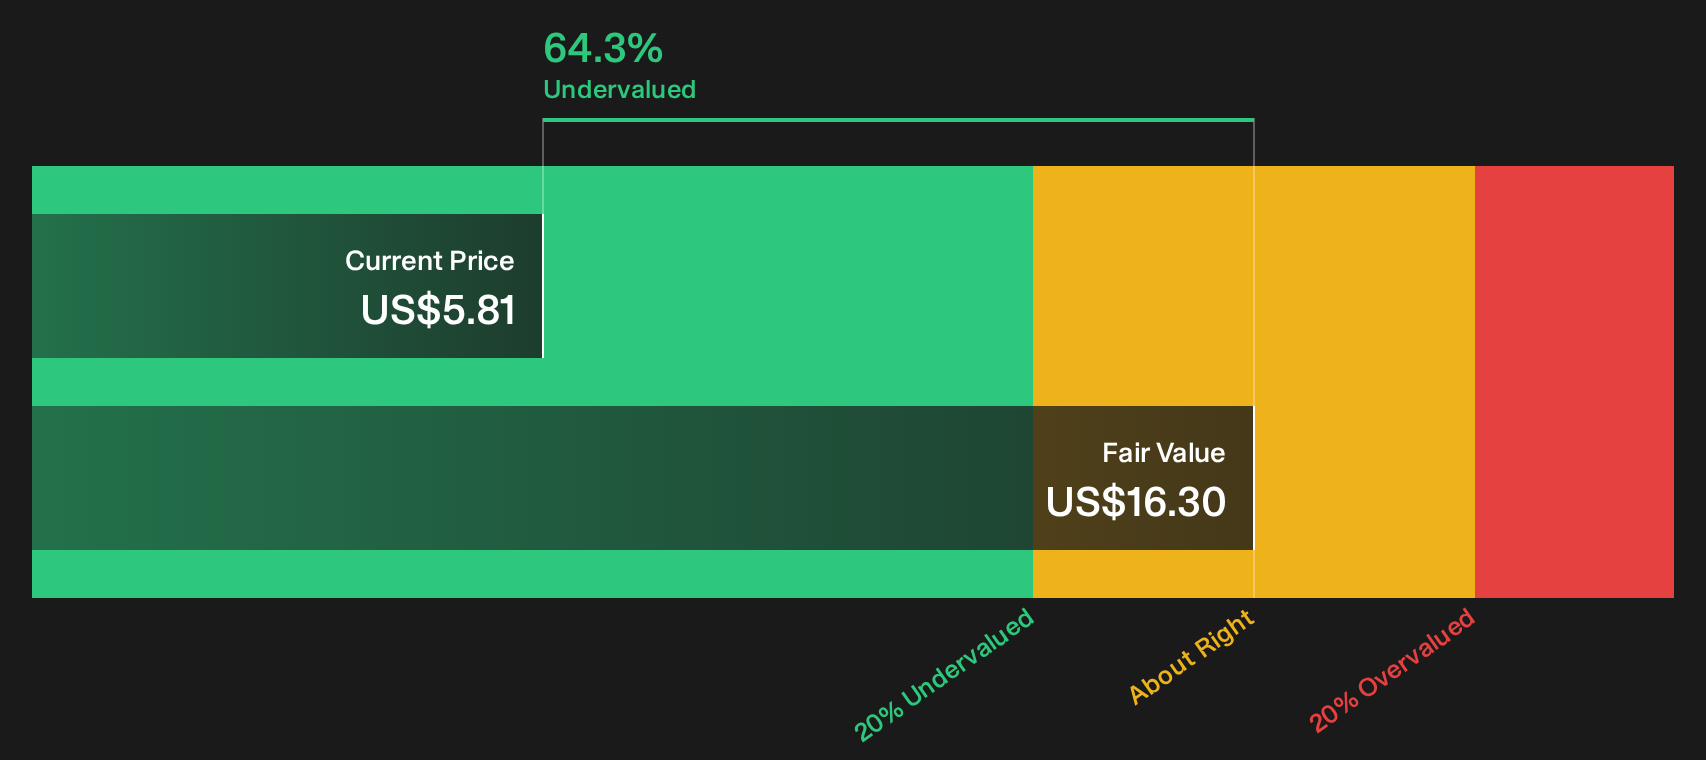
The DCF narrative pins Snap’s fair value around $7.33, yet our SWS DCF model flags a much larger gap, with the shares trading 64.3% below an estimated future cash flow value of $16.30. If both signals are pointing to undervalued, the key question is how comfortable you are with the assumptions that support each model.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Snap’s valuation and Specs funding can feel messy, so move quickly, examine both the upside and downside drivers, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Snap?
If Snap has you weighing upside against risk, do not stop there. Use targeted screeners to spot other opportunities that better match your goals.
- Target potential mispricing by reviewing a focused group of 29 high quality undervalued stocks that combine strong fundamentals with price tags that may not fully reflect their underlying business strength.
- Protect the downside first by checking a curated set of 31 resilient stocks with low risk scores where balance sheets and risk scores aim to keep surprises in check.
- Get ahead of the crowd by scanning a tight group of 12 elite penny stocks with strong financials that pair smaller market caps with stronger financial profiles than many peers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com