
SHEIN Global Holdings (SEHK:625) Earnings Put Valuation In Focus, Is The Stock Still Cheap?
Earnings jolt puts SHEIN Global Holdings in focus
SHEIN Global Holdings (SEHK:625) has jumped onto investor radars after half year 2026 results showed sales of US$20.134b and net income of US$2.299b, compared with US$19.940b and US$1.086b a year earlier.
SHEIN Global Holdings now trades at HK$32.94, with the 7 day share price return up 6.81% but the 30 day share price return down 16.27% and the year to date share price return down 32.08%. This points to short term momentum improving while longer term performance remains weak as investors reassess both growth potential and risk after the earnings release.
Scan how SHEIN Global Holdings compares with other fashion and e-commerce plays under pressure by running through the hand picked 619 high quality undiscovered gems list.
The recent rebound in SHEIN Global Holdings after mixed longer term returns leaves a blunt question: Are you seeing a reset in sentiment, or a price that now better reflects the underlying business when you look at valuation next?
Preferred P/E of 5.4x for SHEIN Global Holdings: Is it justified?
SHEIN Global Holdings now carries a P/E of 5.4x, which looks low beside both the wider Hong Kong market at 10.7x and the Specialty Retail group at 8.9x. That gap indicates the share price is not being set on an aggressive earnings multiple compared with local peers.
The P/E ratio compares what you pay for each unit of profit to what the company currently earns. For a fashion and e commerce platform like SHEIN Global Holdings, this yardstick is often used as a quick check on how the market is weighing current profitability against forecast earnings trends, especially when analyst expectations point to pressure on the bottom line.
Here, the picture is mixed. On one side, the business recorded revenue growth of 4.4% over the past year and net profit margins of 7.8% that were higher than the previous 6.8%, which supports the idea of stronger recent profitability. On the other, earnings are forecast to decline by an average of 11.7% per year over the next 3 years, and those same forecasts call for revenue growth of 5.2% per year, slower than the Hong Kong market at 9.1%. That combination helps explain why the market assigns a lower earnings multiple, even though the current P/E sits beneath both the market and sector averages.
Compared with the Hong Kong Specialty Retail industry, the discount is clear. SHEIN Global Holdings trades on a P/E of 5.4x while the sector average stands at 8.9x. The stock also prices below the wider Hong Kong market P/E of 10.7x. That suggests investors are applying a cheaper earnings tag than both direct peers and the broader market.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 5.4x (UNDERVALUED).
Still, the narrative around SHEIN Global Holdings can shift quickly if projected earnings pressure continues or if fashion demand on its online platform softens.
Find out about the key risks to this SHEIN Global Holdings narrative.
Another view on SHEIN Global Holdings’ value
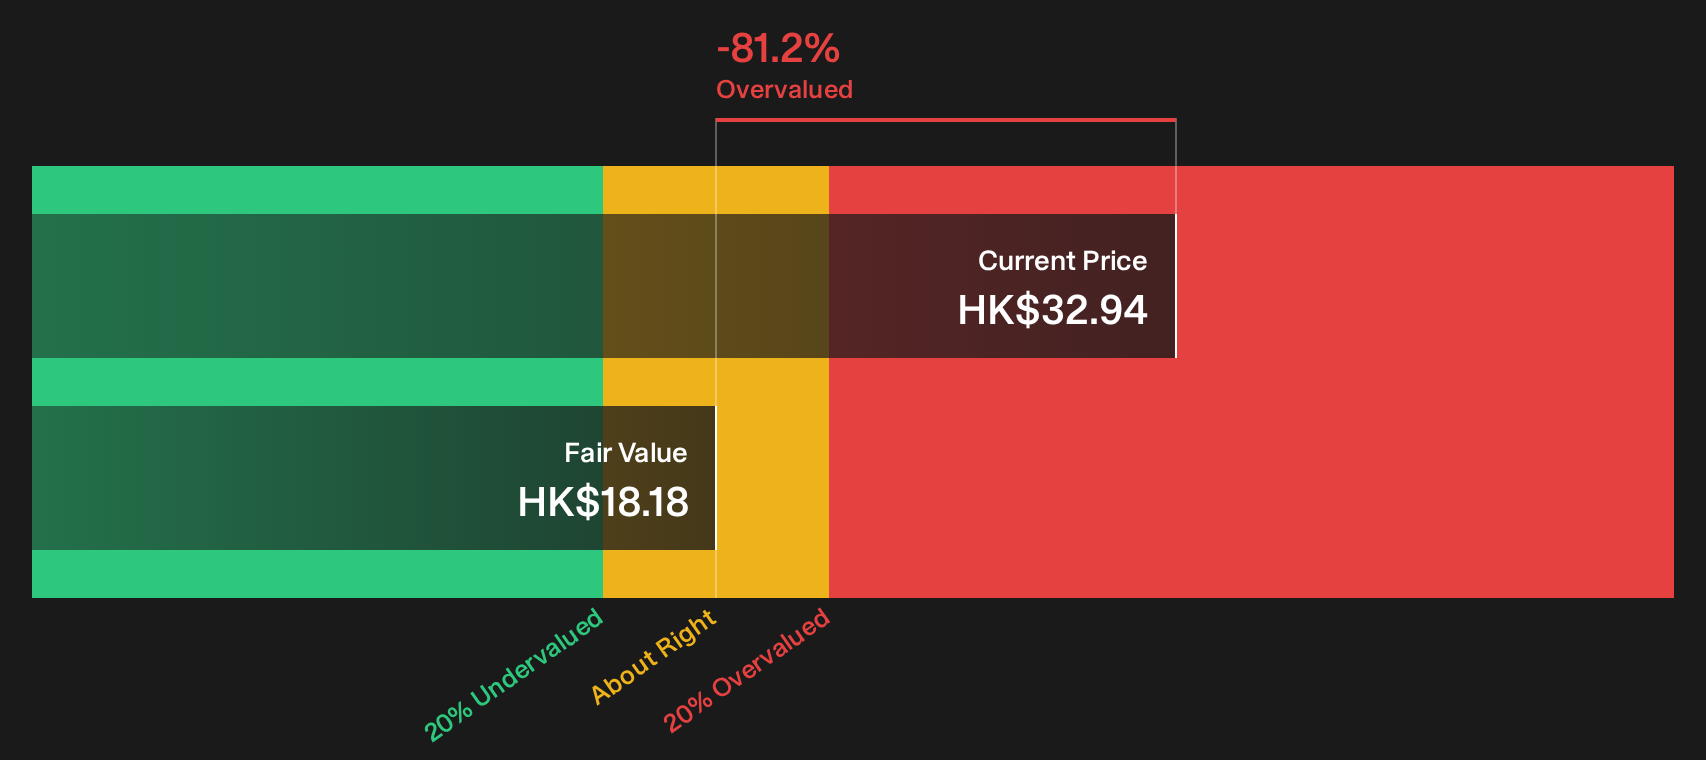
The earlier P/E check paints SHEIN Global Holdings as inexpensive. A different lens tells a tougher story. The SWS DCF model estimates future cash flows at about HK$18.18 per share, while the market price sits at HK$32.94, which screens as overvalued on this approach.
That is a wide gap for investors to weigh, especially with earnings forecast to decline by an average of 11.7% per year. Does this reflect excessive pessimism in the cash flow model, or is the low P/E simply not capturing balance sheet and cash flow pressure yet?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SHEIN Global Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around SHEIN Global Holdings often leave sentiment split, so move quickly, review the data and shape your own take using the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond SHEIN Global Holdings?
Do not stop with SHEIN Global Holdings. Put the same discipline to work on fresh ideas, or risk missing companies that better match your goals and risk tolerance.
- Target potential mispricing by scanning the 184 high quality undervalued stocks that pair solid fundamentals with more modest expectations embedded in the share price.
- Focus on resilience first and see which businesses pass the 225 resilient stocks with low risk scores with steadier earnings profiles and cleaner balance sheets.
- Prioritise financial strength by running through the list of solid balance sheet and fundamentals (207 results) that combine lower leverage with healthy cash positions and consistent funding flexibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com