
Kyushu Railway (TSE:9142) Could Be 55% Above Fair Value After Its Pullback
Kyushu Railway (TSE:9142) drew fresh attention after its recent close at ¥3,351, as investors weighed the stock’s one-month and past three-month declines against its longer multi-year total return record.
Recent trading has been heavy on hesitation, with Kyushu Railway’s share price down 5.4% over the past month and 17.9% year to date, while the 5 year total shareholder return of 50.1% points to momentum that has eased rather than reversed.
Scan beyond Kyushu Railway and consider other transport and infrastructure plays that screen for value and balance sheet strength using our curated list of solid balance sheet and fundamentals (23 results)
For Kyushu Railway, the pullback to ¥3,351 raises a simple tension: Is this already a fair entry after a weaker year, or does waiting for an even lower valuation make more sense before committing fresh capital?
Price-to-Earnings of 11.5x: Is it justified?
On simple earnings terms, Kyushu Railway is trading on a P/E of 11.5x, which places the current ¥3,351 share price at a level that screens as relatively modest compared with both its peers and the wider Japanese market.
The P/E ratio compares what investors pay for each unit of net profit, so a P/E of 11.5x for a transport and infrastructure focused group like Kyushu Railway can help you gauge how the market is weighing its earnings power against other listed businesses.
Against the JP Transportation industry average of 11.7x, this stock changes hands at a slightly cheaper earnings multiple. Compared with the broader JP market on 14x, the discount is clearer. This implies the market is assigning a lower price tag than the 14.4x fair P/E level that regression analysis suggests it could move toward if sentiment and fundamentals line up.
Explore the SWS fair ratio for Kyushu Railway.
Result: Price-to-Earnings of 11.5x (UNDERVALUED)
Still, Kyushu Railway faces narrative risks if its revenue growth of 4.0% and net income growth of 2.6% slow, or if domestic transport demand weakens further.
Find out about the key risks to this Kyushu Railway narrative.
Another View on Kyushu Railway’s Value
The P/E points to Kyushu Railway looking inexpensive, yet the SWS DCF model paints a stricter picture. On that cash flow view, the estimated value sits at ¥2,158.55 per share, which leaves the current ¥3,351 level screening as overvalued rather than cheap.
That kind of gap can reflect different expectations around future cash generation or required returns. It puts the onus back on you. Do you trust the earnings-based snapshot more, or does the cash flow math carry more weight for your next move?
Look into how the SWS DCF model arrives at its fair value.
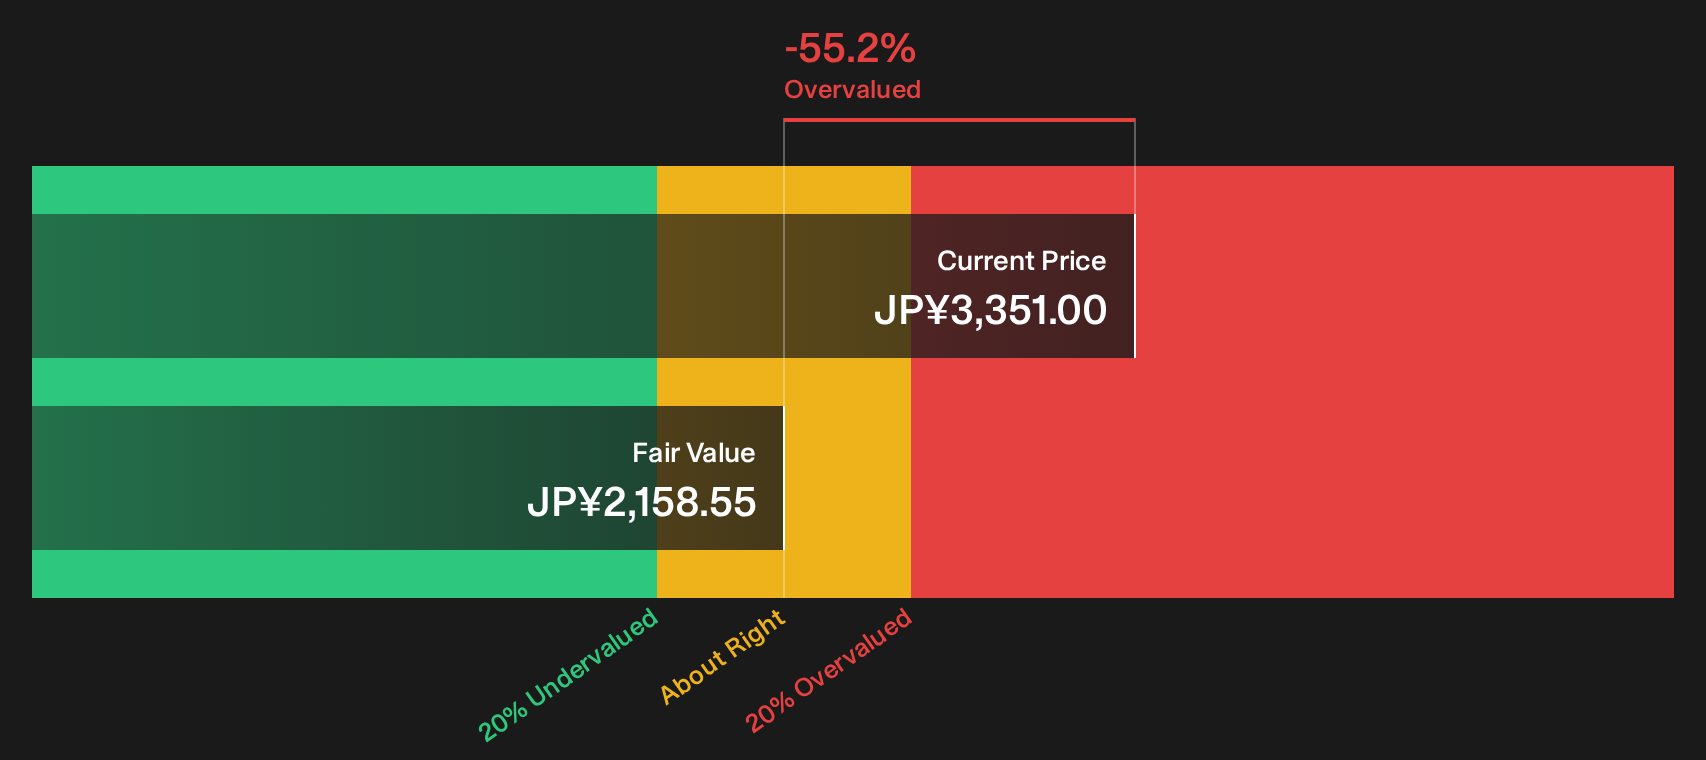
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kyushu Railway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear message, either way the sooner you dig into the data, the sooner you can decide where you stand on Kyushu Railway. To weigh both sides of the story in one place, start with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kyushu Railway?
Sticking with a single stock can leave you exposed, so widen your options now and tap into fresh ideas that your future self may thank you for.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that filters for financial strength before anything else.
- Hunt for quality at a reasonable price and surface opportunities that may trade below their implied worth with the focused 15 high quality undervalued stocks.
- Prioritise cash returns and recurring income potential by reviewing companies that feature in the yield focused 28 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com