
Is Five Below (FIVE) A Bargain As Strong Earnings And Guidance Lift The Stakes?
Market reaction and valuation context
Five Below (FIVE) just delivered a quarterly double beat that caught investor attention, with revenue growth near 23% and earnings growth near 110% off the back of stronger comparable sales and rapid store openings.
Management also raised its FY26 sales and EPS outlook for a second straight quarter. This puts the recent share move and valuation into sharper focus for anyone tracking the stock after this report.
Five Below’s latest update lands after a choppy few weeks, with the share price down 19.02% over the past 30 days and 6.98% over the last week, even though the 90 day share price return of 10.85% and 1 year total shareholder return of 32.83% point to momentum that has mostly been building rather than fading.
Seize this earnings momentum in Five Below and compare it against a curated group of value focused opportunities using our 29 high quality undervalued stocks as a starting universe.The share price has slid while analyst targets and intrinsic estimates point much higher. For Five Below, is fair value closer to the recent print or the upper end of that range?
Most Popular Narrative: 34% Undervalued
Five Below’s most followed narrative anchors fair value at $310.48 per share, which is well above the last close near $204. The story therefore hinges on how fully the rollout and reinvestment plan can translate into durable earnings power.
The decision to direct the roughly $170 million in tariff refunds and a sizeable cash balance of about $1.2 billion toward investments in in store experience, digital and product development, alongside a new $600 million share repurchase authorization, can support future revenue and earnings while potentially increasing per share earnings through a lower share count.
See why 15 investors see Five Below as 34% undervalued.
Result: Fair Value of $310.48 (UNDERVALUED)
Still, the Five Below story can crack if fuel and trucking costs continue to pressure margins or if ongoing legal disputes translate into heavier, persistent expenses.
Find out about the key risks to this Five Below narrative.
Another view on Five Below’s valuation
The big narrative around Five Below leans on a fair value of $310.48 per share, yet the SWS DCF model points in the opposite direction. On that cash flow view, the stock around $204 trades above an estimated value of $173.19, which implies less upside and more valuation risk if cash generation disappoints.
That kind of split between a narrative fair value and a lower cash flow estimate leaves you with a simple question: Which story do you trust more, the earnings path implied by analyst targets or the cash actually expected to come in the door over time?
Look into how the SWS DCF model arrives at its fair value.
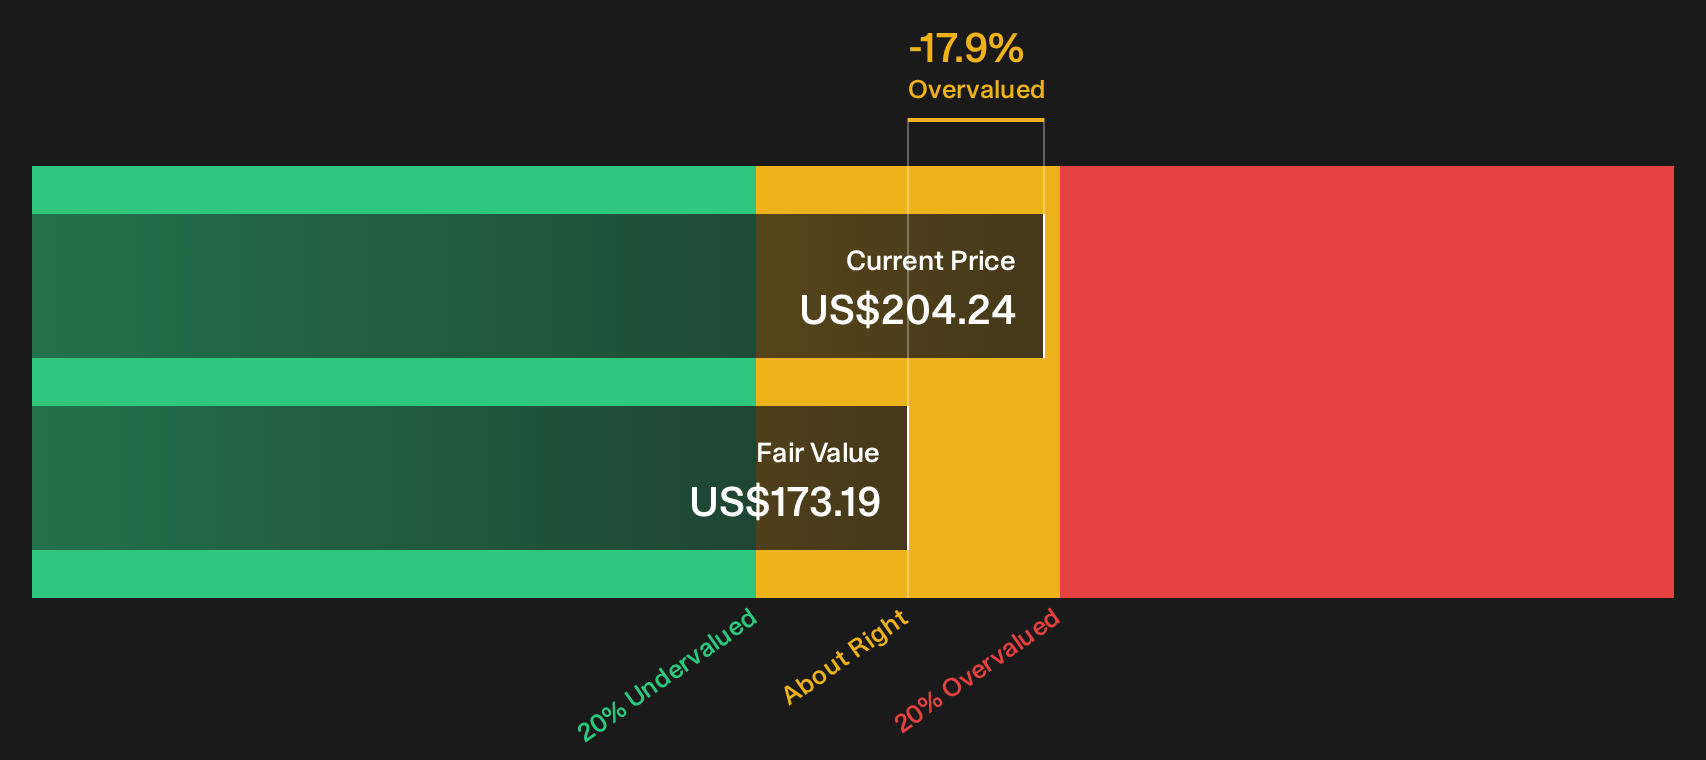
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Five Below for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data can be a gift if you move quickly and test the narrative against the numbers yourself. To weigh Five Below’s potential against the caution flags, start by reviewing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Five Below?
Do not stop with one stock. Use this earnings update on Five Below as your launchpad to compare other opportunities and sharpen your watchlist with fresh ideas.
- Target stronger upside potential by scanning companies trading below their estimated worth through the 29 high quality undervalued stocks.
- Prioritize staying power by focusing on financially resilient businesses with clean balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities by tracking fundamentally sound companies that most investors are still overlooking via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com