
Baidu (BIDU) Faces A Class Action, Is The Upside Still Credible?
Why a new class action puts Baidu (NasdaqGS:BIDU) under a legal spotlight
A fresh securities class action targeting Baidu (NasdaqGS:BIDU) has pulled legal risk to the forefront for shareholders, with claims centered on alleged misstatements about operations, growth prospects, and financial stability.
The lawsuit covers trades in Baidu securities between November 18, 2025 and August 17, 2026. It arrives after a difficult 2026 share performance, which has already pressured sentiment around the Chinese search and AI group.
Baidu’s latest legal setback lands after a tough run for the shares, with the 30-day share price return down 14.25% and the year-to-date move weaker still, while the 1-year total shareholder return has declined 38.14%.
The recent class action headlines appear to be reinforcing that pressure rather than creating it, as investors were already reacting to a 90-day share price return down 27.41% and a 5-year total shareholder return that has fallen 47.94%, which signals fading momentum around the US$85.30 level.
Spot opportunities beyond Baidu by scanning a curated 29 high quality undervalued stocks that aims to balance share price pressure with stronger cash flows and sturdier balance sheets.Bulls argue that Baidu’s AI assets and its recent revenue and net income growth matter more than the lawsuit and poor returns. Bears point to losses and the legal overhang. Which case does the valuation support next?
Most Popular Narrative: 42% Undervalued
Baidu’s most followed valuation narrative pegs fair value at $146.50, well above the recent $85.30 close. This puts the new lawsuit against a backdrop of already significant implied upside in the model.
The rapid rise in digitalization and urbanization across China is fueling increased engagement with online platforms and services, creating a larger addressable market for Baidu's AI-powered products. This secular shift underpins continued growth potential in core search, cloud, and new digital services, which should drive revenue upside as AI monetization progresses.
See why 176 investors see Baidu as 42% undervalued.
The narrative uses a 10.92% discount rate and ties that fair value to analyst expectations for Baidu’s earnings and margin profile over the coming years, while also baking in risks around advertising softness, AI investment, and regulation. For readers, the key question is whether those assumptions feel reasonable against a business that is currently loss making, with revenue of $127.3b and a reported net loss of $4.7b in the most recent year in the data provided.
Analysts behind this widely followed view are also split, with targets ranging from $80.24 to $206.59, which highlights how differently the market is treating Baidu’s AI cloud, autonomous driving and search monetization story. The fair value of $146.50 sits inside that band and implies that, if the underlying revenue growth, margin recovery and AI monetization thesis play out as expected, today’s share price gap could gradually narrow, although there is no assurance that will occur.
Result: Fair Value of $146.50 (UNDERVALUED)
Still, the Baidu narrative leans heavily on AI paying off while core search ads remain under pressure, and legal or regulatory action could unsettle sentiment further.
Find out about the key risks to this Baidu narrative.
Another View: Baidu Through The Cash Flow Lens
The popular Baidu narrative leans on a fair value of $146.50, yet the SWS DCF model tells a cooler story. On that framework, Baidu at $85.30 is trading slightly above an estimated future cash flow value of $81.11, which points to a modest premium rather than a clear bargain. So which lens do you trust more when legal and AI execution risks are both in play?
Look into how the SWS DCF model arrives at its fair value.
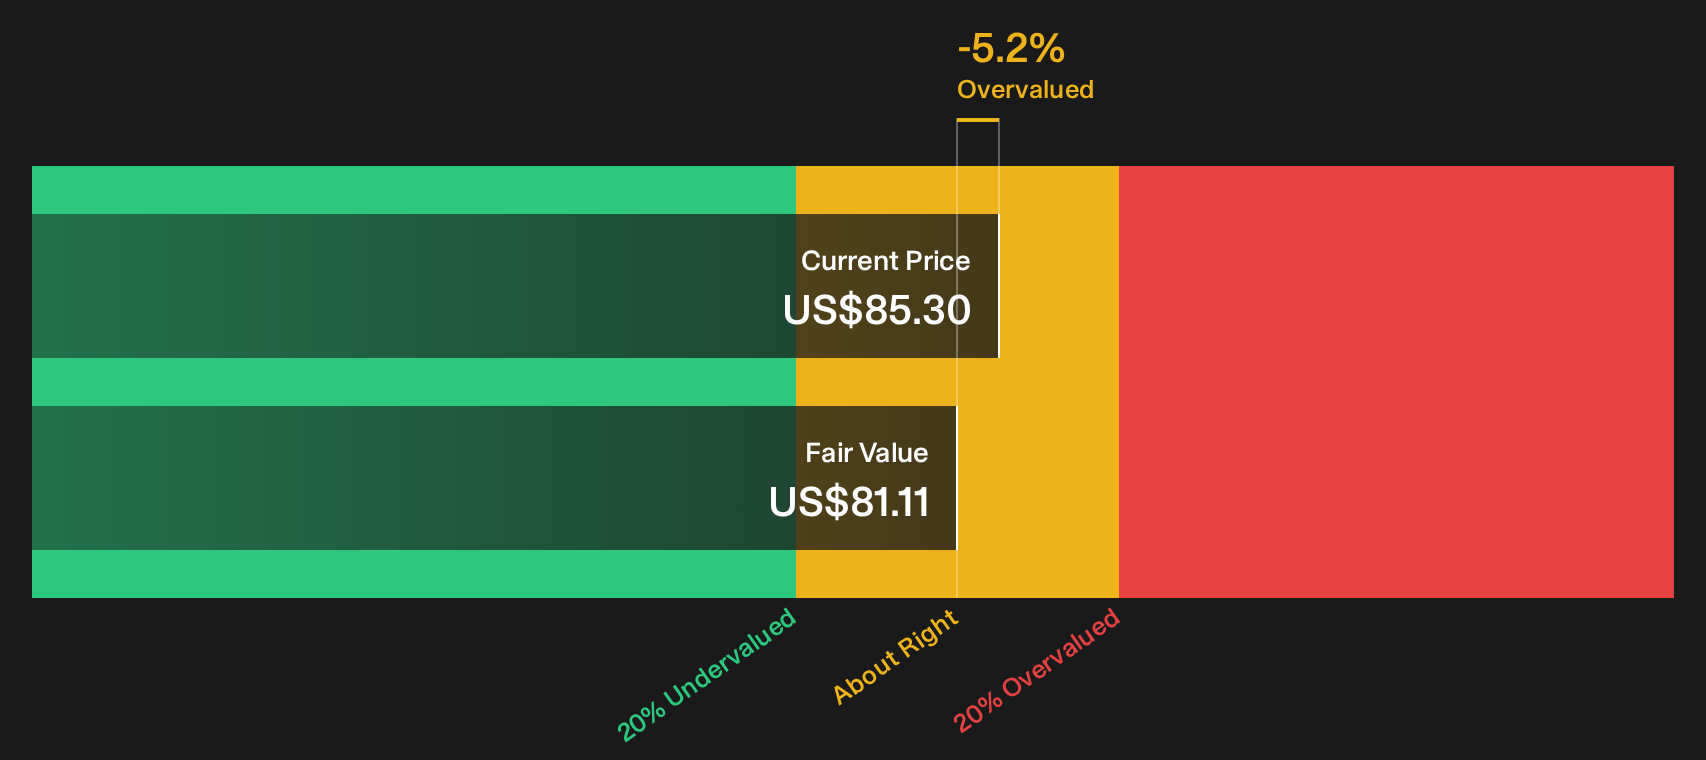
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Baidu for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Uncertain about whether the legal overhang or the AI optimism feels stronger in the Baidu story right now? Move quickly, examine the underlying figures for yourself, and pressure test your thesis against the 1 key reward.
Looking beyond Baidu for your next move
If Baidu has sharpened your focus on risk and reward, do not stop there. Broader idea hunting often reveals opportunities your current watchlist simply misses.
- Target potential mispricing by scanning a focused group of companies that screen as strong value candidates through the 29 high quality undervalued stocks.
- Prioritize resilience by reviewing a curated list of solid balance sheet and fundamentals (25 results) that aims to pair financial strength with healthier fundamentals.
- Hunt for less crowded opportunities by checking the 20 high quality undiscovered gems that filters for quality businesses flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com